

Is an OnDeck Business Line of Credit Right for Your Business?
An on deck business line of credit is a revolving credit product designed for small business owners who need fast, flexible access to working capital — without the red tape of a traditional bank loan.
Here’s what you need to know at a glance:
| Feature | Details |
|---|---|
| Credit limits | $6,000 to $200,000 |
| Minimum FICO score | 625 |
| Minimum annual revenue | $100,000 |
| Minimum time in business | 1 year |
| Repayment terms | 12, 18, or 24 months |
| Average APR | ~56.6% (as of June 30, 2025) |
| Collateral required | No |
| Funding speed | Same day; draws up to $10,000 in seconds |
| Draw fees / Annual fees | None |
OnDeck has funded more than 185,000 businesses and delivered over $25 billion across the U.S. since 2006. That track record makes it one of the more established names in online small business lending.
But fast and accessible doesn’t always mean cheap. With an average APR hovering around 56.6%, this product costs significantly more than a bank loan or SBA line of credit. It’s built for businesses that need capital quickly and can’t wait weeks for approval.
This article breaks down exactly how OnDeck’s line of credit works, what it costs, who qualifies, and how it compares to other options — so you can decide if it’s the right fit for your business.
Key Features of an On Deck Business Line of Credit
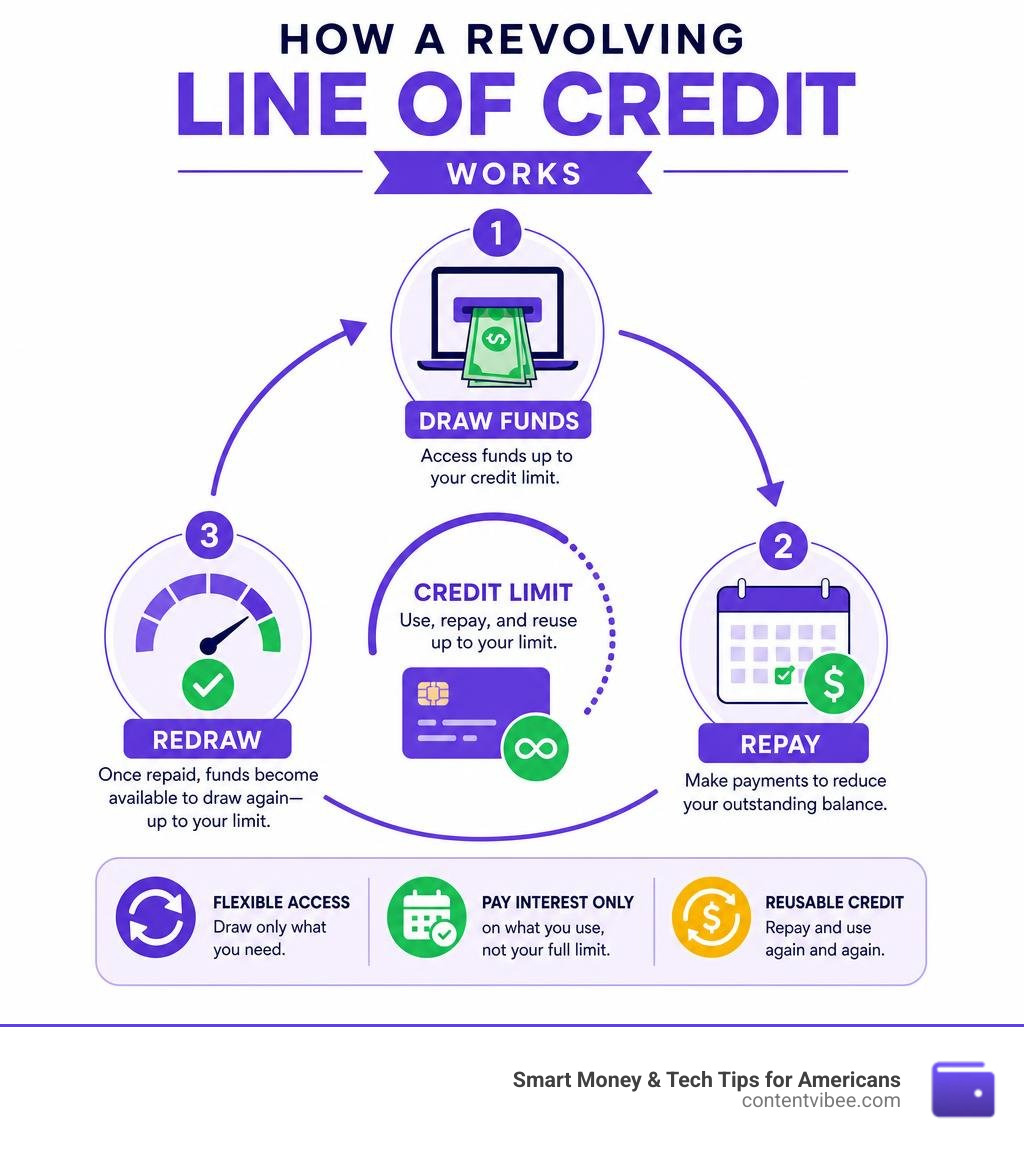
When we look at short-term business financing, flexibility is usually at the top of our wishlist. That is exactly what a revolving credit line offers. Unlike a standard term loan where you get a lump sum and start paying interest on the whole amount immediately, the on deck business line of credit allows you to draw only what you need, when you need it.
As you repay the balance, your available credit limit replenishes. It is like having a financial safety net that sits in the background, ready to rescue you when cash flow gets tight or a sudden growth opportunity knocks on your door.
Understanding Draw Limits and Repayment Terms
OnDeck’s revolving lines of credit range from a minimum of $6,000 up to a maximum limit of $200,000. When you are approved for a credit limit, you can choose to draw any amount above the minimum draw requirement (typically $1,000 for your initial draw).
Once you make a draw, you must repay that amount over a set term. OnDeck offers three distinct repayment term lengths:
- 12 months
- 18 months
- 24 months
Unlike traditional bank lines of credit that may only require monthly interest payments, OnDeck uses a more frequent repayment schedule. Depending on your business’s cash flow and creditworthiness, your payments will be automatically deducted from your business checking account on either a weekly or monthly basis.
While weekly payments can help smooth out cash flow by avoiding a massive end-of-month bill, they can also put a strain on businesses with highly volatile daily revenues. It is important to look at your bank statements and ensure your cash flow can handle the steady, frequent drafts.
Navigating the Costs and APR of an On Deck Business Line of Credit
Let’s address the elephant in the room: the cost. Online lenders offer speed and convenience, but they charge a premium for it.
As of February 2025, OnDeck reported an average APR of 57.10% for its business lines of credit. More recently, as of June 30, 2025, the average APR was reported at 56.6%. Depending on your business profile, your actual rate could range from around 35.90% to over 60+% APR. If you have pristine credit and strong bank balances, you will likely get a rate on the lower end, but it will still be higher than traditional bank financing.
Fortunately, OnDeck has an unusually clean fee structure for a non-bank lender. You can read more about this on their FAQs | OnDeck page. They do not charge:
- Draw fees (fees charged every time you pull money)
- Annual fees (to keep the line open)
- Monthly maintenance fees
- Prepayment penalties (you can pay off your balance early to save on interest)
This fee-free structure is a major plus. Many alternative lenders sneak in 1% to 3% draw fees, which can quickly eat into your capital. With OnDeck, you only pay the interest on the outstanding balance you have drawn.
Eligibility Requirements and Restricted Industries
One of the main reasons small businesses turn to online lenders is that traditional banks say “no” far too often. Traditional banks typically require stellar personal credit, years of profitable tax returns, and physical collateral. OnDeck takes a more holistic view of your business health, focusing heavily on your cash flow and revenue.
You can check your eligibility directly on Small Business Lending That’s Fast & Easy | OnDeck without hurting your credit score.
Minimum Qualifications for an On Deck Business Line of Credit
To qualify for an OnDeck line of credit, your business must meet the following baseline requirements:
- Minimum Personal FICO Score: 625 (for the primary business owner)
- Minimum Annual Revenue: $100,000
- Minimum Time in Business: 1 year
- Business Checking Account: Required (with healthy daily balances)
If you only meet these minimums, you may get approved, but you will likely receive a smaller credit limit and a higher APR. To get the best terms, OnDeck prefers businesses that meet their “preferred criteria,” which include:
- 2+ years in business
- $250,000+ in annual business revenue
- A personal FICO score of 675 or higher
- An average monthly bank balance of $3,000 or more
Excluded Sectors and Business Types
Even if you meet the financial requirements, your business might be ineligible based on your industry. Like most commercial lenders, OnDeck maintains a list of restricted industries due to regulatory or financial risks.
Some of the restricted sectors include:
- Adult entertainment and establishments
- Gambling and gaming activities
- Cannabis-related businesses
- Firearms and ammunition manufacturing or sales
- Financial services (e.g., payday lenders, check cashers)
- Government and public administration entities
Additionally, there are geographic restrictions. For example, OnDeck’s line of credit is currently not available to businesses operating in North Dakota.
The Application Process and Funding Speed
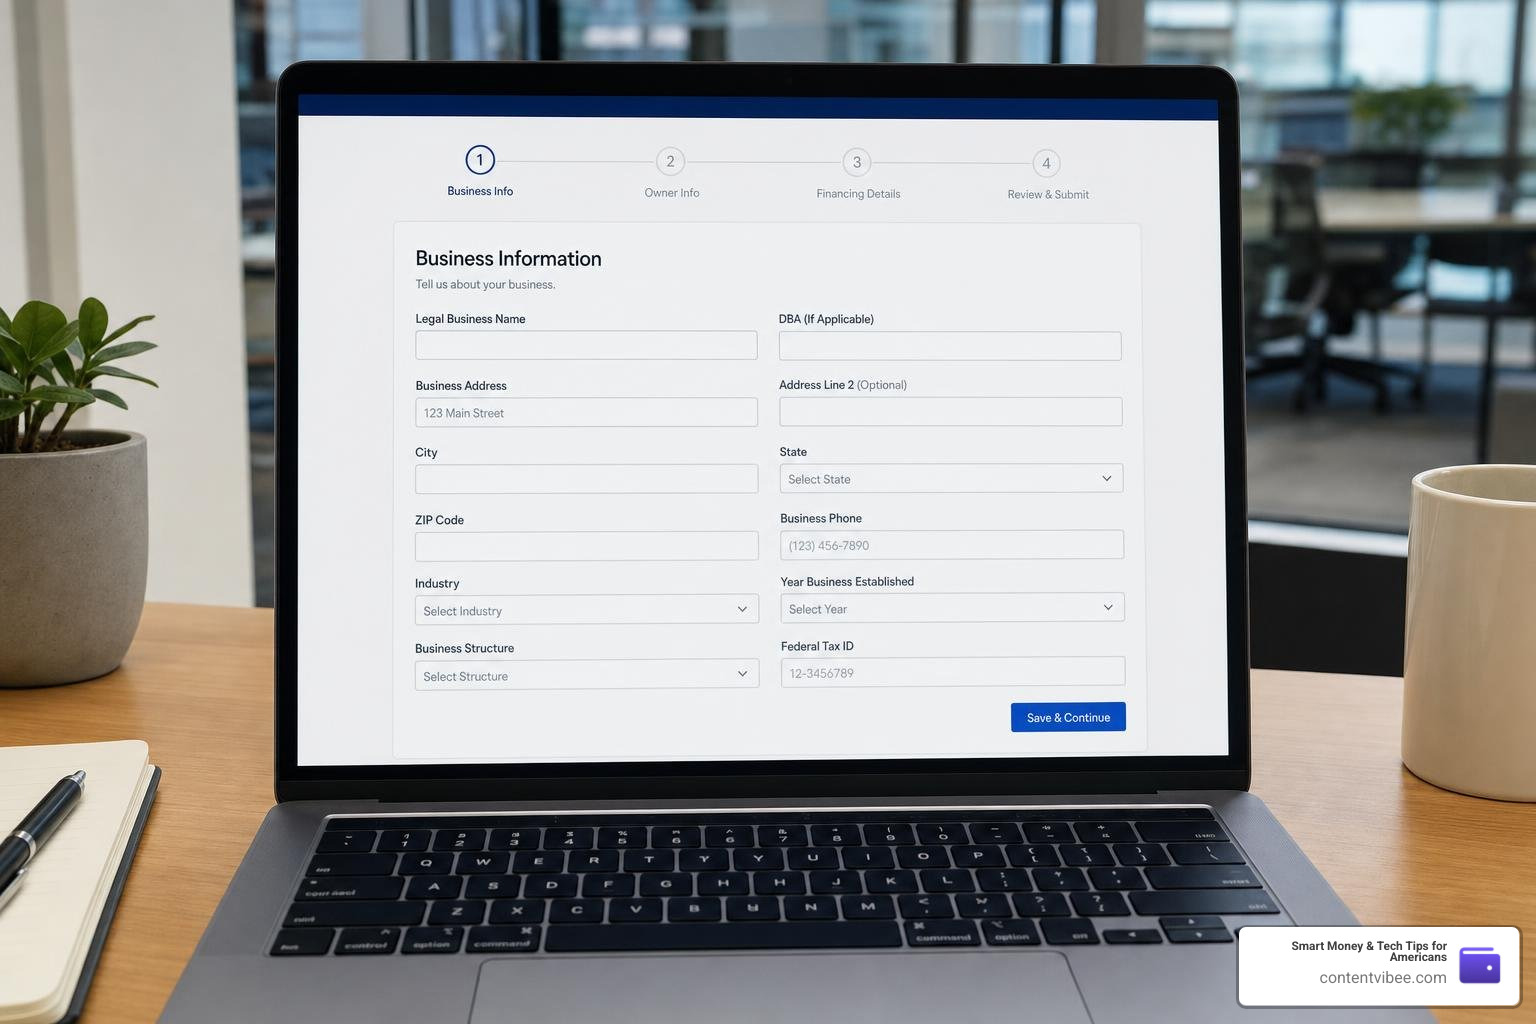
If you have ever applied for a commercial bank loan, you know it can feel like a part-time job. You have to gather years of tax returns, profit and loss statements, business plans, and personal financial statements. OnDeck has simplified this process into a digital experience that takes only a few minutes.
To apply, you will need to visit the OnDeck | Fast Business Financing portal and provide basic information about your business.
Soft Credit Pulls and Same-Day Approval
When you submit your initial application to check your eligibility, OnDeck performs a soft credit pull on your personal credit. This means you can see your funding options and rates without any negative impact on your personal credit score.
The application typically requires:
- Your Business Tax ID (EIN)
- Your Social Security Number (for identity verification and the soft credit check)
- Your last three months of business bank statements (usually linked digitally for instant verification)
Once submitted, OnDeck’s automated underwriting system evaluates your bank data and credit profile. In many cases, you will get a decision in minutes. If approved, a dedicated loan advisor will reach out to help you choose the best term length and finalize your setup. If you complete your application and checkout before 10:30 a.m. EST on a weekday, you can receive your funds in your account the same day.
Instant Funding vs. Standard ACH Transfers
Once your line of credit is active, drawing funds is incredibly fast. OnDeck offers two ways to access your money:
- Instant Funding: This is a standout feature of the OnDeck line of credit. If you link an eligible business debit card (associated with your business checking account on file), you can request a draw and receive the funds in your account in seconds — 24 hours a day, 7 days a week, including nights, weekends, and holidays. Instant Funding is limited to draws of $10,000 or less per day.
- Standard ACH Transfer: If you need to draw more than $10,000, or if your bank does not support push-to-debit transactions, you can use standard ACH. These transfers are processed during regular banking hours and typically take 1 to 2 business days to hit your account.
Comparing Lines of Credit to Traditional Term Loans
Many business owners get confused when deciding between a revolving line of credit and a traditional term loan. Both have their place, but they serve very different financial purposes.
If you are planning a one-time, large-scale project—like a major office renovation or buying heavy machinery—a term loan is usually the better choice. It gives you a lump sum upfront, and you pay it back over a fixed period.
However, if you are dealing with seasonal cash flow dips, buying inventory to prepare for a busy season, or needing a safety net for payroll, a line of credit is much more appropriate. You can read more about these differences on Business Funding | OnDeck.
Here is a direct comparison of the two structures:
| Feature | OnDeck Line of Credit | Traditional Term Loan |
|---|---|---|
| Funding Structure | Revolving (draw as needed) | Lump sum (one-time disbursement) |
| Interest Charged | Only on the amount you draw | On the entire loan balance from day one |
| Flexibility | High (reuse funds as you repay) | Low (must reapply for more funds) |
| Best For | Short-term cash flow, inventory, payroll gaps | Equipment purchases, expansion, major investments |
| Repayment Period | 12, 18, or 24 months | Typically 1 to 5+ years |
Frequently Asked Questions About OnDeck Financing
Does OnDeck require collateral or a personal guarantee?
OnDeck’s business line of credit is unsecured, meaning you do not have to pledge specific business assets (like real estate, equipment, or inventory) to secure the funding. This is a major benefit for service-based businesses that do not own substantial physical assets.
However, “unsecured” does not mean “risk-free.” OnDeck requires a personal guarantee from the primary business owner(s). If your business defaults on the debt, you are personally liable for repaying the remaining balance. Additionally, OnDeck may file a UCC-1 general lien on your business assets, which gives them a legal claim to your business property if the account goes into default.
How does this line of credit impact my business credit score?
Yes, you can use an OnDeck line of credit to build your business credit. OnDeck reports your payment history to major commercial credit bureaus, including Experian Business.
If you make your weekly or monthly payments on time, this positive payment history will be reflected on your business credit reports, helping you build a stronger business credit profile. Over time, this can make it easier to qualify for lower-interest financing from traditional banks. Conversely, late or missed payments will also be reported and can severely damage your business credit.
What are the best practices for managing a revolving line of credit?
Using a high-interest line of credit responsibly requires discipline. Here are three best practices we recommend to keep your costs down and your cash flow healthy:
- Borrow Only What You Need: Since interest starts accruing as soon as you draw funds, avoid the temptation to pull out extra cash “just in case.” Leave the rest of your credit limit untouched in your account where it doesn’t cost you a dime.
- Have a Clear Repayment Plan: Before you make a draw, know exactly how and when you will pay it back. If you are borrowing $15,000 to buy inventory for a holiday rush, ensure your expected sales will cover the weekly repayments.
- Keep Your Utilization in Check: Avoid keeping your line of credit maxed out. High credit utilization can signal financial distress to credit bureaus and may prevent OnDeck from increasing your credit limit in the future.
Conclusion
An on deck business line of credit is a powerful, fast, and highly flexible financial tool for small businesses that need immediate access to working capital. While the APRs are significantly higher than traditional bank loans, the lack of draw fees, the speed of same-day approval, and the game-changing 24/7 Instant Funding feature make it an incredibly convenient option for managing short-term business needs.
Before taking on any debt, it is crucial to analyze your business’s financial health and ensure that the return on your borrowed capital outweighs the cost of the interest. To help you plan your cash flow and understand your profitability, you can Calculate your business margins using ContentVibee’s free margin calculator tool.
With the right planning, a revolving line of credit can serve as a launchpad for your business’s next phase of growth.


