What Ethos Term Life Insurance Reviews Reveal in 2026
Ethos term life insurance reviews consistently point to one standout feature: you can get covered in about 10 minutes, no doctor’s visit required.
Here’s a quick snapshot of what reviewers and experts say in 2026:
| Source | Rating | Key Takeaway |
|---|---|---|
| Trustpilot | 4.8/5 (Excellent) | Fast process, friendly agents |
| NerdWallet | 4.6/5 | Strong consumer experience, low complaints |
| BBB | A+ | Accredited, responsive to issues |
| Google Reviews | 4.7/5 | Customers praise speed and pricing |
| MoneyGeek | 3.5/5 | Rates slightly above average for some |
Ethos is not a traditional insurance company. It’s a licensed broker and tech platform that sells policies underwritten by established carriers like Legal & General (Banner Life), Ameritas, Protective Life, and Mutual of Omaha.
That means the financial muscle behind your policy belongs to those carriers — Ethos simply makes buying much easier.
The appeal is real. One customer summed it up on Trustpilot: they got three times the coverage for about half the price they’d been quoted elsewhere. Another finished the entire application sitting in their car after grocery shopping.
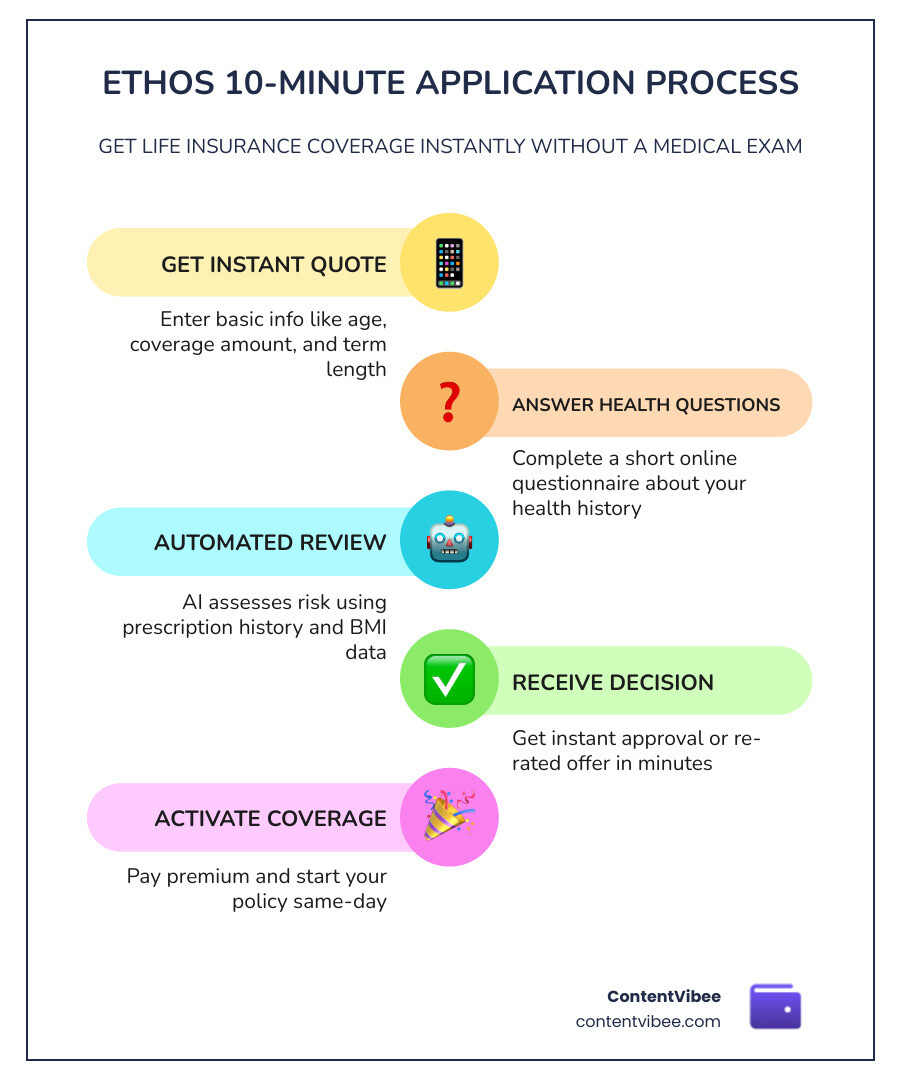
But not everyone’s experience is glowing. Some applicants find their final rate is higher than the advertised quote — especially if a prescription history check or BMI calculation triggers a re-rating.
So is Ethos the right fit for you? That depends on your health profile, coverage needs, and how much you value speed over price.
Comprehensive Ethos Term Life Insurance Reviews for 2026
As we navigate the financial landscape of May 2026, it’s clear that “insurtech” is no longer just a buzzword—it’s the standard. When we look at the aggregate data for ethos term life insurance reviews, the company maintains a formidable reputation. Major third-party reviewers have given Ethos high marks for its ability to strip away the “friction” of traditional life insurance.
According to the Ethos Life Insurance Review 2026, the company earned a 4.6 out of 5-star rating. This score is heavily weighted by the fact that Ethos partners with carriers that have fewer than the expected number of complaints to state regulators, as verified by NAIC data. Furthermore, the Ethos Life Insurance Review – Top Expert Guide (2026) highlights that the company’s A+ rating from the Better Business Bureau (BBB) reflects its commitment to resolving any customer friction points quickly.
While MoneyGeek provides a slightly more conservative score of 3.5 out of 5, this is largely due to their pricing analysis. They found that while the experience is top-tier, the “convenience tax”—a slightly higher premium for skipping the medical exam—might not appeal to the most budget-conscious shoppers who are in perfect health.
Analyzing Real Customer Ethos Term Life Insurance Reviews
Beyond the expert scores, what are people actually saying on the ground? On Trustpilot, Ethos holds an “Excellent” rating with 4.8/5 stars from over 4,700 reviews. The sentiment on Google is similarly positive at 4.7/5. Many customers express relief at finally checking “get life insurance” off their to-do list after years of procrastination.
However, if you head over to Reddit, the conversation gets a bit more nuanced. In threads like What’s the catch with Ethos Life Insurance? : r/LifeInsurance – Reddit, users discuss the trade-offs. The “catch” isn’t that the company isn’t legitimate—it’s very much so—but rather that the automated underwriting can be sensitive. For instance, some users report that an old prescription for anxiety or a slightly high BMI (Body Mass Index) led to a “re-rating,” where the final premium was higher than the initial quote.
We’ve found in our own ethos life insurance reviews that 95% of people who complete the application are approved as applied, but that remaining 5% often feels the sting of the algorithm’s strictness.
Policy Options and Coverage Limits
Ethos offers a surprisingly wide net of coverage. For those looking for term life, you can choose lengths of 10, 15, 20, 30, or even 40 years. This 40-year option is quite rare in the industry and is a huge win for young parents wanting to lock in a rate until their kids are well into adulthood.
- Coverage Amounts: $20,000 to $3 million.
- Eligibility Age: Generally 20 to 65 for term policies.
- No Medical Exam: Most applicants qualify for “simplified issue,” meaning no needles and no doctor visits.
For seniors or those with significant health issues, Ethos also provides guaranteed issue whole life options. If you’re wondering is whole life insurance a good investment, it’s important to note that Ethos’s whole life products are primarily designed for final expenses (burial costs) rather than complex wealth building, with coverage typically capped at $25,000 to $30,000 for those aged 66-85.
The Ethos Laddering System and Underwriting
One of the most innovative parts of the Ethos platform is its “laddering system.” Most insurance companies give you a “yes” or a “no.” If Ethos can’t approve you for their top-tier “Term Life Prime” policy, the system automatically checks if you qualify for “Term Life Choice,” then “Advantage Whole Life,” and finally “Guaranteed Acceptance.”
This means you aren’t just flat-out declined; you’re offered the next best thing. The underwriting process uses about 200 data points, including:
- MIB Group Records: A database of previous insurance applications.
- Pharmacy Databases: A history of your prescriptions (often the #1 cause of re-ratings).
- Motor Vehicle Reports: Your driving record (speeding tickets matter!).
If you have a complex medical history, you might want to learn what you need to know about index universal policies, which Ethos also offers for those looking for permanent coverage with cash value potential.
Comparing Costs and Sample Rates
How much will this actually cost you? While rates vary based on your specific “credit-based insurance score” and health, here are some sample monthly rates for a $500,000, 20-year term policy in 2026:
| Age | Gender | Monthly Rate (Excellent Health) |
|---|---|---|
| 30 | Female | $18.00 |
| 30 | Male | $23.00 |
| 40 | Female | $29.00 |
| 40 | Male | $38.00 |
| 50 | Female | $62.00 |
| 50 | Male | $81.00 |
Note: Smoking can double or even triple these rates. If you’re looking for why life insurance investment cash value growth is important, term insurance doesn’t build cash value—it’s pure protection for a set period.
Ethos performs a “soft” credit pull during this process. Don’t worry—this does not impact your credit score, but they use the data to help determine your risk level.
Final Verdict: Is Ethos Right for You?
At ContentVibee, we believe Ethos is a game-changer for the “average” American family. If you are a busy professional in Virginia or anywhere else in the U.S. (except New York), the convenience of getting a policy while on your lunch break is hard to beat.
The added perks are the “cherry on top.” Every Ethos term policy includes free estate planning tools, including the ability to create a legal will or living trust at no extra cost. They also include an accelerated death benefit rider, which allows you to access a portion of your payout if you are diagnosed with a terminal illness.
You can explore more options in our category/insurance/ section or find More financial tips and resources to help you budget for your new premium.
Key Benefits and Limitations in Ethos Term Life Insurance Reviews
To keep it simple, here is the “too long; didn’t read” (TL;DR) version of the pros and cons found in ethos term life insurance reviews:
The Pros:
- Speed: Same-day approval for 95% of applicants.
- No Exams: No needles for those who qualify.
- Financial Strength: Policies are backed by A-rated giants like Mutual of Omaha and Legal & General. You can see more about their Life Insurance Reviews & Ratings – Ethos.
- Perks: Free legal will and estate planning tools.
The Cons:
- Geography: Not available in New York.
- The “Convenience Tax”: If you are in perfect health and don’t mind a medical exam, you might find a slightly cheaper rate with a traditional carrier.
- Automated Declines: The algorithm can be unforgiving with certain medical histories (like recent cancer or heart conditions).
How to Apply and Claim Payouts
The application process is entirely digital. You’ll answer a series of health questions honestly. According to Ethos Life Insurance Review (May 2026) – MarketWatch, the interface is “sleek and seamless,” taking most users about 10 minutes from start to finish.
If the unthinkable happens, the claims process is handled by the underlying carrier (e.g., Banner Life or Ameritas). Because these are multi-billion dollar companies with high financial strength ratings, payouts are highly reliable. Beneficiaries typically need to provide a death certificate, and claims are often processed within days.
Just keep in mind the two-year contestability period. This is a standard industry rule where the carrier can investigate a claim if the death occurs within the first two years of the policy to ensure no fraud was committed during the application.
Our Take: If you want protection today without the headache of a medical exam, Ethos is arguably the best “one-stop-shop” in the 2026 market. It’s fast, it’s backed by heavy hitters, and it gives you a free will to boot. What’s not to love?