Ethos life insurance reviews consistently show one of the highest customer satisfaction scores in the insurtech space — but is it the right fit for you?
Here’s the quick answer:
| What You Want to Know | The Short Answer |
|---|---|
| Is Ethos legit? | Yes — licensed agency, A-rated underwriters, A+ BBB rating |
| Medical exam required? | No — most applicants approved online in ~10 minutes |
| Customer rating | 4.8/5 on Trustpilot (4,743+ reviews) |
| Coverage range | $15,000 to $3 million depending on policy type |
| Best for | Busy people who want fast, no-hassle coverage |
| Not ideal for | New York residents, those wanting the absolute lowest rates |
| Unique perk | Free will and estate planning tools (valued at ~$898) |
Life insurance has a reputation for being slow, confusing, and full of hoops to jump through. Ethos was built specifically to change that.
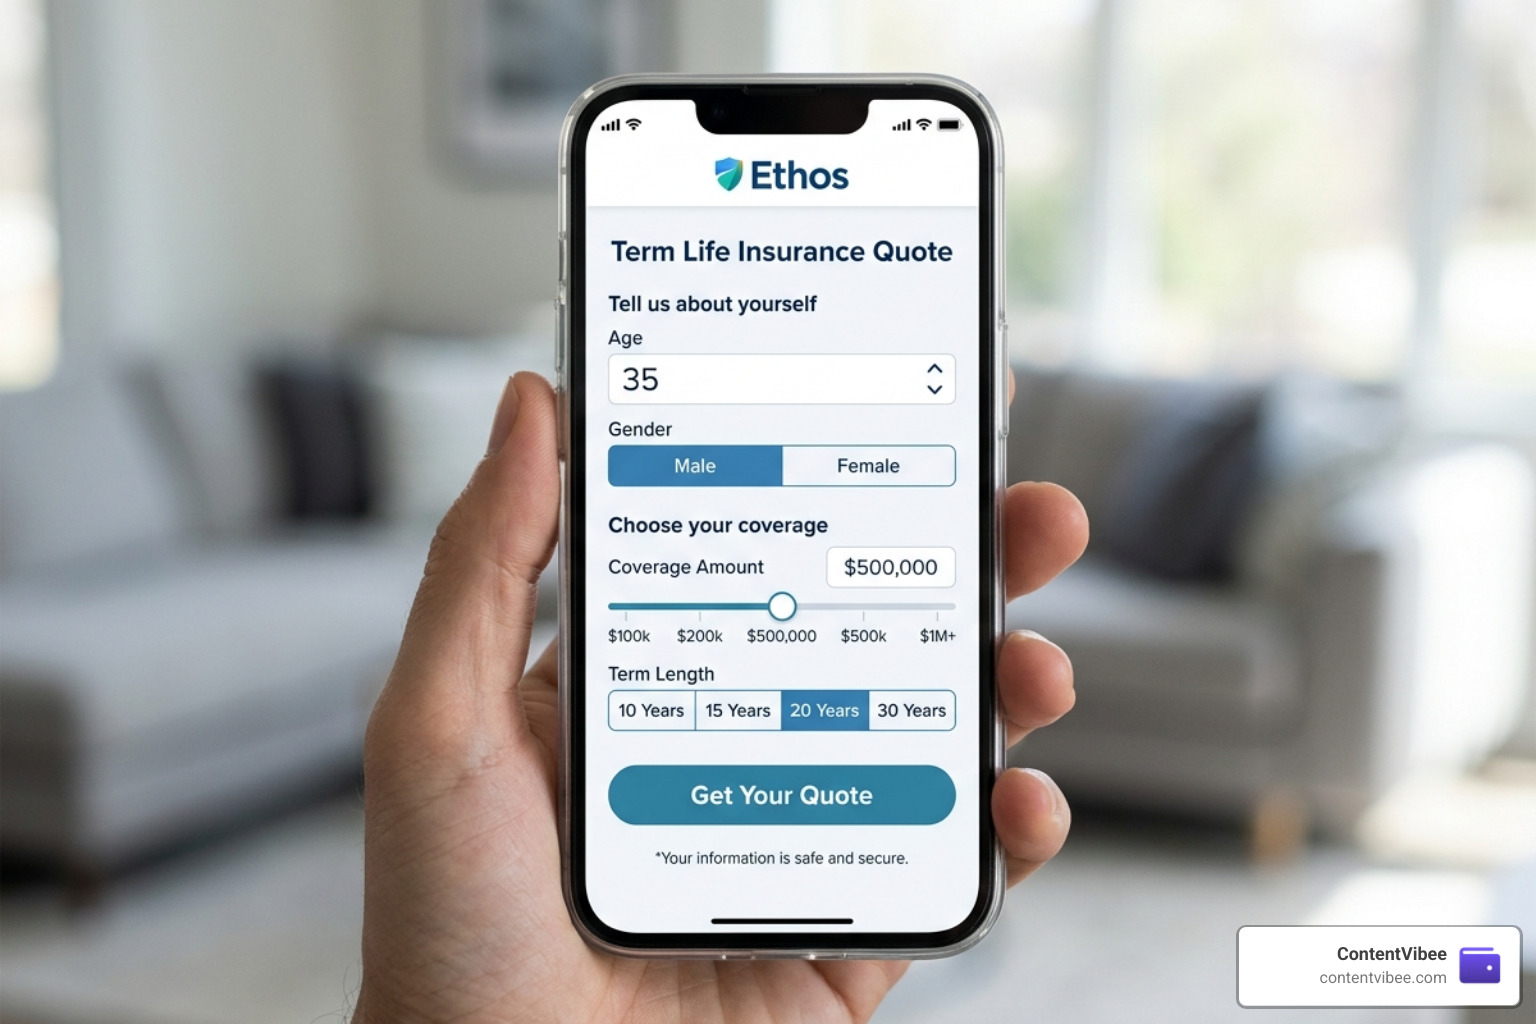
Founded in 2016, Ethos is a digital insurance broker — not a carrier itself — that connects applicants with policies from highly rated insurers like Legal & General America, Mutual of Omaha, and Ameritas. The whole process happens online, without a doctor’s visit, and often wraps up in about 10 minutes.
For first-time home buyers especially, that matters. A new mortgage is one of the biggest financial responsibilities you’ll ever take on. Getting life insurance in place quickly — so your family isn’t left with an unmanageable debt — is a smart, urgent priority.
But is Ethos actually as good as the ads suggest? That’s exactly what this guide breaks down.
What is Ethos Life Insurance and How Does it Work?
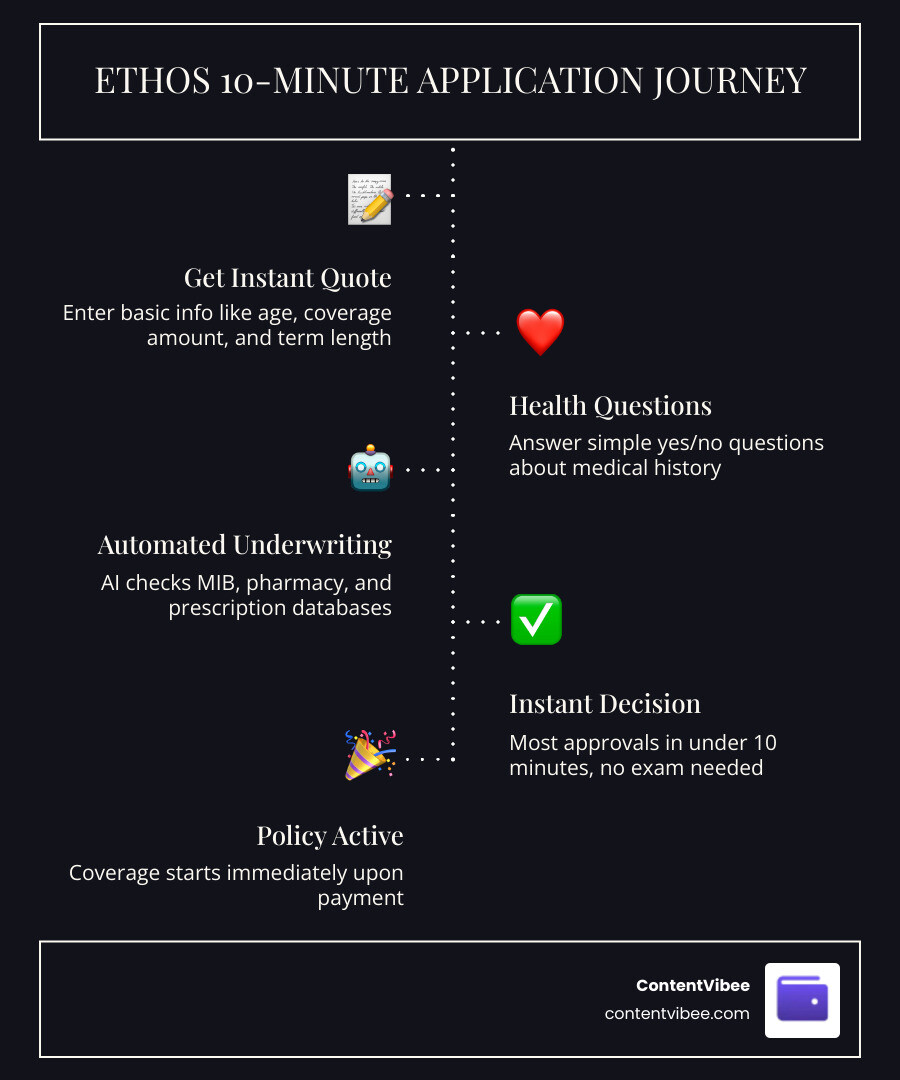
Ethos is a major player in the “insurtech” (insurance technology) world. Think of it as the modern bridge between you and traditional, century-old insurance companies. Instead of meeting an agent at a coffee shop and waiting weeks for a blood test result, we use Ethos to access a streamlined, digital-first platform.
As of May 2026, Ethos has matured into a formidable industry leader, even going public on the Nasdaq under the ticker symbol LIFE. But how does it actually work? Ethos operates as a digital broker. They don’t take on the risk themselves; instead, they use a proprietary algorithm to match you with policies issued by heavy hitters like Legal & General America, Ameritas, and Mutual of Omaha.
The “secret sauce” is their automated underwriting. When you apply, Ethos instantly checks several data points behind the scenes:
- MIB (Medical Information Bureau) records: A history of your previous insurance applications.
- Pharmacy databases: A look at your prescription history to gauge health risks.
- Motor Vehicle Records (MVR): To see if you have a penchant for speeding tickets or DUIs.
By analyzing these 200+ data points in real-time, Ethos can offer an Ethos Life Insurance Review 2026: Pros & Cons – NerdWallet that highlights their ability to approve 95% of applicants as applied without a single needle prick.
Understanding the Ethos Life Insurance Reviews and Ratings
If we look at the hard data, the ethos life insurance reviews are overwhelmingly positive. On Trustpilot, the company boasts a 4.8-star rating from over 4,700 customers. What’s even more impressive is their engagement; they reply to 98% of negative reviews, usually within 48 hours. This shows a level of accountability that’s rare in the financial sector.
The Better Business Bureau (BBB) awards them an A+ rating, and their underwriting partners typically hold AM Best ratings of “A” (Excellent) or better. According to Life Insurance Reviews & Ratings – Ethos, users frequently praise the “stress-free” nature of the application. While some forum discussions on Reddit mention aggressive follow-up calls if you leave an application unfinished, the general consensus is that the convenience is world-class.
How the Laddering System Impacts Ethos Life Insurance Reviews
One of the most innovative features we found in our research is the Ethos laddering system. In traditional insurance, if you don’t qualify for the “Prime” policy, you often just get a rejection letter. Ethos does things differently.
Their system acts as a safety net. If their algorithm determines you don’t qualify for their top-tier Term Life Prime policy, it automatically redirects your application to the next best fit, such as Term Life Choice or a Guaranteed Acceptance Whole Life policy. This optimization means you spend less time reapplying and more time covered.
Analyzing Ethos Life Insurance Reviews: Pros, Cons, and Legitimacy
Is Ethos legitimate? Absolutely. They’ve raised over $400 million in venture capital from big names like Jay-Z and Sequoia Capital. However, “legitimate” doesn’t always mean “perfect for everyone.”
The Pros:
- No Medical Exams: This is the big one. Most healthy people under 65 can get up to $2 million (and sometimes $3 million) in coverage just by answering questions on their phone.
- Speed: You can literally get covered while waiting for your laundry to dry.
- Financial Strength: Because they partner with giants like Mutual of Omaha, you don’t have to worry about the company disappearing when it’s time to pay a claim.
The Cons:
- Geographic Restrictions: If you live in New York, you’re out of luck. Ethos does not currently offer policies there.
- Limited Conversion: Unlike some traditional policies, Ethos term plans often cannot be converted into permanent whole life plans later on.
- The “Convenience Premium”: As noted in the 2026 Ethos Life Insurance Review: Rates, Pros & Cons, you might pay a few dollars more per month for the luxury of skipping the medical exam.
Common Reasons for Denials in Ethos Life Insurance Reviews
Even with a 95% approval rate, some people do get turned away or hit with higher rates. We see this often in ethos life insurance reviews where customers are surprised by a “re-rating.” Common triggers include:
- BMI and Lifestyle: Body Mass Index issues account for 20-25% of price hikes during the application.
- Prescription History: If you’re taking medication for a chronic condition you didn’t mention, the pharmacy database check will flag it.
- High-Risk Hobbies: If you spend your weekends skydiving or scuba diving at extreme depths, the automated system might flag you for a manual review or denial.
- Credit Score: While it’s only a “soft check” that doesn’t hurt your score, a poor credit-based insurance score can lead to higher premiums.
For those looking for more “investment-heavy” options, you might wonder Is Whole Life Insurance A Good Investment/. Ethos does offer whole life, but it is primarily designed for final expenses rather than high-growth wealth accumulation.
Policy Options and the Cost of Convenience
Ethos offers a surprisingly wide range of products for a digital platform. While many competitors stick to simple term life, Ethos includes permanent options as well.
| Policy Type | Coverage Limits | Best For |
|---|---|---|
| Term Life | $100k – $3M | Families, mortgage protection, income replacement |
| Whole Life | $1,000 – $30,000 | Seniors (66-85), funeral costs |
| Indexed Universal Life | Up to $1M+ | Those wanting cash value growth tied to market indexes |
For a healthy 40-year-old male, a $500,000 20-year term policy averages around $38/month. A female of the same age might see rates around $29/month. While you can find cheaper rates if you are willing to undergo a full medical exam with a traditional carrier, the “cost of convenience” here is usually just the price of a couple of lattes.
If you’re interested in how these policies build value over time, check out Why Life Insurance Investment Cash Value Growth/ and our guide on What You Need To Know About Indexed Universal/.
Beyond Coverage: Free Wills and Estate Planning Benefits
One of the most significant “hidden” values mentioned in ethos life insurance reviews is their estate planning suite. Ethos provides a free legal will and living trust service valued at approximately $898.
In our experience at ContentVibee, we see many home buyers focus entirely on the mortgage and forget about the legal paperwork that dictates what happens to that home. Ethos solves this by bundling:
- Last Will and Testament: Decide who gets your assets.
- Living Trust: Help your heirs avoid the long, expensive probate process.
- Healthcare Directive: Make your medical wishes known.
This isn’t just a “budget” version, either. It’s a comprehensive digital dashboard that allows you to manage your estate plan entirely from your smartphone. As highlighted in the Ethos Life Insurance Review – Top Expert Guide (2026), this makes Ethos a “one-stop-shop” for family financial protection. It’s as essential for your family’s future as understanding Health Insurance Options For Every American Family/.
Frequently Asked Questions about Ethos
Is Ethos Life Insurance legitimate and safe?
Yes. Ethos is a licensed insurance agency that has been around since 2016. They are backed by massive investment firms and partner with “A” rated carriers like Legal & General America and Mutual of Omaha. These partners are the ones who actually pay out the claims, ensuring your money is safe.
Does Ethos require a medical exam for all applicants?
No. In fact, the majority of Ethos applicants qualify for “simplified issue” policies that require zero medical exams. You simply answer health and lifestyle questions online. Only in rare cases involving complex medical histories might a further review be required.
How long does the Ethos application process take?
The actual application usually takes about 10 minutes. Because they use instant data verification, many people receive an approval decision the same day — often immediately after hitting “submit.”
Conclusion: Is Ethos Life Insurance Worth It in 2026?
At ContentVibee, we believe that the best insurance policy is the one you actually have in place. Too many people delay getting coverage because they dread the medical exam or the paperwork. Ethos removes those barriers.
If you are a busy professional, a new parent, or a homeowner looking to protect your mortgage, Ethos is a fantastic choice. The combination of a 10-minute application and nearly $900 in free estate planning tools makes it a “no-brainer” for the modern consumer. While you might save a few dollars elsewhere by doing a blood test, the time and peace of mind you gain with Ethos are well worth the trade-off.
For more insights into protecting your future, explore our more info about insurance categories or, if you’re ready to secure a home to protect, start your real estate journey today.