


Finding the Best Health Insurance for Self Employed California
Finding the best health insurance for self-employed workers in California comes down to a few key options — and for most people, Covered California is the clear winner.
Quick Answer: Best Health Insurance Options for Self-Employed Californians in 2026
| Option | Best For | Subsidy Eligible? |
|---|---|---|
| Covered California (Silver plan) | Most self-employed Californians | Yes |
| Covered California (Bronze HDHP + HSA) | Healthy, low-utilization freelancers | Yes |
| Covered California (Gold plan) | Frequent medical users | Yes |
| Medi-Cal | Income below 138% FPL (~$20,783/yr) | N/A (free) |
| Private off-exchange plan | High earners above subsidy limits | No |
Being your own boss has real perks. But one thing that catches a lot of freelancers, gig workers, and independent contractors off guard? Health insurance is now entirely your responsibility.
More than 16 million Americans are self-employed — and 1 in 4 of them have no health coverage at all. In California, that gap is especially costly. The state has its own individual mandate, meaning you can face a penalty of up to $900 per adult just for going uninsured.
The good news: California’s health insurance landscape in 2026 is genuinely favorable for self-employed people. 4 out of 5 Covered California enrollees qualify for financial help, and some pay as little as $10–$75 per month after subsidies.
This guide walks you through every option, every number, and every strategy you need to get covered without overpaying.
Best health insurance for self employed california terms at a glance:
- average mesothelioma settlement amounts
- mesothelioma compensation for family members
- what is the average settlement for asbestos claim
When we look for the best health insurance for self employed california, we have to start with Covered California. It is the only place where self-employed individuals can access federal premium tax credits and state-specific subsidies. If you earn between $20,783 and $83,120 as a single person in 2026, these subsidies can reduce your Silver plan premiums to as little as $10 to $400 a month.
Beyond the exchange, there are three primary paths:
- Covered California: Ideal for those who qualify for subsidies. It offers standardized plans from big-name carriers.
- Medi-Cal: If your Modified Adjusted Gross Income (MAGI) is below 138% of the Federal Poverty Level (about $20,783 for an individual), you may qualify for free or low-cost coverage through the state’s Medicaid program.
- Private Off-Exchange Plans: If your income is significantly high (e.g., a family of four earning well over $150,000), you might look at plans directly from insurers like Blue Shield or Kaiser, though you won’t get any tax credits this way.
For more details on how these programs work, you can visit the official Self-Employed People | Covered California™ page.
| Plan Tier | Premium Cost | Out-of-Pocket Cost | Best For |
|---|---|---|---|
| Bronze | Lowest | Highest | “Just in case” coverage; healthy people |
| Silver | Moderate | Moderate | The “sweet spot” with Cost-Sharing Reductions |
| Gold | High | Low | Regular doctor visits or prescriptions |
| Platinum | Highest | Lowest | Chronic conditions or planned surgeries |
How to Choose the Best Health Insurance for Self Employed California Based on Metal Tiers
Choosing a “metal tier” is a balancing act between what you pay every month (premiums) and what you pay when you see a doctor (deductibles and copays).
- Bronze HDHP: These plans have the lowest premiums. They are often “High-Deductible Health Plans,” which allow you to open an HSA (Health Savings Account).
- Silver 70: This is often the best health insurance for self employed california because of Cost-Sharing Reductions (CSR). If your income falls within certain limits, a Silver plan is “enhanced,” meaning your deductible and out-of-pocket maximum drop significantly while your premium stays low.
- Gold 80 & Platinum 90: If you know you have a surgery coming up or you see a specialist monthly, paying a higher premium is worth it to avoid a $5,000+ deductible.
For families, the stakes are even higher. You can learn more about health insurance options for every American family to see how to balance these tiers for children and spouses.
Maximizing Subsidies and the Best Health Insurance for Self Employed California
Subsidies are calculated based on your Modified Adjusted Gross Income (MAGI). For most of us, MAGI is our total business income minus business expenses (like home office, supplies, and marketing).
The trick for the self-employed is that subsidies are based on your projected income for 2026, not what you made last year. If you overestimate your income, you might miss out on thousands of dollars in monthly savings. If you underestimate, you might have to pay some of that subsidy back at tax time.
Strategic ways to lower your MAGI include:
- Making contributions to a SEP-IRA or Solo 401(k).
- Deducting 100% of your health insurance premiums.
- Maximizing business expenses like mileage (the 2024 rate was 67 cents per mile; keep an eye on 2026 updates!).
According to Marketplace savings research, even a family of four earning up to $150,000 can still qualify for some level of assistance in California.
Tax Deductions and HSAs for Freelancers
One of the best “hacks” for the self-employed is the above-the-line deduction for health insurance premiums. Unlike W-2 employees, we can deduct 100% of our health insurance premiums directly on Form 1040, Schedule 1. This reduces your taxable income even if you don’t itemize.
Additionally, if you choose a Bronze HDHP, you can use a Health Savings Account (HSA). In 2026, the contribution limits are:
- Individual: $4,300
- Family: $8,550
- Age 55+: Additional $1,000 catch-up contribution.
HSAs offer a “triple tax advantage”: the money goes in tax-free, grows tax-free, and comes out tax-free for medical expenses. Plus, unlike an FSA, the money rolls over every year.
Enrollment Strategies and Avoiding Common Mistakes
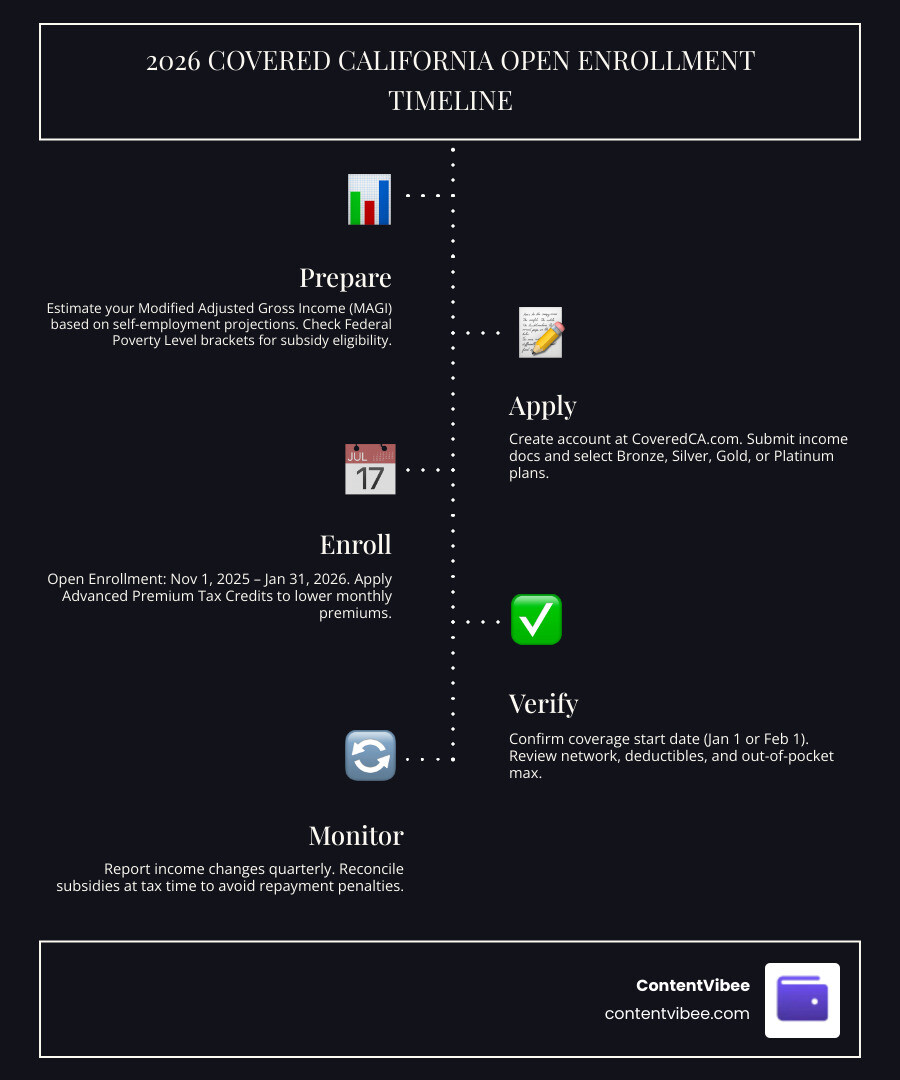
The standard Open Enrollment Period usually runs from November 1 to January 31 in California. If you miss this window, you can only enroll if you have a Qualifying Life Event (Special Enrollment Period), such as:
- Losing job-based coverage.
- Getting married or having a child.
- Moving to a new zip code.
- A significant change in income that makes you newly eligible for subsidies.
Don’t forget the California individual mandate. If you go without coverage, you could face a state tax penalty of $900 per adult and $450 per child. That’s money down the drain that could have gone toward a subsidized plan.
Managing Variable Income and Mid-Year Updates
We know that freelance income is rarely a straight line. You might have a “whale” client in March and nothing in July.
The Golden Rule: Update Covered California within 30 days of a major income change.
- Income goes up? Reporting it now prevents a massive “clawback” of subsidies when you file your taxes.
- Income goes down? Reporting it now could lower your monthly premium immediately, helping your cash flow.
In 2026, there are reconciliation caps for those under 400% of the Federal Poverty Level, but it’s always safer to keep your account updated quarterly.
Individual Plans vs. Small Business SHOP Options
Are you a “solopreneur” or do you have a team?
- Self-Employed (No Employees): You must use the individual marketplace. You, your spouse, and your children count as one unit.
- Small Business (1+ W-2 Employees): If you have at least one non-owner employee, you may qualify for the SHOP Marketplace (Small Business Health Options Program).
SHOP plans can sometimes offer better rates and allow you to claim the Small Business Health Care Tax Credit, which can cover up to 50% of the premiums you pay for your employees. However, for a family-run business with no outside staff, the individual Covered California route is usually simpler and more cost-effective.
Conclusion: Securing Your Financial Future
At ContentVibee, we believe that smart money management is the key to a successful self-employed life. Securing the best health insurance for self employed california isn’t just about doctor visits; it’s about protecting your savings from a single $30,000 hospital bill.
Before you sign up, run your numbers through a settlement calculator or an income estimator to see exactly where you stand.
Your Final Checklist:
- Estimate your 2026 MAGI (Income minus business expenses).
- Compare Silver vs. Bronze HDHP plans on Covered California.
- Check if your preferred doctors are in-network (HMO vs. PPO).
- Open an HSA if you choose an HDHP.
- Mark your calendar to update your income every three months.
By taking an hour now to navigate these options, you could save $3,000–$8,000 a year in premiums and taxes. That’s more money to reinvest in your business and your future. For more practical tips, explore our guide on mesothelioma compensation for family members or other financial planning resources.


