The Hard Truth About Divorce Legal Fees and Your Taxes
Divorce legal fees are not tax deductible for most Americans under current federal law.
Here is what you need to know right away:
| Expense Type | Deductible? |
|---|---|
| General divorce attorney fees | No |
| Child custody legal fees | No |
| Property division legal fees | No |
| Mediation and court filing fees | No |
| Legal fees for tax advice during divorce | No (permanently repealed) |
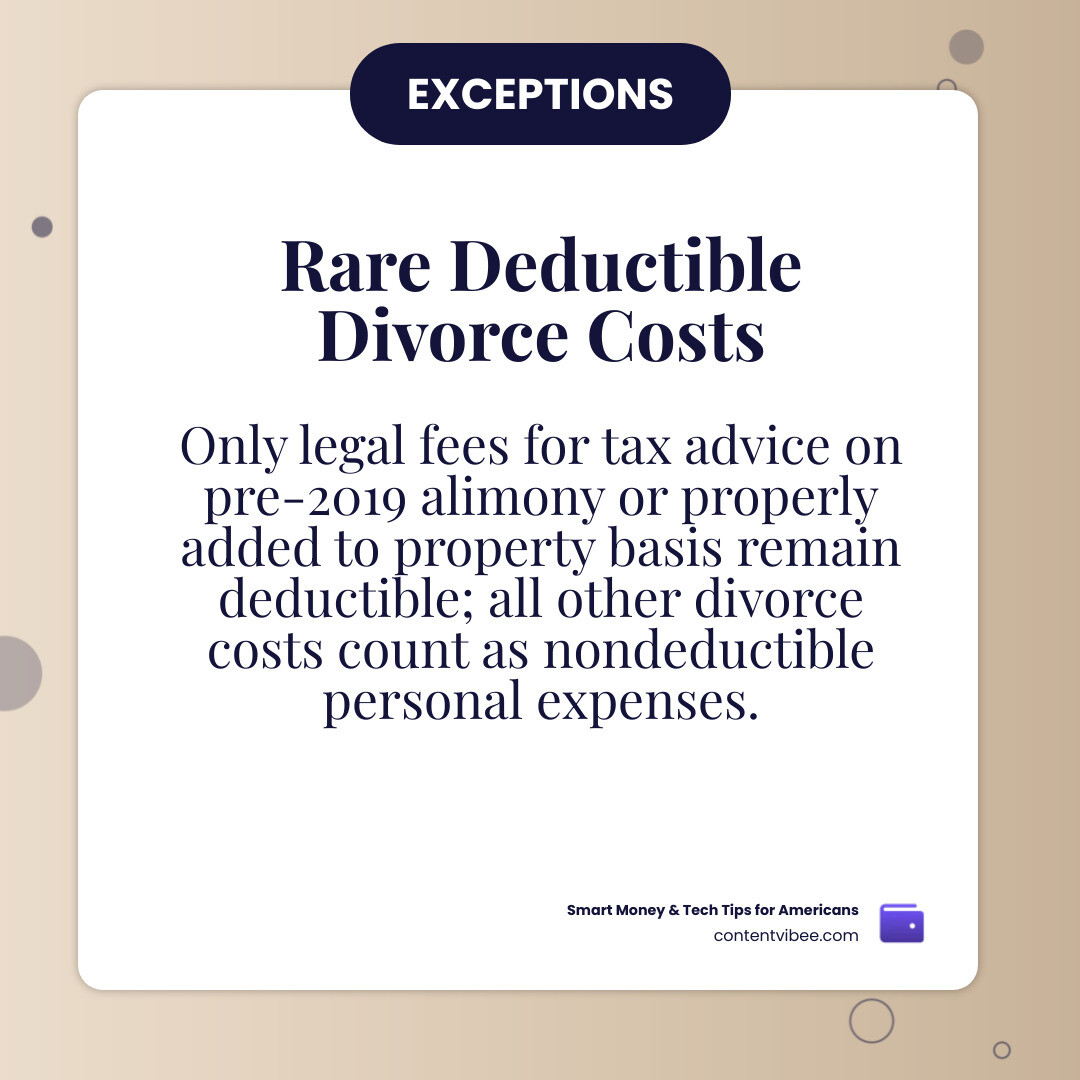
| Legal fees to collect taxable alimony (pre-2019 divorces only) | Extremely limited |
| Adding legal fees to property cost basis | Sometimes — reduces future capital gains |
The rules changed dramatically starting in 2018, and a 2025 law made those changes permanent.
If you are going through a divorce right now, this matters. The average divorce costs around $12,900, with roughly $11,300 going to attorney fees alone. That is a massive out-of-pocket hit — and almost none of it reduces your tax bill.
It wasn’t always this way. Before 2018, some narrow deductions were available. But the Tax Cuts and Jobs Act (TCJA) stripped most of them away, and the One Big Beautiful Bill Act of 2025 permanently closed the door on the rest.
Understanding exactly where the line is drawn can help you avoid costly filing mistakes — and spot the rare exceptions that might still apply to your situation.
Are Divorce Legal Fees Tax Deductible Under Current Federal Law?
As we navigate the tax landscape of May 2026, the short answer remains a firm “no” for the vast majority of taxpayers. According to the Internal Revenue Service (IRS), the costs associated with ending a marriage are viewed as personal expenses rather than business or investment expenses.
The primary authority on this is Publication 504 (2025), Divorced or Separated Individuals | Internal Revenue Service. This document explicitly states that legal fees for obtaining a divorce are nondeductible. This includes the costs of counseling, legal advice on personal matters, and the standard litigation involved in dissolving a union.
When we look at Navigating the Financial Maze of Family Law Costs, we see that while these costs are a significant burden, the tax code treats them with the same “personal” designation as your groceries or your rent. Under Section 262 of the Internal Revenue Code (IRC), personal, living, or family expenses are strictly barred from being deducted unless specifically allowed elsewhere in the code. Unfortunately for those in the middle of a split, the “elsewhere” has largely vanished.
Why Most Divorce Legal Fees Tax Deductible Claims are Denied
The IRS is very clear: a divorce is a personal life event. Even if your divorce involves complex arguments over who gets the family business or how to split a massive stock portfolio, the “origin” of the dispute is your marriage.
Under IRC Section 262, the following are almost always considered nondeductible:
- Legal advice regarding child custody or visitation.
- Fees for personal counseling or therapy during the divorce.
- The cost of drafting a simple divorce decree.
- General litigation fees to settle “who gets what” in the house.
Because these expenses arise from a personal relationship rather than a business transaction, they don’t qualify for tax relief. We often see people trying to argue that because the divorce is expensive, it should be subsidized by a tax break. However, as explored in our guide on How Much Do Divorce Lawyer Fees Really Cost?, the high price tag doesn’t change the personal nature of the expense.
Tax Treatment of Alimony and Related Divorce Legal Fees Tax Deductible Status
One of the biggest shifts in recent history involves alimony. If your divorce was finalized after December 31, 2018, alimony is no longer deductible for the person paying it, and it is no longer considered taxable income for the person receiving it.
This change had a “domino effect” on legal fees. Historically, if you were the spouse receiving alimony, you could sometimes deduct the legal fees spent to secure that alimony because you were essentially paying fees to generate taxable income. But since alimony is no longer taxable for new divorces, there is no “taxable income” being generated, and thus, no legal basis for a deduction.
For those with older agreements (pre-2019), the old rules may still apply, but even then, the ability to claim these as miscellaneous deductions has been suspended. For more on these evolving rules, check out our Legal Guides section.
How the TCJA and 2025 Legislation Changed Everything
To understand why divorce legal fees tax deductible status is so rare today, we have to look at the legislative timeline. The Tax Cuts and Jobs Act (TCJA) of 2017 was the first major blow. It suspended “miscellaneous itemized deductions” for tax years 2018 through 2025.
Before this, you could deduct legal fees for tax advice or for the production of income (like alimony) if those fees, combined with other miscellaneous costs, exceeded 2% of your Adjusted Gross Income (AGI).
The Permanent Repeal of Miscellaneous Itemized Deductions
Many taxpayers were holding their breath, hoping the TCJA provisions would “sunset” at the end of 2025, bringing back the old deductions in 2026. However, the One Big Beautiful Bill Act of 2025 made the repeal of these miscellaneous deductions permanent.
This means that Section 212 deductions—which previously allowed for the deduction of fees related to tax preparation, investment advice, and the collection of taxable income—are gone for good. Whether you are paying for an accountant to value your marital assets or a lawyer to give you tax planning advice during the split, these are now considered 100% personal, nondeductible costs.
| Rule Component | Pre-2019 Divorces | Post-2018 Divorces (Current 2026) |
|---|---|---|
| Alimony Payer | Deductible | Non-deductible |
| Alimony Recipient | Taxable Income | Tax-free |
| Legal Fees for Tax Advice | Deductible (subject to 2% AGI) | Not Deductible |
| Legal Fees for Income | Deductible (subject to 2% AGI) | Not Deductible |
The “Origin of the Claim” Test: Why Business Owners Can’t Deduct Divorce Costs
If you own a business, you might think, “I’m paying my lawyer to protect my company from my ex-spouse. That’s a business expense!”
We wish it were that simple. The IRS and the courts use what is called the “Origin of the Claim” test. This legal standard comes from a famous Supreme Court case, United States v. Gilmore. The court ruled that the deductibility of legal fees depends on the origin of the claim, not the consequences to your wealth.
Protecting Business Assets vs. Personal Marital Claims
In the Gilmore case, the husband spent a fortune in legal fees to prevent his wife from taking his controlling interest in three General Motors dealerships. He argued that if he lost the dealerships, his livelihood would be destroyed. The Court disagreed, stating that the “claim” originated from his marriage and divorce, which are personal. Therefore, his $3 million in legal fees were nondeductible personal expenses.
This was reinforced recently in Lucas v. Commissioner (2018). The taxpayer attempted to deduct over $3 million in fees related to investment partnership distributions. Even though the money involved was business-related, the court held that because the dispute was part of a divorce settlement, the fees were personal.
Unless you are defending against a spouse who is literally interfering with your business operations (for example, sabotaging your clients or physically blocking your office), you cannot claim these fees as business expenses on a Schedule C. For a deeper dive into these nuances, Legal Fees for Divorce: What’s Deductible? – DivorceNet provides excellent context on nationwide standards.
Strategies to Offset Costs: Basis Adjustments and State Rules
While you can’t deduct the fees on your 1040 form this year, there is one “silver lining” strategy: Basis Adjustment.
Under IRC Section 1041, property transfers between spouses during a divorce are generally tax-free. However, the spouse receiving the property also “inherits” the original cost basis. If you spend significant legal fees to secure a specific piece of property (like the family home or a rental building), you may be able to add those legal costs to the “basis” of the property.
Can I Deduct Legal Fees for Tax Advice or Financial Planning?
Adding fees to the basis doesn’t give you a tax refund today, but it reduces your capital gains tax when you sell the property in the future.
Example:
- You receive a house worth $500,000 in the divorce.
- The original cost basis (what you and your ex paid for it) was $200,000.
- You paid $10,000 in legal fees specifically to secure the title to that house.
- Your new basis is $210,000.
- When you sell for $600,000, your taxable gain is $390,000 instead of $400,000.
Regarding state-specific rules, if you are in California, you should be aware that state tax laws often mirror federal laws, but there can be subtle differences. In California, attorney fees for the production or collection of income (like pre-2019 alimony) might still have some life at the state level, though the Franchise Tax Board (FTB) has tightened these rules significantly. You can find more specific details here: Are Divorce Attorney Fees Tax Deductible in California?.
Always remember that Divorce Costs: Why Your Ex Might Be Your Most Expensive Hobby, so utilizing every available strategy like basis adjustment is vital for your long-term financial health.
Frequently Asked Questions about Divorce Legal Fees
Are court filing fees, mediation costs, or expert witness fees deductible?
No. Just like attorney fees, court filing fees, mediation costs, and fees for expert witnesses (such as forensic accountants or child custody evaluators) are considered personal expenses. Even though these are necessary to complete the legal process of divorce, they do not qualify for a federal tax deduction in 2026.
What happens if I am ordered to pay my ex-spouse’s attorney bills?
If a judge orders you to pay your ex-spouse’s legal fees, those payments are generally treated as a non-taxable transfer of funds (similar to a property settlement). You cannot deduct them, and your ex-spouse does not have to report them as income. It is a “tax-neutral” event that unfortunately leaves you with a smaller bank account and no tax relief.
What are the record-keeping requirements for future tax claims?
Even though you can’t claim a deduction today, you must keep impeccable records. If you ever want to use the “basis adjustment” strategy mentioned above, the IRS will require proof of what you paid and exactly what the legal work covered.
Essential Documents to Save:
- Itemized Invoices: Ask your attorney to break down their bill. “General representation” isn’t enough. You want to see specific lines for “Property Settlement Negotiation” or “Title Transfer Work.”
- Proof of Payment: Keep canceled checks or credit card statements.
- The Final Decree: This document often specifies which assets were contested and how they were divided.
- Appraisal Reports: If you paid for a business valuation or home appraisal, keep these to justify your cost basis.
Conclusion
At Smart Money & Tech Tips for Americans, we know that navigating the financial maze of a divorce is exhausting. While divorce legal fees tax deductible status is essentially a thing of the past for federal returns, being informed prevents you from making errors that could trigger an IRS audit.
Focus on the strategies that do work: itemizing your bills for future basis adjustments, understanding the “origin of the claim” test to avoid business-filing mistakes, and consulting with a tax professional who understands the post-2025 legislative landscape.
If you are looking for the right representation to help you through this process, we recommend checking out these Detailed Reviews of the Top 10 Family Law Attorneys to find a partner who can help you protect your assets efficiently. Stay smart, keep your records organized, and remember that while the tax code might not be on your side during a divorce, proactive planning always pays off.