How to Compare Car Insurance Quotes and Save Money in 2026
When you compare car insurance quotes side by side, you can find the same coverage for dramatically less money — sometimes hundreds of dollars less per year.
Here’s how to do it quickly:
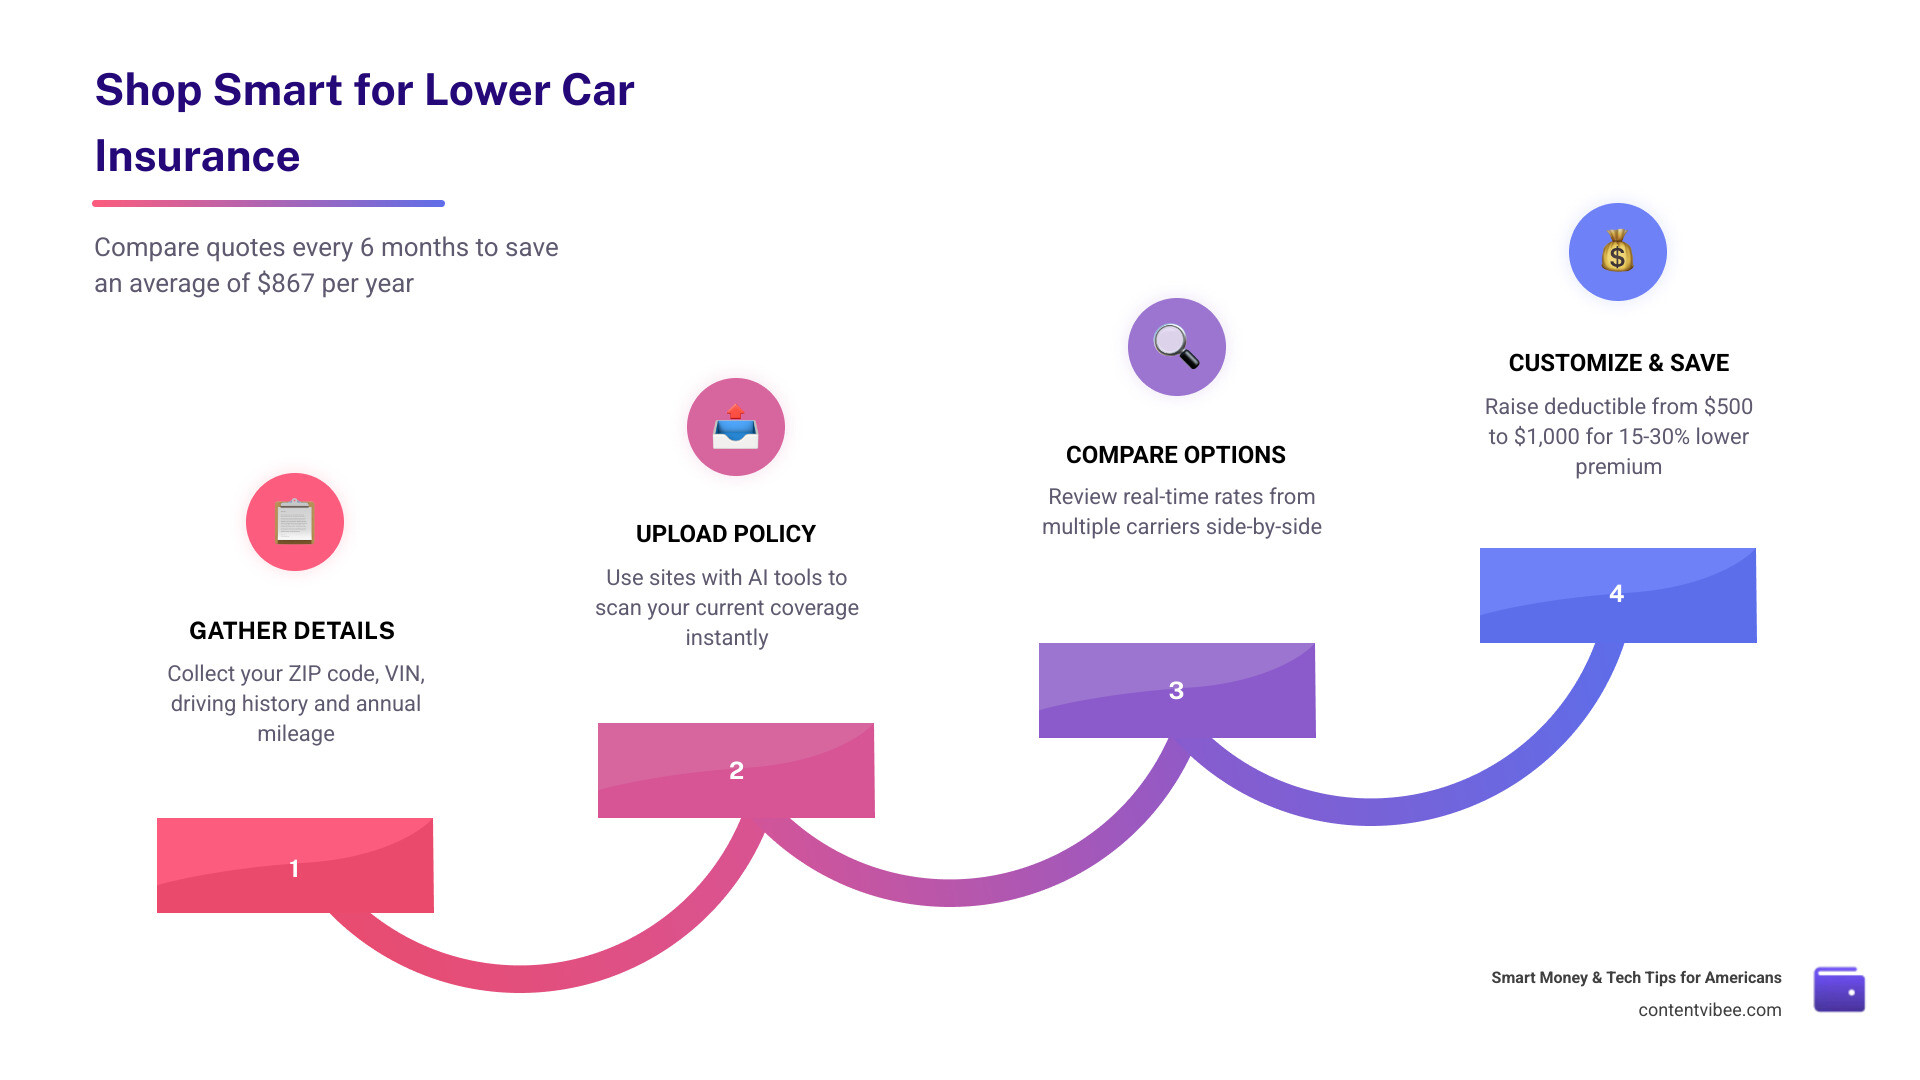
- Gather your info — ZIP code, vehicle VIN, driving history, and current coverage limits
- Use a comparison tool — enter your details once to see quotes from multiple insurers at the same time
- Match coverage apples to apples — make sure each quote uses the same deductibles and limits before comparing prices
- Pick the best value — consider price, customer service ratings, and financial strength, not just the lowest number
The average American driver pays $182 per month for full coverage. Drivers who shop around can save up to $867 per year — just by comparing rates.
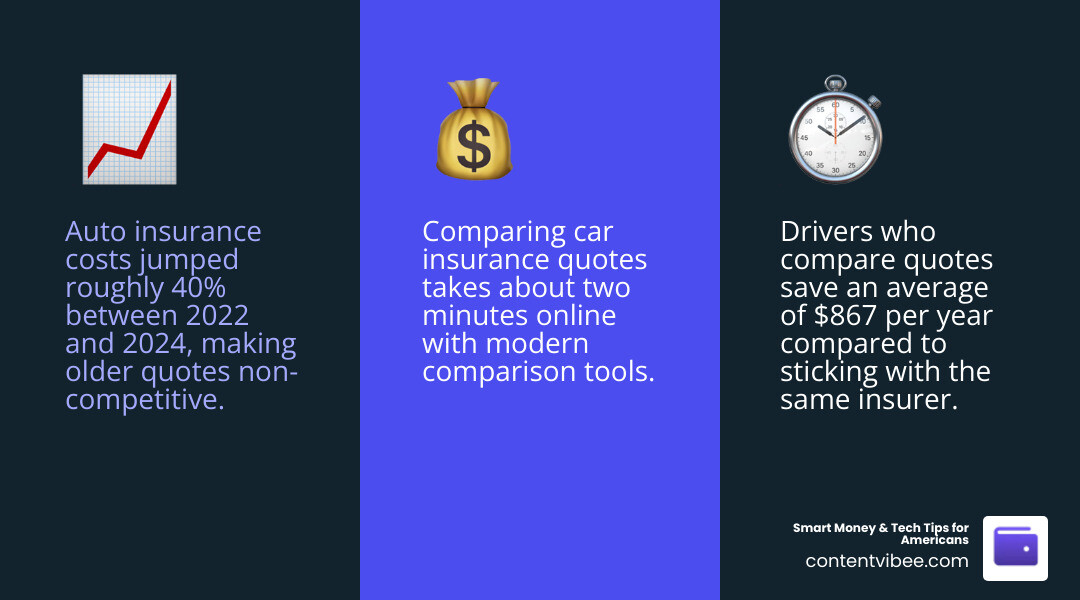
Auto insurance costs jumped roughly 40% between 2022 and 2024. That means the rate you locked in two or three years ago is likely no longer competitive. Insurers price risk differently, so the cheapest company for your neighbor may be the most expensive one for you.
The good news? Comparing quotes takes about two minutes online — and the savings can be significant.
Why You Should Regularly Compare Car Insurance Quotes
If you’re like us, you probably have a “set it and forget it” mentality with most of your bills. But while that works for your favorite streaming service, it’s a dangerous game to play with auto insurance. The market in May 2026 is volatile, and sticking with the same carrier for a decade might actually be costing you a small fortune.
Between 2022 and 2024, the average American driver saw their auto insurance bill skyrocket by about 40%. This wasn’t just a minor bump; it was a market-wide shift. If you haven’t looked at other options lately, you are likely paying “loyalty tax.” Research from NerdWallet suggests that drivers could be overpaying by an average of $4,914 per year simply by not shopping around. That is enough for a very nice vacation—or a lot of fancy toast.
Regularly checking the market ensures you aren’t leaving money on the table. Much like The Ins and Outs of Health Insurance Cost Per Month, auto insurance rates are highly personalized. What was the “cheapest” option for you two years ago might now be the most expensive because the insurance company changed how they calculate risk for your specific ZIP code or vehicle type.
By taking the time to Compare Car Insurance Rates Online | Progressive, you can see how your current carrier stacks up against the competition.
How to compare car insurance quotes for maximum savings
To get the most out of your search, we recommend using a multi-pronged approach. The goal is to get a wide variety of personalized quotes. Every insurance company has its own “secret sauce” for pricing. One might love drivers with electric vehicles, while another might offer massive discounts for students with good grades.
Using modern comparison tools is the most efficient way to see these variations in real-time. These tools allow you to enter your data once and receive quotes from dozens of carriers. This is very similar to how we suggest you approach other financial decisions, as seen in our A Comprehensive Guide to Health Insurance Plans Comparison. When you see the data side-by-side, the “best” choice usually jumps off the screen.
Information needed to compare car insurance quotes accurately
To get a quote that is actually accurate (and not just a “teaser” rate), you need to have your ducks in a row. If you provide vague info, you’ll get a vague price. Before you sit down to compare car insurance quotes, gather the following:
- ZIP Code: Where you park your car at night is a huge factor.
- Vehicle Identification Number (VIN): This tells the insurer exactly what safety features and tech your car has.
- Driving History: Be honest about that speeding ticket from three years ago; they will find it anyway!
- Annual Mileage: Do you drive 5,000 miles a year or 25,000? It makes a difference.
- Current Policy Declarations: This is the “cheat sheet” that shows your current coverage limits and deductibles.
- Personal Details: Dates of birth and driver’s license numbers for everyone in your household.
Key Factors That Determine Your Monthly Premiums
Ever wonder why your brother pays half as much as you do for insurance despite driving a faster car? It’s because insurers look at a massive range of data points to predict how likely you are to file a claim. Here are the big ones:
- Driving Record: This is the most obvious. A clean record with no accidents or DUIs will always net you the lowest rates. An at-fault accident can raise your rates by an average of 49%.
- Credit History: In most states (excluding places like California, Hawaii, and Massachusetts), your credit score significantly impacts your rate. Drivers with poor credit can pay nearly twice as much as those with excellent credit.
- Age and Gender: Teenagers pay the most (averaging $260/month) because they lack experience. On the flip side, drivers in their 60s often see the lowest rates, averaging around $122/month.
- Location: Living in a busy urban area with high theft rates will cost more than living in a quiet rural town.
- Vehicle Type: If your car is expensive to repair or frequently stolen, your premium will reflect that. Modern safety sensors can actually make some cars more expensive to fix after a minor fender bender!
To give you an idea of the cost difference between basic and robust protection, check out the average monthly costs below:
| Coverage Type | Average Monthly Cost | What it Covers |
|---|---|---|
| Liability-Only | $98 | Damage/injuries you cause to others |
| Full Coverage | $182 | Liability + damage to your own vehicle |
Step-by-Step Guide to Compare Car Insurance Quotes Online
Ready to save? Follow our step-by-step guide to navigate the digital insurance marketplace like a pro.
Step 1: Choose Your Comparison Method You have three main options:
- Comparison Sites: Tools like The Zebra: Instantly Compare Insurance Quotes are great because they allow you to fill out one form and see quotes from over 100 insurers.
- Direct Carriers: You can go straight to the websites of big names like State Farm or Progressive. This takes longer but can sometimes yield specific “direct-to-consumer” discounts.
- Independent Agents: These are real humans who shop multiple companies for you. They are great if you have a complicated situation, like a DUI or multiple classic cars.
Step 2: Use Policy Upload Features Many modern sites now allow you to upload a photo of your current policy “Dec Page.” Their AI reads your current coverage and automatically finds cheaper versions of that exact same plan. This ensures you are getting a true comparison.
Step 3: Watch Out for “Lead-Gen” Spam Not all comparison sites are created equal. Some sites just want to sell your phone number to 50 different agents who will call you during dinner. Look for “spam-free” or “real-time” quote tools that provide the price on the screen rather than a “we’ll call you” message.
Step 4: Customize Your Coverage Don’t just take the default. Adjust your deductibles. Raising your deductible from $500 to $1,000 can often drop your premium by 15-30%. Just make sure you have that $1,000 in a savings account just in case!
For those looking at their family’s total protection, it’s worth checking Health Insurance Options for Every American Family to see how you can balance your total insurance budget.
Frequently Asked Questions about Car Insurance Comparison
How much can I save by switching insurers?
On average, drivers who compare car insurance quotes and switch save about $867 per year. Some shoppers have even reported cutting their bills by 50%. This happens because insurance companies frequently update their “underwriting models.” A company that was expensive for you last year might be aggressively trying to grow its customer base this year by offering lower rates.
Does comparing quotes affect my credit score?
No! This is a common myth. When an insurance company checks your credit, it is a “soft pull,” similar to when you check your own score on an app. It does not impact your credit score or show up to lenders. You can shop as much as you want without worrying about your financial standing.
How often should I shop for new coverage?
We recommend shopping every six to twelve months, or specifically when your policy is up for renewal. You should also compare rates after major life events, such as:
- Moving to a new ZIP code.
- Buying a new vehicle.
- Adding a teen driver to the policy.
- Getting married (married drivers pay significantly less than single drivers!).
- Improving your credit score significantly.
Conclusion
At Smart Money & Tech Tips for Americans, we believe that financial empowerment starts with having the right information. You don’t have to be a victim of rising insurance costs. By taking just a few minutes to compare car insurance quotes, you can reclaim hundreds of dollars of your hard-earned money.
Whether you are looking to trim your monthly budget or ensure your family has the best possible protection, staying informed is key. And while you’re optimizing your monthly expenses, don’t forget to look at the big picture—check out how you can Maximize your financial strategy with our Social Security Spousal Benefit Calculator to ensure your long-term retirement goals are on track too!