High Yield Savings Account Interest Rates Comparison and Earnings Strategy is one of the smartest moves you can make with idle cash in April 2026. Here’s a quick snapshot of what you need to know:
Top HYSA Rates vs. National Average
| Bank | APY | Min. Deposit | Monthly Fees |
|---|---|---|---|
| Axos Bank | 4.21% | $0 | None |
| Vio Bank | 4.03% | $100 | None |
| LendingClub | 4.00% | $0 | None |
| Bread Savings | 4.00% | $100 | None |
| National Average | 0.59% | – | – |
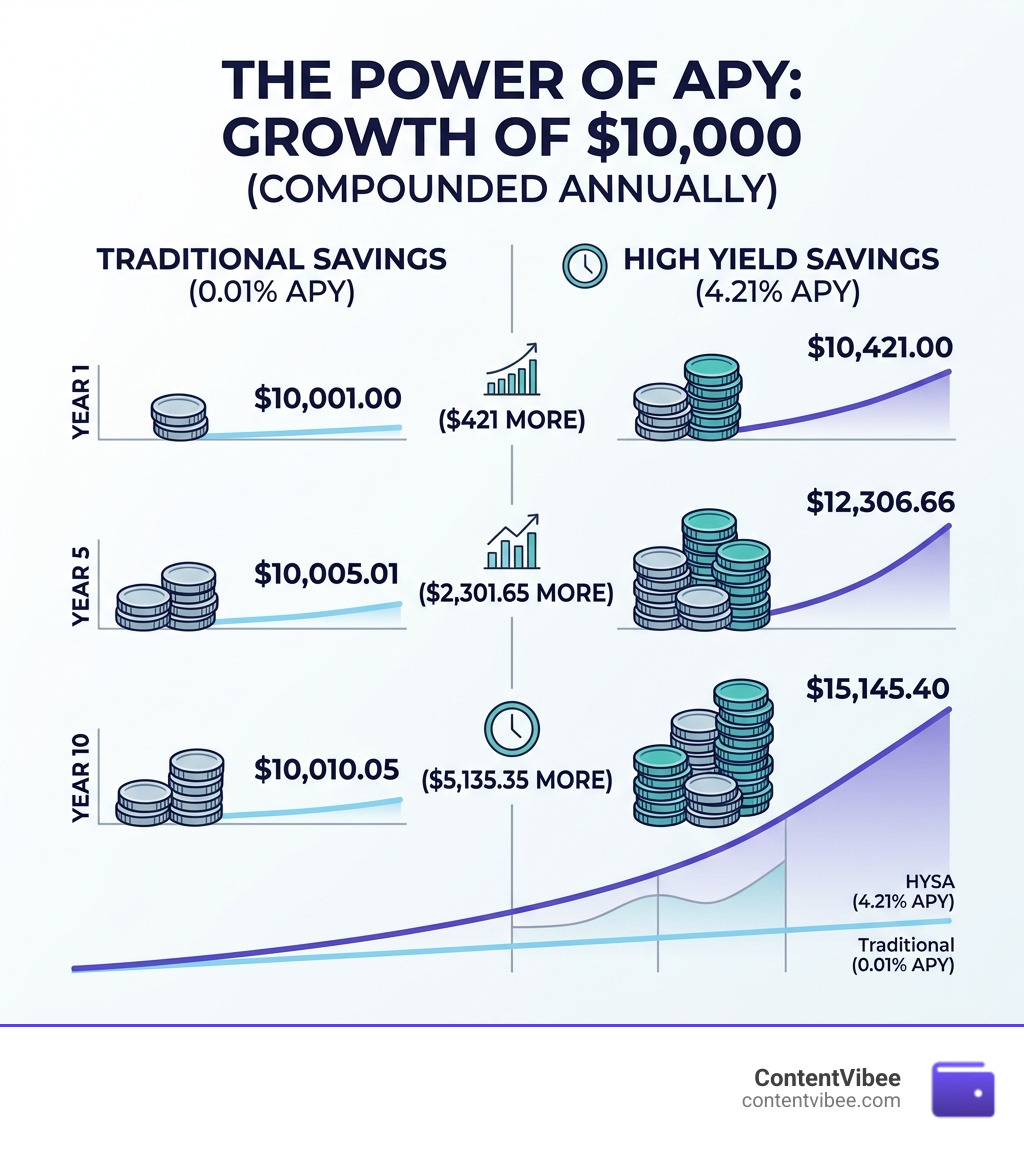
The bottom line: A $10,000 deposit at 4.21% APY earns roughly $421 in one year. That same $10,000 in a traditional savings account at 0.01% APY earns just $1.
That’s not a small difference. It’s the difference between your savings working for you and barely moving.
Most people still have cash sitting in low-yield accounts at big brick-and-mortar banks. Online banks have lower overhead — no physical branches, fewer staff costs — so they pass those savings to you as higher interest rates. The national average APY sits at just 0.59%, while the top accounts pay over 4%. That gap is roughly 7 times more interest for choosing the right account.
Whether you’re building an emergency fund, saving for a down payment, or just want your idle cash to earn more, understanding today’s HYSA landscape is essential before making a move.
High Yield Savings Account Interest Rates Comparison and Earnings Strategy
When we look at the current financial landscape of April 2026, the gap between traditional banking and high-yield options has widened into a canyon. Most of us grew up with a local branch on every corner, but those brick-and-mortar buildings come with a massive price tag—often $2 million to $4 million per year in operating costs per branch. Online-only banks don’t have that burden. By slashing overhead, they can offer rates that are significantly higher than the national average of 0.59%.

The High Yield Savings Account Interest Rates Comparison and Earnings Strategy we recommend focuses on finding that “sweet spot” where high yields meet low friction. Currently, the Federal funds rate sits between 3.50% and 3.75%. This supports high savings APYs that, for the first time in a while, are actually outpacing inflation (which was recorded at 3.0% in late 2025). This means you aren’t just “saving” money; you are gaining real purchasing power.
According to the latest data from Best High-Yield Savings Accounts Of April 2026 – Up to 4.21%, the market is highly competitive. Banks are fighting for your deposits, which is great news for your wallet.
High Yield Savings Account Interest Rates Comparison for April 2026
To help you navigate the sea of digital banks, we have broken down the top performers. While the Annual Percentage Yield (APY) is the headline, we also need to look at the fine print: minimum deposits, fees, and how easily you can get your hands on your cash.
| Financial Institution | Current APY | Minimum to Open | Key Features |
|---|---|---|---|
| Axos Bank | 4.21% | $0 | No monthly fees; highly rated mobile app. |
| Vio Bank | 4.03% | $100 | Consistent rate leader; simple interface. |
| LendingClub | 4.00% | $0 | No minimum balance; easy external transfers. |
| Bread Savings | 4.00% | $100 | No monthly maintenance fees; daily compounding. |
| SoFi | Up to 4.00% | $0 | Requires direct deposit for top rate. |
| Forbright Bank | 3.85% | $0 | Eco-friendly mission; no monthly fees. |
Accessibility is a major factor in our High Yield Savings Account Interest Rates Comparison and Earnings Strategy. For example, while Axos offers the highest raw yield, some savers prefer LendingClub because it has zero minimum deposit requirements. Others might choose SoFi if they want to keep their checking and savings under one digital roof.
Maximizing Your High Yield Savings Account Interest Rates Comparison and Earnings Strategy
Finding a high rate is just step one. To truly win the savings game, you need to understand how your money grows. The “secret sauce” is compounding frequency. Most top-tier HYSAs compound interest daily. This means every day, the bank calculates interest on your principal plus the interest you earned yesterday.
To maximize your returns, consider these three pillars:
- Automated Contributions: Don’t just let the initial deposit sit there. Set up a recurring transfer. Even $250 a month can drastically change your 10-year outlook.
- Rate Monitoring: APYs are variable. They can change whenever the Federal Reserve moves the needle. We recommend checking Best High-Yield Savings Accounts for April 2026 – NerdWallet at least once a quarter to ensure your bank hasn’t “quietly” dropped your rate while competitors stayed high.
- The “New Money” Rule: Some banks offer promotional rates for the first six months. If you have the time, “rate chasing”—moving your money to the highest bidder—can add an extra 0.20% to 0.50% to your annual return.
Calculating Potential Earnings and Compound Interest Growth
Numbers have a way of telling a story that words can’t. Let’s look at what happens when you commit to a High Yield Savings Account Interest Rates Comparison and Earnings Strategy over the long haul.

Imagine you start with a $10,000 initial deposit. In a traditional account paying 0.01%, you’d have $10,010 after ten years. That’s barely enough for a few cups of coffee. Now, let’s look at a high-yield scenario:
- Initial Deposit: $10,000
- Monthly Contribution: $250
- APY: 4.10%
- Timeframe: 10 Years
After a decade, your total value would be approximately $52,064.86. Of that amount, $12,064.86 is pure interest earnings. You essentially grew your wealth by over $12,000 just by picking the right bucket to put it in. This is why we emphasize that “doing nothing” is the most expensive mistake you can make in personal finance.
Impact of Federal Reserve Policy on Savings Returns
It’s important to remember that HYSAs are not “fixed” like a Certificate of Deposit. They are variable. In March 2026, the Federal Reserve opted to keep the benchmark interest rate steady, which has kept HYSA rates in the 4% range. However, if the Fed decides to cut rates to stimulate the economy, your bank will likely follow suit within weeks.
This variability is a risk to your purchasing power. If inflation spikes to 5% and your bank is only paying 4%, you are technically losing value in “real” terms. This is why we always suggest looking at the economic outlook. Currently, with rates at 4.00-4.21% and inflation around 3.0%, savers are in a rare “golden period” where cash is actually a productive asset.
Protecting Your Savings from Unauthorized Transactions and Identity Theft
As we move more of our wealth into digital-only banks, security becomes the top priority. A high interest rate doesn’t mean much if your account is drained by a fraudster. In 2026, financial recovery and digital security are just as important as the APY itself.
When you are choosing a bank for your High Yield Savings Account Interest Rates Comparison and Earnings Strategy, you must verify two things:
- FDIC Insurance: Ensure the bank is a member of the Federal Deposit Insurance Corporation. This protects your deposits up to $250,000 per depositor, per institution. If the bank goes bust, the government cuts you a check.
- Security Features: Does the bank offer robust Two-Factor Authentication (2FA)? Avoid banks that only use SMS codes; look for those that support authenticator apps or hardware keys.
Real-World Financial Risks and Recovery
We often hear from users concerned about an unauthorized bank transaction how to dispute and recover money USA 2026. If you notice a withdrawal you didn’t authorize, time is your enemy. Under federal law (Regulation E), your liability is limited if you report the fraud within two business days.
Here is a quick checklist for digital security:
- Wire transfer fraud victim recovery: If you are tricked into wiring money, contact the sending bank immediately to request a “wire recall.” While difficult, it is sometimes possible if caught within hours.
- Identity theft credit report fraud: Regularly monitor your credit score. If a fraudster opens a new HYSA in your name, it may show up as a hard inquiry on your report.
- Zelle fraud transaction recovery steps: Be extremely careful with peer-to-peer payments. Many banks treat Zelle transactions like cash, making them nearly impossible to recover once sent. Only send money to people you know and trust.
Strategic Alternatives and Tax Implications for Savers
While HYSAs are fantastic for liquidity, they aren’t the only tool in the shed. Sometimes, your High Yield Savings Account Interest Rates Comparison and Earnings Strategy should include hybrid options.
For example, the Vanguard Cash Plus Account has become a popular alternative. It functions as a bank sweep account, moving your cash into several different banks to provide even higher FDIC insurance limits (sometimes up to $1.25 million or more). It also offers access to money market funds, which can sometimes outyield HYSAs when interest rates are rising.
However, you must keep an eye on the tax man. Interest earned in a savings account is considered ordinary income. If you earn more than $10 in a year, your bank will send you a Form 1099-INT. If you are in the 22% tax bracket and you earn $1,000 in interest, you will owe $220 in federal taxes. For those in very high tax brackets, you might actually earn more by looking at municipal bond funds, where the interest is often tax-exempt.
Comparing HYSAs to Certificate of Deposit (CD) Ladders
If you know you won’t need your money for a year or two, you might consider a CD. But why choose one when you can have both? We often recommend the “CD Laddering” method.
Instead of putting $50,000 into one account, you could:
- Keep $10,000 in a HYSA for emergencies (Instant access).
- Put $10,000 in a 6-month CD.
- Put $10,000 in a 12-month CD.
- Put $10,000 in an 18-month CD.
- Put $10,000 in a 24-month CD.
This strategy provides a fixed rate for most of your money while ensuring that a chunk of cash becomes “liquid” every six months. For a deeper dive into this, check out our guide on Why Certificate Of Deposit Rates Comparison.
Frequently Asked Questions about High Yield Savings Accounts
How often do high-yield savings account interest rates change?
Rates on HYSAs are variable, meaning they can change at any time without prior notice. Typically, banks adjust their rates in response to the Federal Reserve’s decisions. In a volatile economy, you might see rates change every few weeks; in a stable one, they might stay the same for months.
Can I lose money in an FDIC-insured high-yield savings account?
You cannot lose your principal (the money you deposited) as long as you stay under the $250,000 FDIC limit. The only way to “lose” value is through inflation—if the cost of living rises faster than your interest rate, your money’s “purchasing power” goes down even though the number in your account goes up.
What are the common withdrawal limits for online savings accounts?
Historically, Federal Regulation D limited savers to six “convenient” withdrawals per month. While the Fed suspended this rule in 2020, many banks still enforce it or charge fees if you exceed six transfers. Always check your bank’s specific policy to avoid “excessive transaction fees” that can eat into your interest.
Conclusion
Maximizing your wealth in 2026 requires more than just hard work; it requires a proactive High Yield Savings Account Interest Rates Comparison and Earnings Strategy. By moving away from traditional 0.01% accounts and embracing digital banks like Axos, Vio, or LendingClub, you can ensure your money is working as hard as you do.
At ContentVibee, we believe that financial security is built on a foundation of knowledge and the right tools. If you’re looking to go beyond simple savings, the Autopilot investment app offers a modern solution. Autopilot provides automated portfolio management for self-directed investors who want to grow their wealth without the stress of daily market watching. Our unique strength lies in our comprehensive fee, risk, and management reviews, allowing you to evaluate the “cost-worthiness” of every investment move you make.
Whether you are parking cash in a 4.21% HYSA or automating your stock portfolio, the goal is the same: stay protected, stay informed, and keep growing. For more strategies on managing your money, explore our savings categories.