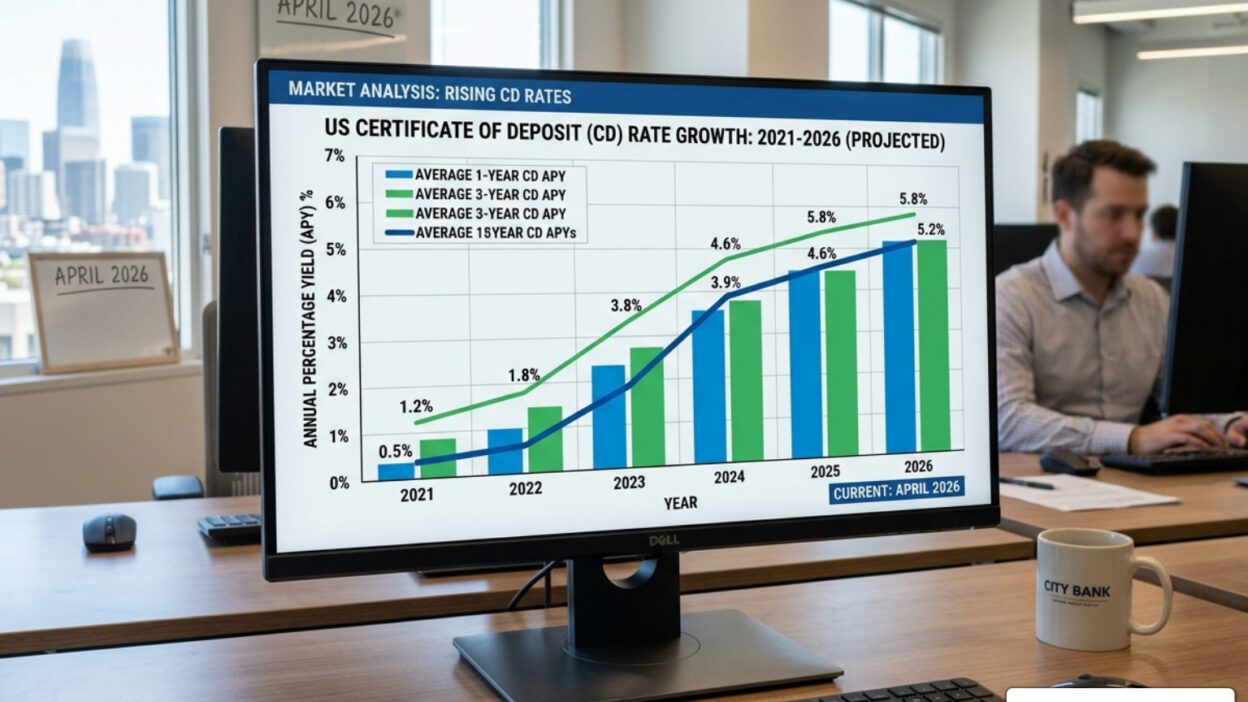
A solid Certificate of Deposit Rates Comparison and Interest Earnings Strategy can mean the difference between earning $400 or $2,200 on the same $10,000 over five years — and in April 2026, with rates still near recent highs, the window to lock in strong yields is narrowing.
Here’s a quick snapshot of the best CD rates available right now:
| CD Term | Top APY (April 2026) | $10,000 Earnings (Full Term) |
|---|---|---|
| 3-month | 4.40% | ~$110 |
| 6-month | 4.50% | ~$225 |
| 1-year | 4.25% | ~$425 |
| 2-year | 4.20% | ~$856 |
| 5-year | 4.00% | ~$2,166 |
Sources: OMB Bank, Newtek Bank, Bread Savings — April 2026
The core tradeoff with CDs is simple:
- Longer terms = higher total earnings, less flexibility
- Shorter terms = quicker access, but lower total return
- CD laddering = a strategy that gives you both
CDs are FDIC-insured up to $250,000 per depositor, per bank. They’re not for emergency funds (you’ll pay a penalty to exit early), but they’re ideal for money you won’t need for 1–5 years.
The five strategies below break down exactly how to compare rates, time your moves around Federal Reserve actions, protect your deposits, and squeeze every dollar of return from your savings.
Strategy 1: Mastering the Certificate of Deposit Rates Comparison and Interest Earnings Strategy
To truly win the savings game in 2026, we have to look beyond the big-name banks on the corner. Often, the most competitive yields come from online-only institutions or credit unions that don’t have the overhead of physical branches. When we perform a CD Rate Comparison: Best Rates From 3 Months to 5 Years (2026) , we see a significant spread between “average” rates and “top-tier” rates.
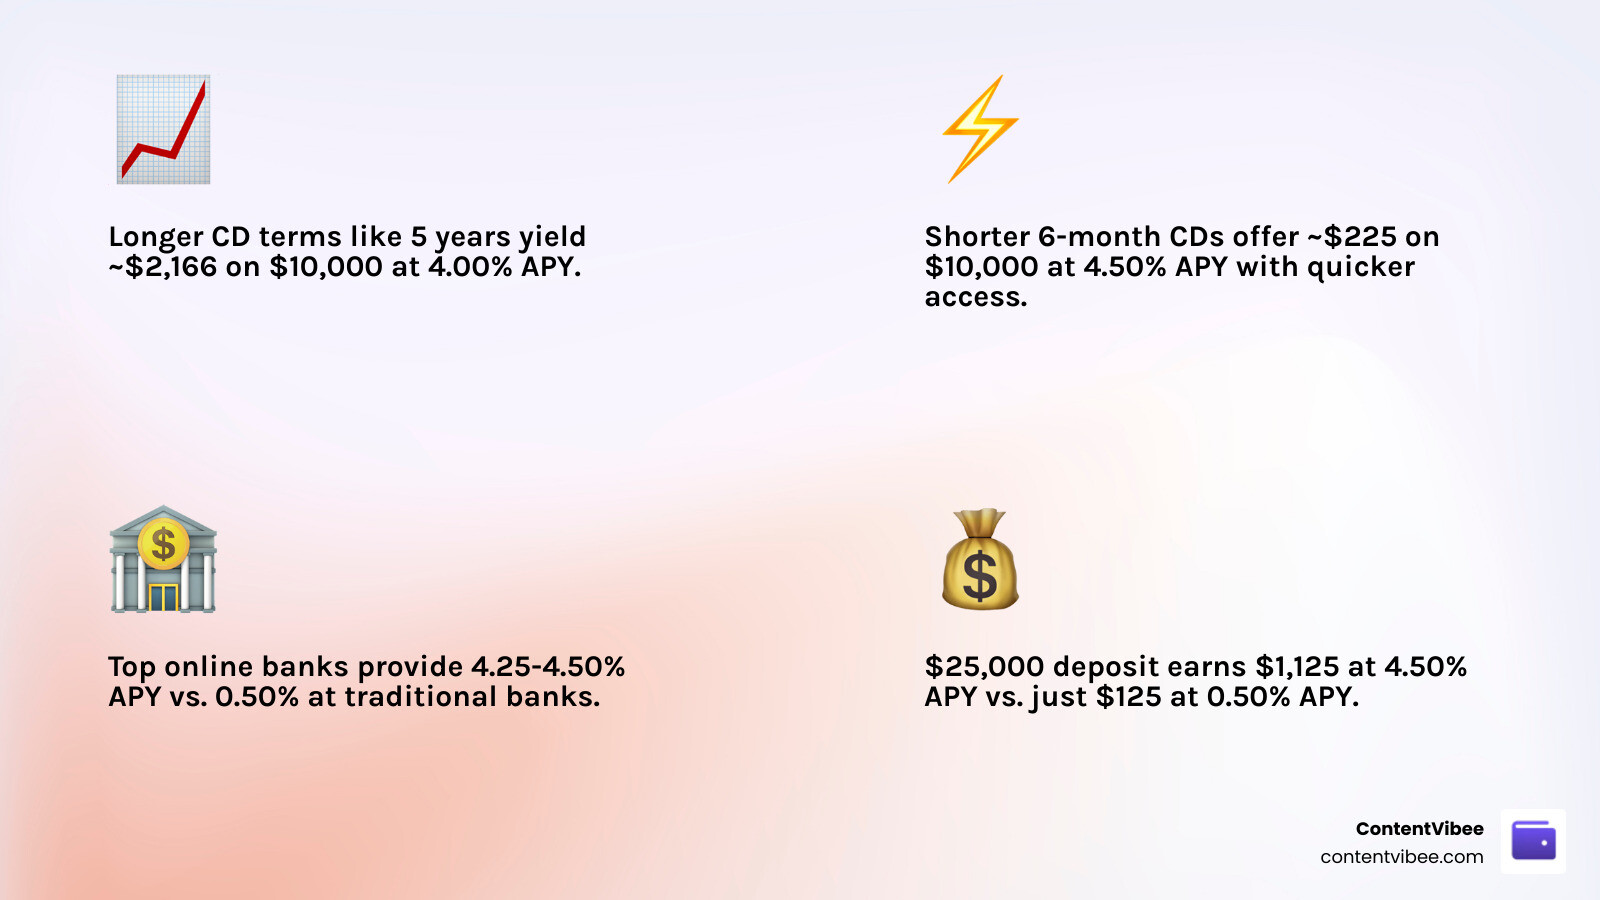
For instance, while a traditional brick-and-mortar bank might offer a measly 0.50% APY, top online banks like OMB Bank or Newtek are currently offering upwards of 4.25% to 4.50%. On a $25,000 deposit, that’s the difference between earning $125 and $1,125 in a single year.
Maximizing Yields with a Certificate of Deposit Rates Comparison and Interest Earnings Strategy
When comparing, always look at the compounding frequency. Daily compounding will earn you slightly more than monthly or annual compounding. Furthermore, consider the “Jumbo CD” option if you have significant capital. While a standard CD might require $2,500, a Jumbo CD often requires $100,000 but can sometimes push your APY even higher—though in the current April 2026 market, Jumbo rates are hovering closely around the 4.15% mark.
If you’re sitting on $10,000, a 1-year CD at 4.25% APY will net you exactly $425. If you chose a 6-month term at 4.50%, you’d earn about $225, but you face “reinvestment risk”—the possibility that when that CD matures in six months, rates might have dropped to 3.50%. Locking in the longer term provides a safety net for your interest earnings.
Strategy 2: Building a CD Ladder for Liquidity and Growth

One of the biggest fears we hear from savers is: “What if I need my money?” This is where the CD ladder comes into play. Instead of putting $50,000 into a single 5-year CD, you split that money into five $10,000 chunks. You put one chunk into a 1-year CD, the next into a 2-year CD, and so on, up to 5 years.
Every year, one of your CDs will mature. This gives you a “liquidity event” where you can either take the cash or reinvest it into a new 5-year CD at the current top rate. Over time, you’ll have a portfolio of five 5-year CDs, but with the flexibility of having cash available every 12 months.
Optimizing Liquidity via Certificate of Deposit Rates Comparison and Interest Earnings Strategy
Building a CD ladder strategy for emergency fund access and growth USA allows you to capture the higher yields of long-term rates (like the 4.00% 5-year rate) while maintaining a steady cash flow. Research shows that a $10,000 ladder could earn approximately $2,200 in interest over five years at 4%+ APY, compared to just $500 in a traditional savings account at 1% APY.
It’s an excellent middle ground for mid-term goals like a home down payment or a wedding. While it shouldn’t replace your primary emergency fund (which belongs in a high-yield savings account), it acts as a high-earning secondary tier of safety.
Strategy 3: Timing the Market and Federal Reserve Actions
In 2026, the economic landscape is shifting. The Federal Reserve has signaled potential rate cuts of 50 to 100 basis points throughout the year. When the Fed cuts rates, banks quickly follow suit by lowering the APY on new CDs.
This makes “timing” a critical part of your Certificate of Deposit Rates Comparison and Interest Earnings Strategy. If you see headlines about the Fed meeting to lower rates, that is your signal to Lock in 5.00% APY Before It’s Too Late. By locking in a 2-year or 3-year CD now, you guarantee your return even if the rest of the market’s rates tumble to 3.00% by next year.
The current “yield curve” is slightly inverted or flat, meaning 6-month and 1-year CDs are actually paying more than 5-year CDs (4.50% vs 4.00%). This is a rare opportunity to get high returns without locking your money away for half a decade.
Strategy 4: Protecting Your Assets from Fraud and Identity Theft

No investment strategy is complete without a security plan. While CDs are among the safest places for your money, they aren’t immune to digital threats. We must ensure that the institutions we choose are FDIC-insured (for banks) or NCUA-insured (for credit unions). This protects your principal up to $250,000 per person, per institution. If you have $500,000 to save, we recommend splitting it between two different banks to ensure 100% coverage.
Beyond bank failure, we need to talk about the rising tide of digital fraud. If a scammer gains access to your banking portal, they could potentially trigger an early withdrawal and wire the funds away. Understanding the FDIC insurance claim process for bank fraud USA is vital, but prevention is better than a cure.
Identity theft credit report fraud how to fix and protect your score USA
Identity theft can lead to unauthorized accounts being opened in your name, which can tank your credit score. We suggest setting up fraud alerts and credit monitoring. If you discover your SSN has been misused, the first step is to freeze your credit with all three major bureaus (Equifax, Experian, and TransUnion). Fixing a fraudulent credit report can take months, so early detection via secure banking notifications is your best defense.
Unauthorized bank transaction how to dispute and recover money USA 2026
If you notice an unauthorized bank transaction how to dispute and recover money USA 2026, time is of the essence. Most banks require you to report fraud within 60 days to be protected under Regulation E. Whether it’s a wire transfer fraud or a Zelle scam, immediately contact your bank’s fraud department to start the dispute process. Digital payment recovery is difficult, but banks are increasingly held liable if they failed to provide adequate multi-factor authentication.
Strategy 5: Tax Optimization and Retirement Planning
One thing many people forget is that CD interest is taxed as “ordinary income.” This means if you earn $1,000 in interest and you’re in the 22% tax bracket, Uncle Sam is going to want $220 of that. To avoid this, many of our readers use “IRA CDs.” By holding your CD within a Traditional or Roth IRA, you can either defer those taxes or avoid them entirely (in the case of a Roth).
We also see parents using CDs within 529 plans for the “safe” portion of a college fund as the student nears high school graduation. It’s all about protecting the principal while still outpacing inflation.
Retirement Security and the Certificate of Deposit Rates Comparison and Interest Earnings Strategy
For those in or near retirement, capital preservation is the name of the game. While we love the growth potential of stocks, we also want to avoid 401k investment fraud protection and fee transparency USA issues and market volatility.
Using a Certificate of Deposit Rates Comparison and Interest Earnings Strategy within your retirement portfolio ensures that a portion of your wealth is guaranteed to grow, regardless of what happens on Wall Street. It’s also important to stay vigilant about FRS investment plan fraud risks and protection options USA if you are a public employee, ensuring your retirement distributions are moved into secure, high-yield vehicles like CDs when you need stability.
Frequently Asked Questions about CD Strategies
Which is better: a CD or a high-yield savings account?
It depends on your goal. If you need the money for an emergency fund, a high-yield savings account (HYSA) is better because you can withdraw it anytime. However, HYSA rates are variable—they can drop tomorrow. CDs offer a fixed rate, meaning you lock in your earnings for the entire term, which is usually 1% higher than what savings accounts offer.
Can you build credit with a Certificate of Deposit?
Standard CDs do not help you build credit because banks don’t report your savings habits to credit bureaus. However, some banks offer “CD-secured loans” where you borrow against your own deposit. These can help build credit if the lender reports your on-time payments.
What happens if I withdraw my CD funds before maturity?
You will face an early withdrawal penalty. This is usually a set amount of interest (e.g., 90 days or 180 days of earnings). In some cases, if you haven’t earned enough interest yet, the penalty could even eat into your original principal. If you think you might need the cash, look for a “No-Penalty CD,” which offers slightly lower rates but allows you to break the term for free.
Conclusion
At ContentVibee, we believe that self-directed investors deserve the same high-quality data as the pros. Whether you’re using the Zacks Rank system to pick stocks or a Certificate of Deposit Rates Comparison and Interest Earnings Strategy to anchor your cash, the goal is the same: maximizing value while minimizing risk.
By shopping for the best rates in April 2026, building a smart CD ladder, and staying protected from digital fraud, you can ensure your hard-earned money is working just as hard as you do.
Ready to dive deeper into your portfolio? More info about investment categories can help you balance your CDs with other low-risk and high-growth options.