

What “Very Cheap Car Insurance No Deposit” Actually Means (And How to Get It)
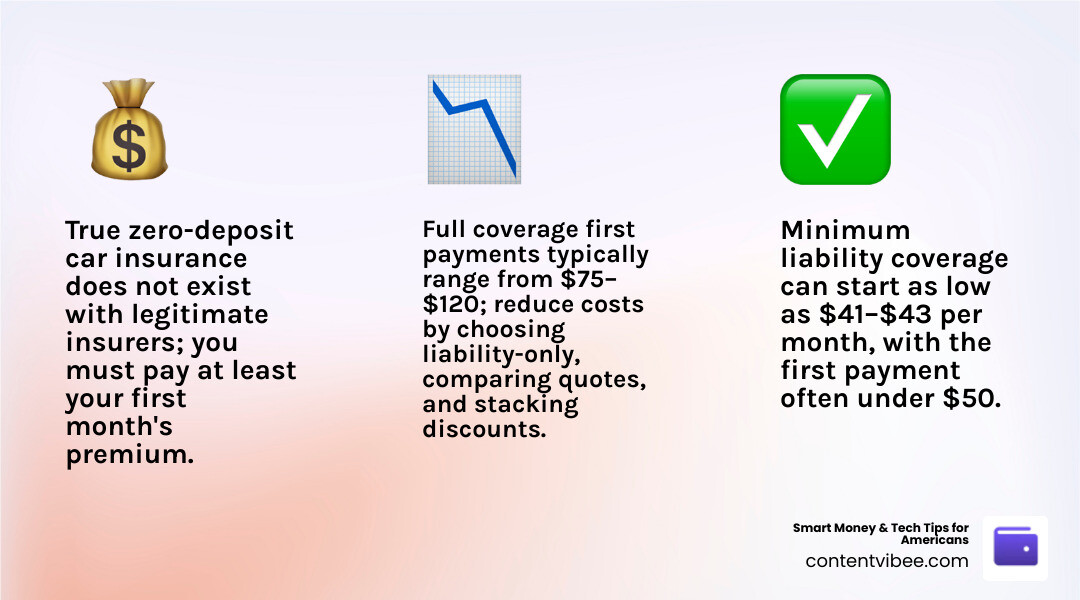
If you’re searching for very cheap car insurance no deposit, here’s the quick answer: true zero-deposit car insurance doesn’t exist with legitimate insurers. You will always need to pay at least your first month’s premium before coverage starts. However, that first payment can be surprisingly low — and there are real strategies to shrink it further.
Quick answers at a glance:
- What “no deposit” really means: No separate security deposit, no multi-month prepayment — but you still owe your first installment before coverage activates.
- Cheapest starting point: Minimum liability coverage can start as low as $41–$43/month, meaning your first payment could be under $50.
- Lowest upfront for full coverage: Expect roughly $75–$120 as a first payment for basic full coverage.
- Best ways to reduce that first payment: Choose liability-only coverage, compare multiple quotes, stack discounts, and consider monthly billing.
- Watch out for: Ads promising “$0 due today” from unverified sources — these are often misleading or outright scams.
For budget-conscious drivers — including retirees managing fixed incomes — the gap between what insurers advertise and what they actually require upfront can cause real frustration. The good news is that with the right approach, your first payment can be kept very low.
This guide breaks down exactly how it works, what to expect, and how to pay as little as possible to get covered today.
Understanding Very Cheap Car Insurance No Deposit Options
When we talk about very cheap car insurance no deposit, we are really discussing the “amount due today.” In the insurance world, a “deposit” is often a separate fee or a requirement to pay several months in advance. Legitimate insurers have moved away from these hefty entry fees, but they still require a “binder” or the first month’s premium to activate your policy.
Think of it like a subscription service. You wouldn’t expect a streaming service to let you watch movies for a month before you pay your first bill. Car insurance works similarly. To “bind” the coverage — meaning the insurer is legally responsible for your risks — they must collect a payment.
If you are looking for No Deposit, $0 Down: Instant Affordable Car Insurance | OCHO, you are essentially looking for a plan that spreads the total annual cost into the smallest possible starting chunk. By paying only the first month upfront, you avoid the traditional 20% to 33% down payment that many legacy companies used to demand.
Finding Very Cheap Car Insurance No Deposit Plans in 2026
As of May 2026, the market has shifted toward high-tech, flexible payment solutions. Fintech companies and digital-first insurers are leading the charge by offering bi-weekly installments that align with your paycheck. This is a game-changer for those who find a full monthly payment difficult to manage all at once.
According to research on Very Cheap Car Insurance with No Down Payment or Deposit 2026, drivers with good credit and a clean record can find policies starting around $53 per month for minimum coverage. If you’re looking for the absolute rock-bottom price, GEICO often leads the pack with minimum coverage quotes averaging around $43 per month.
The Reality of Zero Down Marketing
We’ve all seen the flashy ads: “$0 Down Car Insurance!” or “No Money Needed to Start!” In most cases, these are Very cheap car insurance with no down payment | Dairyland auto® marketing terms that mean you aren’t paying a separate security deposit. You are still paying for the insurance itself.
Some companies might also charge a small administrative or “broker fee” to set up your account. While this fee might be separate from your premium, it’s part of that initial out-of-pocket cost. Always ask for a full breakdown of the “total amount due today” before you provide your credit card information.
Why Insurers Require Upfront Payments
It might feel like a hurdle when you’re short on cash, but insurers require upfront payments for several logical reasons. Primarily, it’s about risk mitigation. The moment you sign that digital contract, the insurance company is on the hook for potentially hundreds of thousands of dollars in damages if you have an accident five minutes later.
Without an initial payment, there is no financial agreement in place. This payment acts as a “binder,” ensuring that both parties are committed to the contract. If you ever find yourself in a situation where you’ve been in an accident without proper coverage, you might need to know How to Find a Lawyer for Car Accidents to navigate the legal fallout.
Administrative and Setup Costs
Every new policy requires underwriting. This is the process where the company verifies your driving record, checks your credit-based insurance score (in most states), and processes your vehicle’s VIN. These administrative tasks cost the company money. By collecting the first month’s premium, they ensure their basic operational costs are covered from day one.
Protecting Against Immediate Claims
Insurance companies use “loss ratios” to determine their pricing. If they allowed thousands of drivers to start policies for $0 and a high percentage of those drivers filed claims in the first week without ever paying a dime, the insurance company would quickly go bankrupt. The first payment ensures that the driver has “skin in the game.”
Strategies to Minimize Your Initial Payment
If your goal is to find very cheap car insurance no deposit, you need to be strategic about how you set up your policy. Here is a comparison of how different payment structures affect your wallet:
| Payment Plan | Upfront Cost | Long-Term Savings | Best For |
|---|---|---|---|
| Paid in Full (6 Months) | High ($300 – $600+) | 5% – 10% Discount | Those with savings |
| Monthly Installments | Low ($40 – $130) | Standard Rates | Tight monthly budgets |
| Bi-Weekly (Paycheck Aligned) | Very Low ($20 – $65) | Higher Total Fees | Cash-flow management |
One clever trick we recommend is using a credit card to pay the first installment. This allows you to bind the coverage immediately while delaying the actual cash outlay from your bank account for up to 30 days. Just be sure to pay off the balance to avoid interest charges! If you’re dealing with the aftermath of an accident and worried about costs, it’s also helpful to understand How Much Do Lawyers Charge for Accident Claims.
Leveraging Discounts for Very Cheap Car Insurance No Deposit
Discounts are the fastest way to lower both your monthly premium and your initial payment. Since the “deposit” is usually just the first month’s premium, a lower total rate means a lower start-up cost.
- Telematics: Programs that track your driving via an app can offer immediate “participation discounts.”
- Paperless Billing: Most companies shave a few dollars off if you agree to digital-only documents.
- Safe Driver: If you haven’t had a ticket in three years, make sure it’s reflected in your quote.
- Pay-per-mile: If you drive less than 7,500 miles a year, you could save an average of $223 annually.
For those looking for No Down Payment Car Insurance: Get Covered with $0 Upfront, stacking these discounts is essential.
Adjusting Coverage to Lower Upfront Costs
The type of coverage you choose drastically changes the “amount due today.” In a city like Houston, the differences are clear:
- Minimum Liability Only: Estimated down payment ranges from $40–$70.
- Basic Full Coverage: Estimated down payment ranges from $75–$120.
If you drive an older vehicle that is already paid off, switching to liability-only can be the most effective way to secure very cheap car insurance no deposit.
Comparing Coverage Types and Upfront Costs
Choosing between minimum liability and full coverage is a balance of risk and budget. Minimum liability is the cheapest way to drive legally. It covers the other person’s car and medical bills if you are at fault. Full coverage includes Comprehensive and Collision, which protects your car.
If you have a loan or lease, your lender will require full coverage. If you are struggling with the legal requirements of your state, you might want to learn How to Find a Good Car Accident Lawyer to ensure you are fully protected.
Impact of Credit Scores on First Payments
It’s an unfortunate reality in the insurance industry: your credit score matters. In most states, drivers with poor credit may pay 50% to 200% more than those with good credit.
- Good Credit: Average first payment around $53.
- Poor Credit: Average first payment can jump to $120 or more for the exact same coverage.
Regional Cost Variations
Where you live changes the math. For example, Houston drivers face unique risks like heavy traffic congestion, volatile weather (flooding), and higher theft rates.
- Houston Monthly Estimates (Liability): $50–$90
- Houston Monthly Estimates (Full Coverage): $90–$130
Avoiding Misleading Marketing and Scams
When searching for very cheap car insurance no deposit, you will likely encounter “Ghost Brokers.” These are scammers, often found on social media, who promise “instant $0 down” policies. They take your money, provide a fake insurance card, and disappear.
Verifying Legitimate Insurers
Always check the NAIC (National Association of Insurance Commissioners) database to ensure a company is licensed in your state. We also recommend checking AM Best ratings to see if the company is financially stable enough to pay out claims.
Hidden Fees to Watch For
- Installment Fees: Many companies charge $3–$8 per month just for the “privilege” of paying monthly.
- SR-22 Fees: If you are a high-risk driver, there may be a filing fee.
- Cancellation Fees: Some “cheap” insurers charge a fee if you switch companies before your six-month term is up.
Frequently Asked Questions about Low Upfront Cost Insurance
Is “no deposit” car insurance truly free to start?
No. Every legitimate insurer in the USA requires at least the first month’s premium to activate coverage. If an offer sounds too good to be true (like “first month free”), it is likely a scam or involves hidden fees that exceed the cost of a standard premium.
How does my credit score affect the first payment amount?
In most states, insurers use a credit-based insurance score to determine risk. A lower score suggests a higher likelihood of missed payments or claims, leading the insurer to charge a higher premium. Since your first payment is a reflection of your total premium, poor credit will result in a higher “amount due today.”
Can I use a credit card to delay my initial insurance payment?
Yes! This is one of our favorite “Smart Money” tips. By paying with a credit card, the insurer gets their money immediately (binding your coverage), but you don’t have to pay the credit card bill until your next statement is due. This effectively gives you a 30-day “grace period” for your cash flow.
Conclusion
Finding very cheap car insurance no deposit is about understanding the billing cycle rather than looking for a free ride. By focusing on monthly installments, leveraging every available discount, and maintaining a clean driving record, you can get back on the road for less than the cost of a nice dinner out.
At Smart Money & Tech Tips for Americans, we believe financial literacy is the key to managing your budget effectively. Whether you’re comparing insurance rates or looking into Why Brokerage Firm Investment Fees and Account structures, staying informed is your best defense against high costs.
Drive safe, stay covered, and always read the fine print!


