When Dental Insurance Won’t Pay: What You Can Do Right Now
Knowing what to do when dental insurance won’t pay can save you hundreds — sometimes thousands — of dollars. Here’s a quick answer if you need it fast:
If your dental insurance claim was denied, take these steps:
- Read your Explanation of Benefits (EOB) — find the denial reason code
- Check for fixable errors — wrong codes, missing info, or clerical mistakes
- Gather supporting documents — X-rays, clinical notes, and a medical necessity letter
- Submit a written appeal — within 30 to 180 days of the denial notice
- Escalate if needed — contact your state insurance commissioner or request an external review
Dental claim denials are far more common than most people realize. Around 73 million insurance claims are denied every year in the United States. In some dental practices, the denial rate runs as high as 15% to 20%.
Here’s the frustrating part: fewer than 1% of patients ever file an appeal — even though 40% to 60% of internal appeals succeed.
That means most people simply pay out of pocket and move on. They don’t know they have options.
Whether your claim was denied due to a coding error, a policy exclusion, or a cost-containment clause you’ve never heard of, the situation is almost always worth challenging. This guide walks you through exactly how to do it.
What to do when dental insurance won t pay vocabulary:
- car accident injury lawyers
- lawyers that deal with car accidents
- average lawsuit settlement for car accident
Why Dental Claims Get Denied in the First Place
To effectively fight a denied claim, we first need to understand why the insurance company refused to pay. Unlike standard medical insurance, dental insurance functions more like a subsidized discount plan with strict annual caps. In fact, most traditional dental plans have annual maximum benefits ranging from $1,000 to $2,000—limits that have remained virtually unchanged since the 1970s despite decades of inflation.
When comparing your dental coverage to your overall healthcare budget, it is helpful to understand The Ins And Outs Of Health Insurance Cost Per Month to see how different insurance structures allocate risk.
The most common reasons dental claims are rejected include:
- Administrative and Clerical Errors: Simple typos, misspelled names, incorrect dates of birth, or mismatched member identification numbers are incredibly common.
- Coding Discrepancies: Dental offices must use the Current Dental Terminology (CDT) codes maintained by the American Dental Association. If an outdated code is used, or if a procedure is coded incorrectly, the claim will be kicked back.
- Coordination of Benefits (COB) Issues: If you are covered under two dental plans (for example, your own plan and your spouse’s plan), both insurance companies may refuse to pay until they establish which plan is primary and which is secondary.
- Lack of Prior Authorization: Some major procedures, like crowns, bridges, or periodontal surgery, require a pre-treatment estimate or prior authorization. Prior authorization is not a guarantee of final payment, but skipping it almost guarantees a denial.
- Eligibility Problems: The policy may have been inactive on the date of service, or the patient may have been removed from the plan.
- Services Not Covered: The specific procedure performed may be explicitly excluded from your policy contract.
For a deeper dive into how administrative issues trigger rejections, you can review the American Dental Association’s guidance on Common reasons for dental claim rejections.
Cost-Containment Clauses and Policy Limitations
Insurance companies use complex contractual limitations to reduce their payouts. When we look at what to do when dental insurance won t pay, we have to identify if one of these cost-containment clauses was triggered:
- Bundling: This occurs when a payer combines separate, distinct clinical procedures into a single code with a lower reimbursement rate. For example, a payer might bundle a core buildup (D2950) into the crown procedure itself, refusing to pay for the buildup separately.
- Downcoding: If your dentist performs a tooth-colored composite filling on a back molar, the insurance company may “downcode” the procedure to the cheaper silver amalgam filling rate, leaving you to pay the price difference.
- Least Expensive Alternative Treatment (LEAT) Clause: If there are multiple ways to treat a dental issue, a LEAT clause allows the insurer to only pay for the cheapest option. If you get a dental implant, but a removable partial denture could technically fill the gap, the insurer will only reimburse you for the cost of the denture.
- Missing Tooth Clause: If you lost a tooth before your current insurance policy became active, the plan may refuse to pay for any future replacement procedures (like bridges or implants) for that specific tooth.
- Frequency Limitations: Most plans limit how often you can receive specific treatments. For example, cleanings are often limited to twice a year or once every six months, and panoramic X-rays may only be covered once every three to five years.
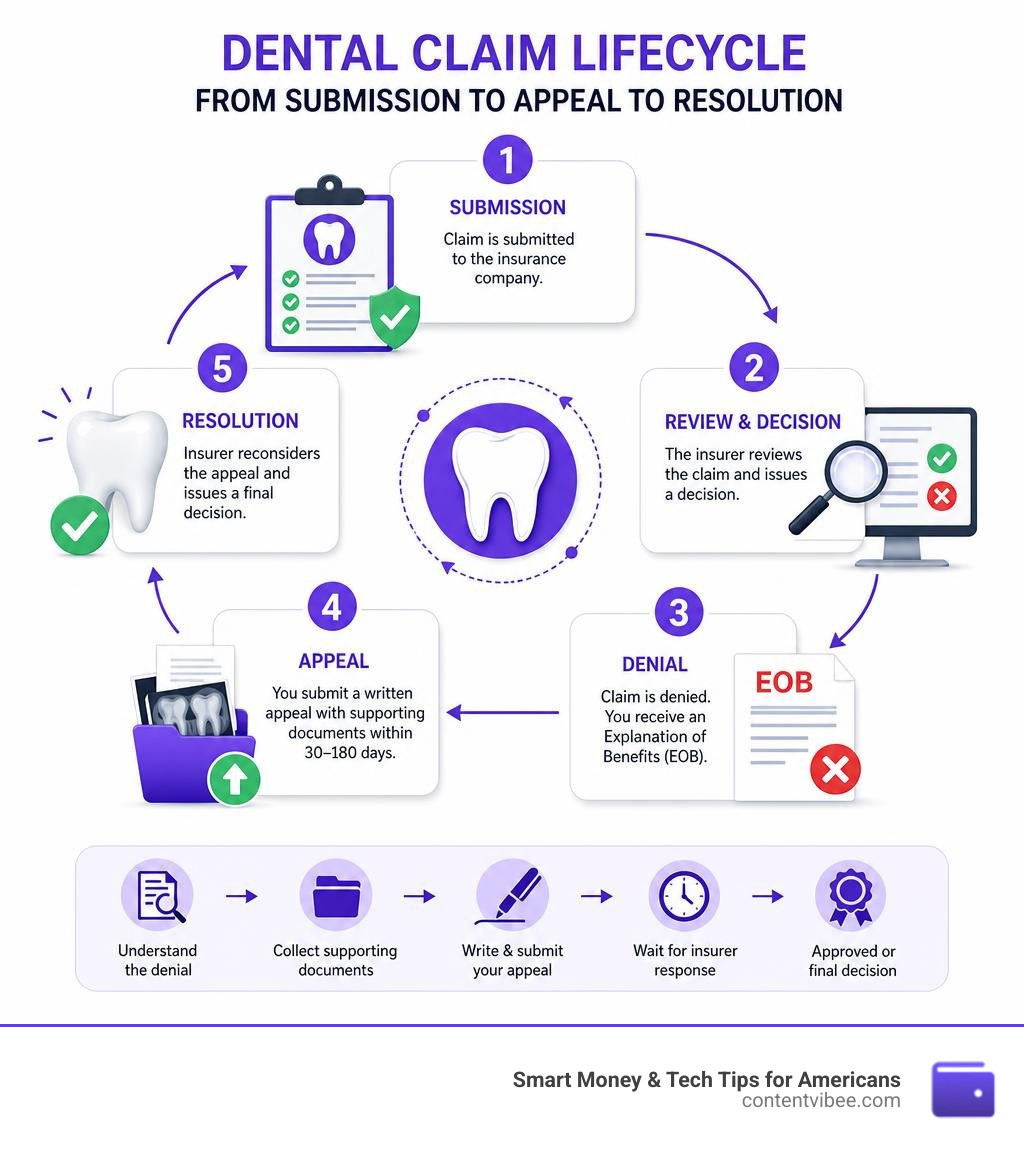
What to Do When Dental Insurance Won’t Pay: The 5-Step Resolution Process
When you receive notice that your insurance company has refused to pay, do not panic. It is appropriate to treat this as the beginning of a negotiation. By establishing a systematic denial management strategy, you can systematically work through the problem.
That you must act quickly. Appeal deadlines typically range from 30 to 180 days from the date of the denial notice or EOB. For a comprehensive overview of how to structure your defense, check out our guide on How to appeal a dental insurance denial.
Here is our step-by-step resolution process.
Step 1: Decode the EOB to Understand What to Do When Dental Insurance Won’t Pay
Your first task is to locate your Explanation of Benefits (EOB). This is not a bill, but a document showing how your insurance company processed the claim. Look closely at the service lines to find the specific alphanumeric code explaining the denial.
These standard Claim Adjustment Reason Codes (CARCs) tell you exactly why the payment was withheld:
- CO-16: Claim/service lacks information or has a submission error. This is a “soft denial,” meaning the insurer just needs more details (like an X-ray or a narrative description) to process it.
- CO-50: These services are not deemed “dentally necessary” by the insurer’s clinical guidelines.
- CO-96: Non-covered service. This is a “hard denial” based on contract exclusions.
To learn more about identifying specific codes on your statement, you can read How to read dental denial codes.
Step 2: Gather Clinical Evidence and Documentation
If the denial is based on clinical necessity or a soft denial for more information, you must build a robust evidence packet. We recommend working closely with your dentist’s billing department to compile:
- High-Quality Diagnostic Images: Clear, properly labeled X-rays, intraoral photographs, or 3D cone-beam computed tomography (CBCT) scans showing the structural damage or decay.
- Periodontal Charting: Comprehensive pocket-depth measurements, especially if you are appealing a denial for periodontal scaling and root planing (SRP).
- A Detailed Clinical Narrative: A patient-specific letter written by your treating dentist describing your symptoms, failed past treatments, and why the specific procedure was clinically required. Boilerplate templates are easily ignored; unique clinical details win cases.
For professional strategies on compiling evidence that insurers cannot ignore, consult these Tips for winning dental appeals.
Step 3: Write and Submit a Formal Appeal Letter
Now, write your formal appeal letter. Keep the tone professional, objective, and evidence-focused. Your letter should:
- State your name, policy number, claim number, and date of service.
- Clearly address the exact reason code cited in the EOB.
- Reference the attached clinical documentation (X-rays, chart notes, narrative).
- Cite specific plan language or clinical guidelines that support your case.
- If your plan is employer-sponsored, mention your protections under the Employee Retirement Income Security Act (ERISA), which gives you legal rights to a full and fair review.
Send your appeal via certified mail with a return receipt requested, or submit it through the insurer’s online portal and take screenshots of the confirmation screen. For more detailed advice on drafting your submission, check out this Guide to fighting a denied dental claim.
Step 4: Track Your Appeal and Follow Up Proactively
Once your appeal is submitted, the clock starts ticking. Under standard guidelines, insurance companies must respond to post-service appeals within 30 to 60 days.
Do not let your claim sit in limbo. Keep a meticulous paper trail. Create a log of every phone call, noting:
- The date and time of the call.
- The name and representative ID of the person you spoke with.
- The exact details of the conversation.
This level of persistence is incredibly powerful. For inspiration on how a detailed paper trail can break through corporate resistance, read A patient’s story of winning a dental bill battle.
Step 5: Escalate Your Case if Your Dental Insurance Won’t Pay After an Appeal
If your internal appeal is denied, you still have options. You can escalate the dispute beyond the insurance company:
- Request an External Review: Many states allow an independent third-party medical professional to review the case. If the independent reviewer agrees the procedure was dentally necessary, the insurance company is legally required to pay. External reviews are free to patients and succeed in 40% to 70% of cases.
- File a Complaint with the State Insurance Commissioner: If you believe the insurer is acting in bad faith, violating state laws, or ignoring policy terms, file a formal complaint with your state’s regulatory agency.
- Contact the Department of Labor (DOL): If your dental plan is an employer-sponsored self-insured plan, it is regulated by federal law under the DOL rather than state insurance commissioners.
To find out where to submit your regulatory complaints, explore this resource on Where to start with unresolved insurance denials.
Alternatives and Financial Options if Your Appeal Fails
Sometimes, despite your best efforts, an appeal is unsuccessful. Perhaps the service is genuinely excluded from your contract, or you have hit your strict annual maximum benefit.
This is a massive hurdle for many Americans. Approximately 23% of Americans do not have dental insurance, and 40% of adults skip necessary dental care due to costs, regardless of whether they have a policy.
If you are facing a large out-of-pocket bill, consider these alternative solutions:
| Option | Best For | Typical Savings / Benefits |
|---|---|---|
| Dental Savings Plans | Immediate treatments, major procedures, and those with pre-existing conditions. | 10% to 60% off standard dental fees. |
| In-House Payment Plans | Splitting the cost of treatment over several months directly with the provider. | Interest-free or low-interest monthly payments. |
| Dental Schools | Budget-conscious patients willing to spend more time in the chair. | 30% to 50% cheaper than private practices. |
| Third-Party Financing | Patients with decent credit scores who need to pay over a longer period. | Promotional 0% interest periods (e.g., CareCredit). |
Dental Savings Plans vs. Traditional Insurance
If traditional insurance has let you down, dental savings plans (also called dental discount plans) are an excellent alternative.
Unlike insurance, dental savings plans:
- Have no annual caps or spending limits.
- Have no waiting periods, meaning you can sign up today and use the discounts tomorrow.
- Do not require a complex claims process—you simply pay the discounted rate directly to an in-network dentist.
- Offer pre-negotiated discounts ranging from 10% to 60% on everything from cleanings to cosmetic work and implants.
Flexible Payment Plans and Financing
Many dental practices are highly willing to work with patients to keep care affordable. Ask your dentist’s billing office if they offer in-house payment plans, which allow you to divide your balance into manageable monthly payments.
Alternatively, you can look into third-party medical financing or pay-over-time plans. If you are managing healthcare for your whole household, understanding The Definitive Guide To Family Health Insurance Plans can help you structure your family’s benefits to minimize out-of-pocket surprises. Additionally, if you are looking after older family members, it is worth exploring Everything You Need To Know About Health Insurance Plans For Senior Citizens to identify specialized coverage options.
Frequently Asked Questions About Dental Insurance Denials
What is the success rate of appealing a dental insurance denial?
Appealing is highly effective. Between 40% and 60% of internal appeals succeed, meaning the insurance company reverses its decision once they receive proper documentation. If you escalate the case to an external review, the success rate rises to 40% to 70%. Because fewer than 1% of patients ever appeal, insurers count on people simply giving up. Patient advocacy and persistence are your greatest tools.
How long do I have to appeal a denied dental claim?
The appeal window typically ranges from 30 to 180 days from the date you receive your EOB or denial notice. It is critical to check your specific plan guidelines immediately. Missing this deadline means you forfeit your legal right to challenge the decision.
What is a LEAT clause and how does it affect my coverage?
LEAT stands for Least Expensive Alternative Treatment. It is a cost-containment clause that allows your insurer to limit their payment to the cost of the cheapest standard treatment that could address your dental problem. For example, if you receive a high-quality composite (tooth-colored) filling, a LEAT clause may limit your reimbursement to the cost of a silver amalgam filling, leaving you to pay the difference out of pocket.
Conclusion
At ContentVibee, we believe that understanding your personal finance options and legal rights is the best way to protect your hard-earned money. Insurance companies often count on patients feeling too overwhelmed to fight back. However, by understanding what to do when dental insurance won t pay and systematically following the appeals process, you can reclaim control over your healthcare expenses.
If you are dealing with other types of insurance issues, you may also find our guide on The Ultimate Guide To Handling An Auto Insurance Claim Denial highly valuable.
To learn more about navigating complex insurance policies, protecting your personal finances, and understanding your consumer rights, Learn more about protecting your finances in our Car Accident Settlement Guide 2026.