


Tazopha Investment Group Legitimacy and Investor Risk Analysis is a critical topic for any self-directed investor considering this platform in April 2026.
Here is a quick summary before we dive deeper:
| Key Question | Quick Answer |
|---|---|
| Is Tazopha regulated? | No confirmed SEC or FINRA registration found as of April 2026 |
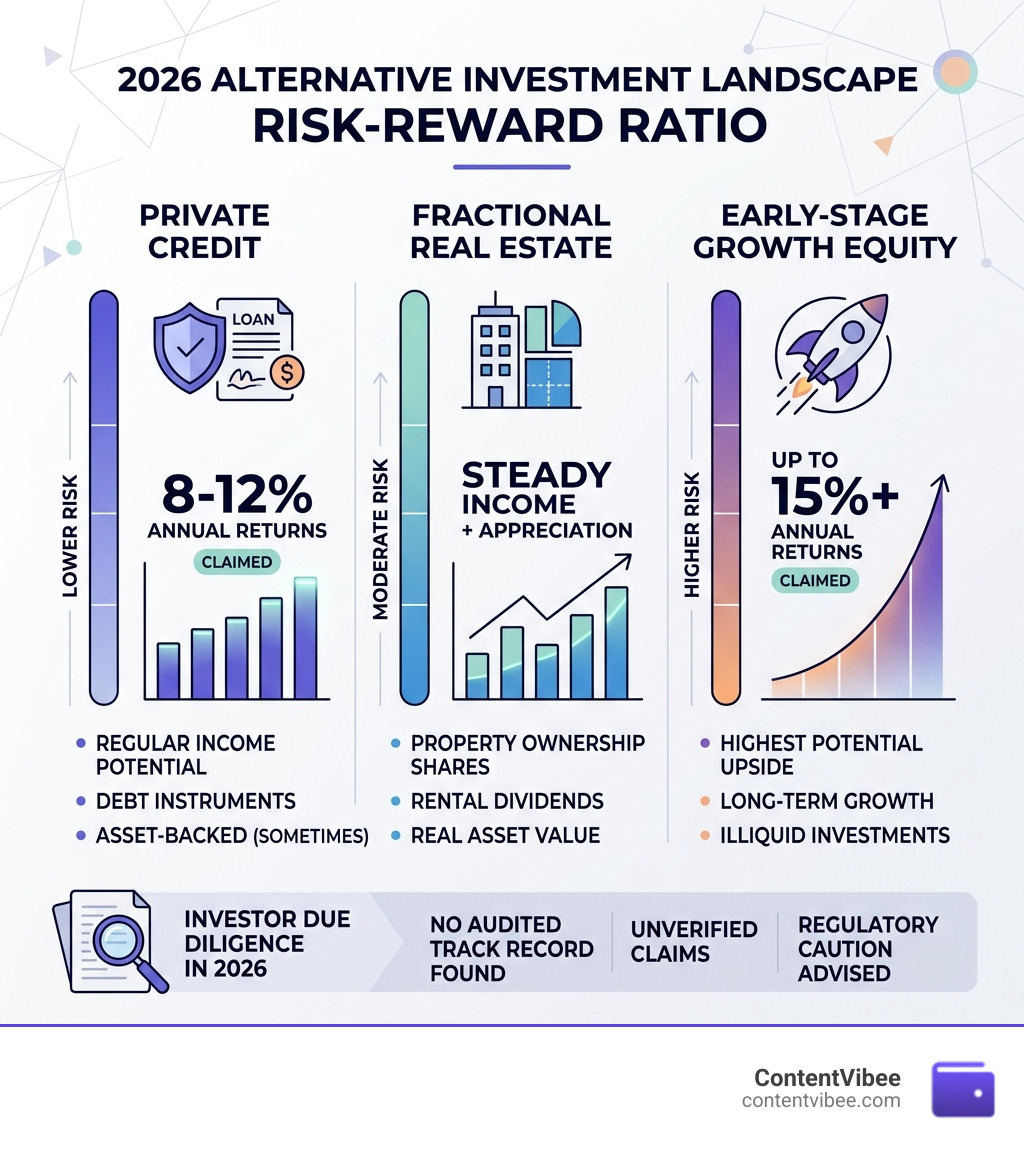
| Core offerings | Private credit, fractional real estate, early-stage growth equity |
| Claimed returns | 8-12% (private credit), up to 15% (growth equity) annually |
| Independent audits | None publicly verified |
| Red flags present? | Yes — promotional content, no audited track record, unverified claims |
| Suitable for beginners? | High caution advised without full due diligence |
Alternative investments are growing fast. More platforms are promising institutional-grade returns to everyday investors. That sounds great — but it also creates real risk, especially when a platform’s regulatory status and track record are unclear.
Tazopha presents itself as a democratizing force, offering access to private credit, fractional real estate, and early-stage equity deals. The marketing is polished. The projected numbers are compelling.
But compelling marketing is not the same as verified legitimacy.
What you’ll find across Tazopha’s online presence is a pattern: strong promotional content, minimal independent verification, and significant gaps around fees, regulatory filings, and audited performance data. For a self-directed investor who values control and transparency, those gaps matter — a lot.
This article breaks down exactly what is known, what is missing, and what you need to check before committing a single dollar.
What is Tazopha Investment Group and Its Core Focus?
To understand the Tazopha Investment Group Legitimacy and Investor Risk Analysis, we first have to look at what the group claims to be. Based in Wallins Creek, Kentucky, Tazopha positions itself as a boutique investment firm that bridges the gap between traditional retail banking and high-level private equity.
Their stated mission is to provide “everyday” investors with access to deals usually reserved for the ultra-wealthy. We see them focusing heavily on three pillars: private credit, fractional real estate, and early-stage growth equity. They argue that the traditional “60/40” portfolio (60% stocks, 40% bonds) is dead because bonds no longer provide a safety net when interest rates rise.
Instead, they suggest a model that integrates personal budgeting with aggressive alternative asset allocation. You can learn more about their specific operational claims by reading how tazopha investment group work or exploring what you need to know about how tazopha investment involves for the average user.
Investment Focus Areas
The core of their pitch involves moving capital into assets that don’t always move in sync with the stock market.
- Private Credit: They claim to offer yields between 8% and 12% annually. These are essentially loans made to mid-sized companies, secured by the company’s assets.
- Fractional Real Estate: This allows investors to own a “slice” of a property, such as an apartment complex or a development project, without having to manage the building themselves.
- Early-Stage Growth Equity: This is high-risk, high-reward territory. They highlight the potential for a $10,000 position to grow at 15% annually, turning into over $40,000 in ten years, compared to just $21,000 in a standard index fund.
While these numbers look great on a spreadsheet, the actual mechanics of How Tazopha Investment Work – tazopha.com rely on their internal vetting process, which they claim only accepts about 3% of the opportunities they review.
Tazopha Investment Group Legitimacy and Investor Risk Analysis: Regulatory Oversight
When we evaluate any financial entity, the first thing we look for is a “license to drive.” In the United States, investment firms managing public funds or offering securities typically must register with the Securities and Exchange Commission (SEC) or the Financial Industry Regulatory Authority (FINRA).
As of April 2026, our research into Tazopha Investment Group Legitimacy and Investor Risk Analysis shows a concerning lack of public regulatory filings. While they use professional terminology like “due diligence” and “accredited standards,” there is no verifiable evidence that they are a registered investment adviser (RIA) or a broker-dealer.
This is a major point of comparison when looking at other digital assets; for instance, you might compare this to Why Rep Sheri Biggs Bitcoin Investment Legitimacy discussions where regulatory clarity is often the deciding factor between a safe bet and a total loss. Without SEC oversight, investors lose a massive layer of protection, including standardized disclosures and the ability to file formal complaints that lead to legal action. You should check the Tazopha Investment Group Review 2025: Is It Legit or a Scam? for updated community sentiment on their legal standing.
Evaluating Tazopha Investment Group Legitimacy and Investor Risk Analysis for 2026
Legitimacy isn’t just about a logo on a website; it’s about third-party verification. In 2026, a legitimate firm should provide:
- Audited Financials: A reputable accounting firm should verify that the returns being advertised are actually being paid out.
- Legal Disclosures: Detailed PPMs (Private Placement Memorandums) that outline exactly how you can lose your money.
- Verifiable Physical Presence: While they list Wallins Creek, KY, as a home base, a deep dive into How Tazopha Investment Group Work – tazopha.com reveals more promotional storytelling than hard corporate data.
We find it interesting that 80% of New Year’s resolutions fail by February. This is often because people get swept up in “hype” rather than “habits.” Investing in an unregulated platform is often a “hype” decision. We recommend looking for platforms that offer audited transparency.
Analyzing Performance Metrics and Transparency

Transparency is the antidote to risk. When we look at Tazopha, we see a lot of “projected” returns but very little “historical” data. They talk about private credit yielding 8% to 10%, which sounds fantastic compared to a 10-year Treasury yield of roughly 4.2%. However, a Treasury bond is backed by the US government. A private credit loan from Tazopha is backed by… well, whatever company they chose to lend to.
If the platform isn’t transparent about its “default rate” (how many loans go bad), the 10% yield is a meaningless number. Furthermore, their fee structures remain vague. Do they take a “2 and 20” cut like traditional hedge funds? Or are there hidden “onboarding” fees? Without a clear breakdown, your actual net return could be significantly lower than the “sticker price” they promote. For broader insights on how global economic shifts affect these types of groups, the GESI Initiative: Sharing Insights on Global Issues provides excellent context on market transparency.
Realistic Returns vs. Promoted Risks in Tazopha Investment Group Legitimacy and Investor Risk Analysis
Let’s talk math. Tazopha promotes a 15% growth rate for early-stage equity.
- The Dream: A $10,000 investment becomes $40,456 in 10 years.
- The Reality: Early-stage companies have a failure rate of roughly 70-90%.
If you put $10,000 into one deal and it fails, you have $0. If you put $10,000 into an index fund at 8%, you have $21,589. The Tazopha Investment Group Legitimacy and Investor Risk Analysis must account for the fact that higher yields always come with a higher probability of total capital loss. We believe a disciplined approach involves allocating no more than 10% to 20% of your total portfolio to these types of “alternatives” to prevent a single bad deal from ruining your retirement.
Key Risks: Liquidity, Withdrawals, and Market Downturns
One of the biggest “gotchas” in private equity and fractional real estate is liquidity. Unlike a stock you can sell in two seconds on your phone, these investments are often “locked up.”
| Asset Type | Typical Yield (2026) | Liquidity Level | Risk Profile |
|---|---|---|---|
| 10-Year Treasury | 4.2% | High (Daily) | Very Low |
| Tazopha Private Credit | 8-12% | Low (Months/Years) | Moderate to High |
| Fractional Real Estate | 7-10% | Very Low (Years) | Moderate |
If the economy takes a downturn in late 2026, you might want to pull your money out. With Tazopha, it’s unclear if that’s even possible. Most private funds have “gate” provisions that allow them to stop withdrawals during market stress to prevent a “run on the bank.” If you can’t get your money when you need it most, is the 10% yield really worth it?
Managing Financial Loss and Recovery Options
In the unfortunate event that an investment platform turns out to be illegitimate or suffers a massive security breach, you need a plan. We’ve seen a rise in unauthorized bank transaction how to dispute and recover money USA 2026 cases, especially involving fintech apps.
If you have linked your primary bank account to an unverified platform and see suspicious activity, follow these steps:
- Immediate Freeze: Contact your bank to freeze all outgoing transfers.
- Identity Theft Protection: If you shared your SSN or tax info, use a service to monitor your credit report for fraud.
- Wire Transfer Fraud Victim Recovery: If you’ve sent a wire, contact the FBI’s IC3 (Internet Crime Complaint Center) immediately. Recovery options for wires are extremely time-sensitive.
- Zelle and Payment Apps: Zelle fraud transaction recovery steps and bank protection options USA are often limited because Zelle is treated like cash. Be extremely wary of using these for large investments.
Due Diligence and Red Flags for Potential Investors

Before you sign up for anything, you must perform your own due diligence. We have noticed several red flags regarding Tazopha that every investor should weigh:
- Promotional Bias: Most of the information available online about Tazopha is published on blogs that appear to be affiliate-driven or written by the company itself.
- The “Kentucky” Narrative: They lean heavily on a “small-town, no-nonsense” branding. While charming, branding is not a substitute for a balance sheet.
- Accreditation Ambiguity: Legitimate private equity usually requires you to be an “Accredited Investor” (meaning you have a high net worth or income). If Tazopha is letting anyone in with $500, they might be bypassing important investor protection laws.
Approximately 40% of our daily actions stem from habits, not conscious decisions. If you have a “habit” of chasing high-yield trends without reading the fine print, you are at risk. We suggest treating every investment like a “non-negotiable bill” — verify the recipient’s legitimacy before you pay.
Frequently Asked Questions about Tazopha Investment Group
Is Tazopha Investment Group a registered financial entity?
As of April 2026, there is no public record of Tazopha Investment Group being registered as an investment advisor with the SEC or FINRA. This means they are not subject to the same strict reporting and consumer protection rules as major banks or brokerage firms.
What are the minimum investment requirements and accreditation standards?
Tazopha’s marketing suggests they are “democratizing” finance, which often implies low minimums (sometimes as low as $1,000). However, most legitimate private credit and equity deals are restricted to “Accredited Investors” under SEC Regulation D. If they are offering these to the general public without a specific exemption, it raises significant legal questions.
How does Tazopha handle liquidity and investor withdrawals during downturns?
The platform focuses on “hard assets” like real estate and private loans. These are inherently illiquid. Based on their available documentation, there is no guaranteed secondary market to sell your “shares,” meaning your money could be locked up for 3 to 7 years depending on the specific deal’s exit strategy.
Conclusion
Our final Tazopha Investment Group Legitimacy and Investor Risk Analysis for April 2026 is one of “High Caution.” While the platform offers a modern, accessible way to enter alternative investments, the lack of regulatory oversight and audited performance data is a massive hurdle.
We believe that wealth is built through consistency and capital preservation. Chasing a 15% return is great, but not if it risks 100% of your principal. If you choose to move forward, treat it as a “speculative” play. Never invest money you cannot afford to lose, and never make it more than 5% of your total portfolio until they provide third-party verification of their returns.
Secure your financial future with ContentVibee by staying informed, asking the hard questions, and prioritizing platforms that value transparency over hype. Your long-term portfolio health depends on the due diligence you do today.


