Investment Calculator Accuracy and Financial Planning Strategy is something every self-directed investor should understand before trusting any projection with real money.
Here’s a quick summary of what you need to know:
- The calculator uses a 6% default annual return — a conservative estimate based on the S&P 500’s long-term average of ~10%
- Projections are hypothetical — they do not guarantee future results
- Taxes, fees, and inflation are excluded — meaning real returns will likely be lower than what the tool shows
- You can adjust inputs — running conservative (lower %) and aggressive (higher %) scenarios gives a more realistic range
- It’s a planning tool, not a prediction engine — best used alongside other tools like a Retirement or Mutual Fund Calculator
The goal of any investment is simple: get more out than you put in. Compounding returns make that possible over time — but only if your projections are grounded in reality.
Investment Calculator
See how your money can grow over time. Enter your starting balance, monthly contributions, and expected timeline to map out your financial future.
*Projections are estimates based on monthly compounding and end-of-month contributions. These figures do not account for taxes, inflation, or advisory fees.
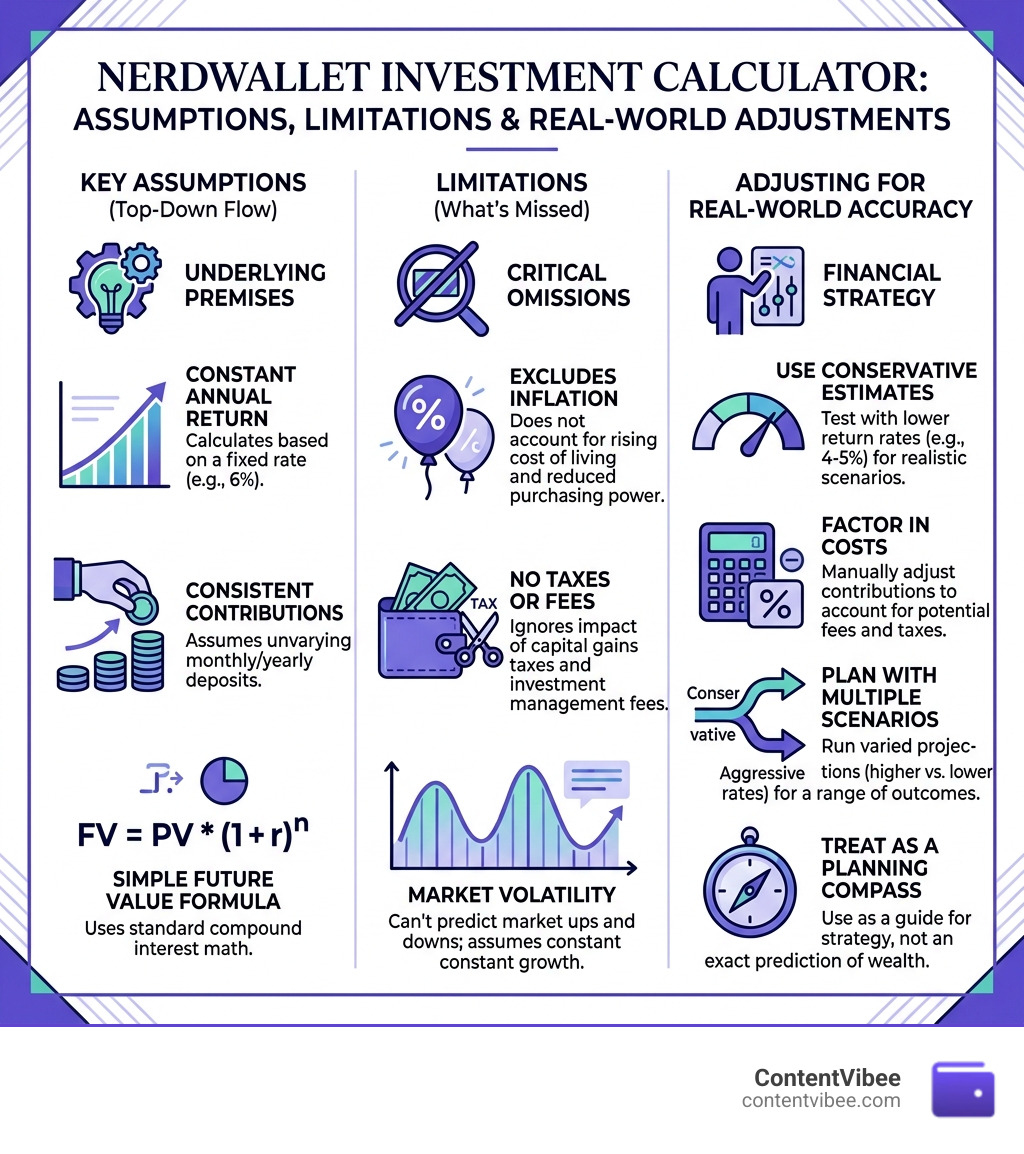
The problem? Many investors take calculator outputs at face value. They see a big future number and feel confident. But that number assumes a constant return rate, zero fees, and no inflation drag. In the real world, none of those things are true.
That gap between what the calculator shows and what you actually keep is exactly what this guide addresses.
Investment Calculator Accuracy and Financial Planning Strategy
When we look at Investment Calculator Accuracy and Financial Planning Strategy, we have to treat the tool as a compass, not a GPS. It points you in the right direction, but it doesn’t account for the traffic jams or potholes you’ll encounter on the road.
The calculator works on a "future value" formula. It takes what you have now, adds what you plan to contribute, and multiplies it by an interest rate over a set number of years. While the math is perfect, the inputs are often guesses. This is why Why a Compound Interest Calculator for Retirement is such a vital concept; it helps you visualize the "snowball effect" of your money, even if the snowball occasionally melts a bit due to market heat.
Adjusting Inputs for Investment Calculator Accuracy and Financial Planning Strategy
To get the most out of an investment calculator, you need to be precise with your inputs. The tool requires four main pieces of data:
- Initial Investment: The "seed" money you are starting with today.
- Years to Grow: Your time horizon. If you’re saving for a car in 2032, that’s 6 years from our current date of April 2026.
- Estimated Rate of Return: The percentage you expect to earn annually.
- Recurring Contributions: How regularly you’ll add money (monthly or annually).
By tweaking these, you can see how a small change—like adding an extra $50 a month—can drastically shift your long-term outcome.
Reliability of Hypothetical Results
We must remember the fine print: projections are hypothetical. The calculator assumes a "constant" rate of return. In reality, the market is a seesaw. One year the S&P 500 might be up 20%, and the next it might be down 10%. The calculator doesn't "see" this volatility; it just draws a smooth upward line.
Because there are no guarantees in investing, the reliability of these projections depends on your ability to use realistic benchmarks rather than "best-case scenario" numbers.
Evaluating Default Assumptions: 6% Returns vs. Historical Reality
Standard investment calculators often set their default return at 6%. Why 6% when the S&P 500 has a long-term historical average of 10%? It’s a safety net. By under-promising, the tool helps you avoid the "wealth illusion"-thinking you'll have more than you actually will. For broader background on long-term market history, the S&P 500 is a useful reference point.
If you want to dive deeper into how these numbers are picked, check out our guide on Understanding Investment Return Assumptions.
Realistic Rate of Return in 2026
As of April 2026, a "realistic" return depends entirely on your asset mix.
- Stocks: While the 10% average holds over decades, short-term windows can be much lower.
- Bonds: U.S. government bonds usually offer a 3% to 4% annual return.
- Cash/CDs: High-yield savings and CDs are currently hovering around the 3-4%+ mark, making them great for short-term goals but poor for long-term wealth building.
Long-term Wealth Protection and Investment Calculator Accuracy and Financial Planning Strategy
One of the biggest threats to your strategy is the loss of purchasing power. A standard retirement calculator often defaults to a 3% inflation rate. This is crucial because $1 million in 2026 will not buy the same amount of groceries or gas in 2056.
To maintain accuracy, we recommend:
- Assuming a 95-year life expectancy: It’s better to have extra money at the end than to run out at 85.
- Planning for 2% annual salary increases: This helps your contributions keep pace with your lifestyle.
The Impact of Fees and Taxes on Projected Wealth
This is where the "simple" calculator can lead you astray. Most basic tools do not subtract the cost of doing business. If your mutual fund has a 1% expense ratio, that's 1% less compounding for you every single year. Over 30 years, a 1% fee can eat up nearly 25% of your total potential wealth.
For more on this, we've broken down Understanding Investment Platform Fees and Navigating Investment Advisory Costs.
Comparison: Gross vs. Net Returns (30-Year Projection)
| Scenario | Annual Return | Annual Fee | Final Balance (on $100k) |
|---|---|---|---|
| Gross Return | 7% | 0% | $761,225 |
| Net Return | 7% | 1% | $574,349 |
| Total Cost of Fees | - | - | $186,876 |
Tax Implications and Net Returns
Taxes are the other "silent killer" of investment returns. Depending on whether you use a Roth IRA, a 401(k), or a standard brokerage account, your "take-home" investment growth will vary. Understanding the difference between Understanding Marginal vs Effective Rates is key here.
To stay tax-efficient, many investors prefer ETFs over mutual funds, as ETFs are structured to trigger fewer capital gains distributions.
Identifying Hidden Investment Costs
Beyond the obvious fees, keep an eye out for transaction costs and "load" fees (commissions paid to buy or sell a fund). We always suggest looking for "no-load" funds to keep your costs at rock bottom. If you are using a managed service, the Autopilot app can help by providing comprehensive fee and risk reviews to ensure you aren't overpaying for performance.
Strategic Diversification to Prevent Financial Loss
A core part of any Investment Calculator Accuracy and Financial Planning Strategy is diversification. Financial experts often describe a portfolio like a seesaw: when one investment (like tech stocks) dips, another (like bonds or gold) should hopefully rise to balance it out.
Balancing Stocks and Bonds
Your mix of assets should reflect your risk tolerance.
- Index Funds: These are great for low-fee, broad market exposure.
- REITs: Real Estate Investment Trusts allow you to invest in property without being a landlord.
- Alternative Investments: To see how these fit in, read Understanding Traditional vs Alternative Investments.
Conservative vs. Aggressive Scenarios
We recommend "stress-testing" your plan. Run the calculator three times:
- The Dreamer: Use an 8-9% return (Aggressive).
- The Realist: Use the 6% default.
- The Worst-Case: Use a 3-4% return (Conservative).
If your financial plan still works in the "Worst-Case" scenario, you’ve built a strategy that can survive market volatility.
Frequently Asked Questions about Investment Projections
How accurate is the 6% default return rate?
It is a historically conservative estimate. While the S&P 500 has averaged 10% since its inception, 6% accounts for potential "lost decades" and provides a margin of safety for your planning.
Does the calculator account for annual inflation?
Standard investment calculators do not automatically adjust for inflation in the final "total" number. You should manually subtract ~3% from your expected return to see your "real" purchasing power growth.
Can I use this tool to plan for early retirement (FIRE)?
Yes, but you’ll need to be aggressive with your "recurring contribution" input. FIRE (Financial Independence, Retire Early) usually requires saving 50% or more of your income, which you can model by increasing your monthly deposits in the tool.
Conclusion
At the end of the day, Investment Calculator Accuracy and Financial Planning Strategy is about preparation, not perfection. The calculator is a fantastic starting point to see what's possible, but it’s your job to account for the real-world variables like fees, taxes, and inflation.
At ContentVibee, we believe in empowering investors with the best tools and knowledge. Whether you are using professional financial planning tools or looking for automated portfolio management, always remember to run conservative scenarios.
If you're ready to take the next step, View the best investments right now and start building a portfolio that can withstand whatever the market throws at it.