


What the RMD Age Table Means for Your Retirement Withdrawals
The RMD age table is the IRS tool that tells you exactly how much you must withdraw from your retirement accounts each year — and ignoring it can cost you dearly.
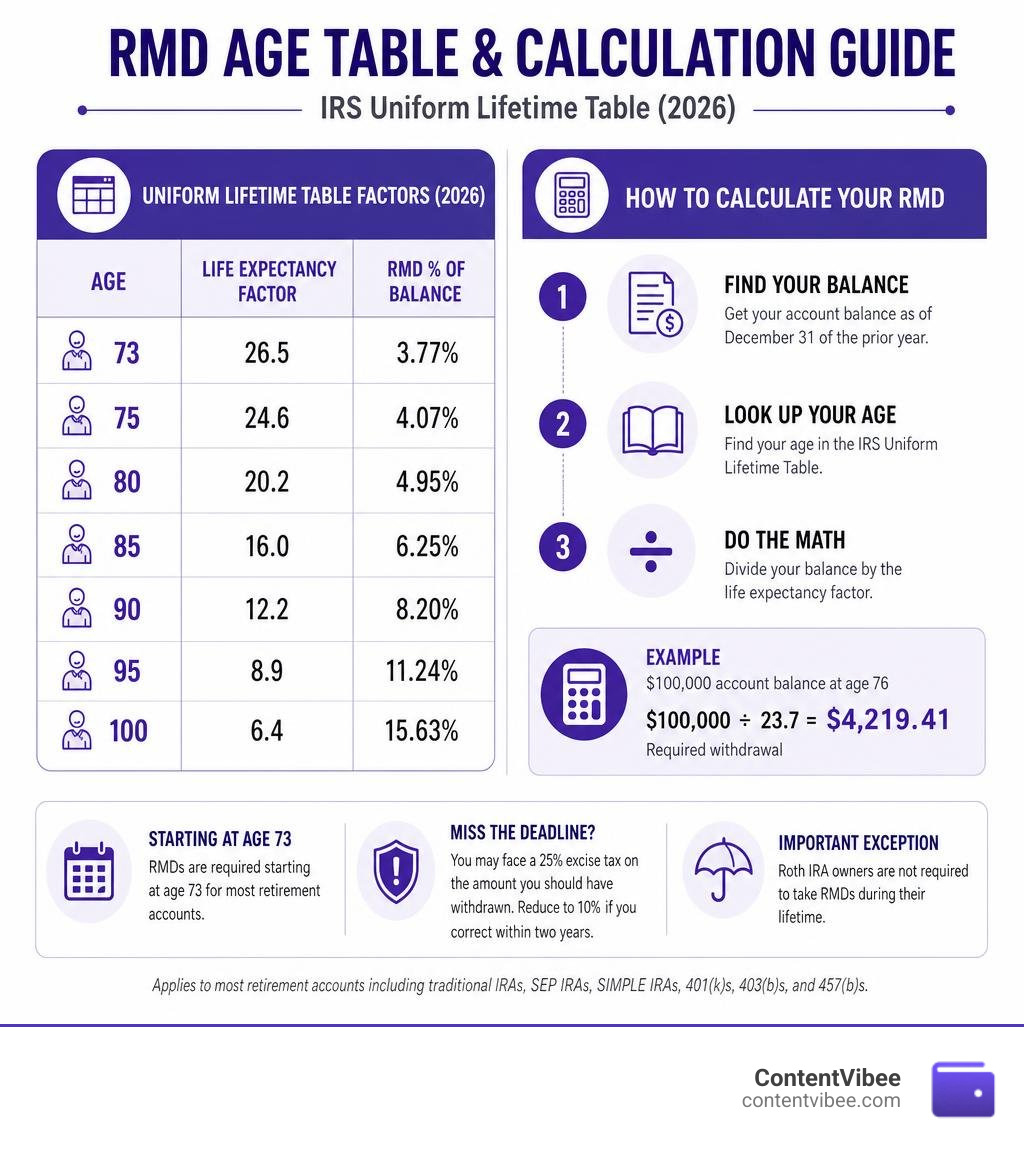
Quick answer: Here are the key Uniform Lifetime Table factors you need to know for 2026:
| Age | Life Expectancy Factor | RMD % of Balance |
|---|---|---|
| 73 | 26.5 | 3.77% |
| 75 | 24.6 | 4.07% |
| 80 | 20.2 | 4.95% |
| 85 | 16.0 | 6.25% |
| 90 | 12.2 | 8.20% |
| 95 | 8.9 | 11.24% |
| 100 | 6.4 | 15.63% |
To calculate your RMD:
- Find your account balance as of December 31 of the prior year
- Look up your age in the IRS Uniform Lifetime Table
- Divide your balance by the life expectancy factor
Example: A $100,000 account balance at age 76 ÷ 23.7 = $4,219.41 required withdrawal.
The IRS requires most retirement account holders — including traditional IRAs, SEP IRAs, SIMPLE IRAs, 401(k)s, 403(b)s, and 457(b)s — to start taking withdrawals at age 73. Miss that deadline and you face a 25% excise tax on the amount you should have withdrawn. That penalty drops to 10% only if you correct the mistake within two years.
There’s one important exception worth knowing early: Roth IRA owners are not required to take RMDs during their lifetime. If you’re rolling a 403(b) into a Roth IRA, that’s a significant long-term advantage.
This guide covers both sides of the “rmd age table” world — the IRS rules every retiree needs, and how R Markdown (Rmd) developers can build automated age tables for financial reporting.
Understanding the IRS RMD Age Table and Calculation Rules
When dealing with required minimum distributions, the IRS does not use a one-size-fits-all approach. Depending on your marital status and whether you are the original account owner or a beneficiary, you must consult different life expectancy tables.
To help clarify which rmd age table applies to your situation, we have put together a comparison of the two primary tables used for RMD calculations:
| Feature | Uniform Lifetime Table | Single Life Expectancy Table |
|---|---|---|
| Primary User | Unmarried account owners, married owners whose spouses are not more than 10 years younger | Beneficiaries of inherited retirement accounts (non-spouse and certain spouse situations) |
| How It Works | Assumes a joint life expectancy with a beneficiary 10 years younger | Based solely on the individual life expectancy of the beneficiary |
| RMD Percentage | Generally lower withdrawal percentages (e.g., 3.77% at age 73) | Higher withdrawal percentages because it does not assume a joint life |
| Yearly Adjustment | You look up your new age and corresponding divisor factor every year | You find the initial divisor for your age in the first year, then subtract 1.0 each subsequent year |
The age 73 milestone is a critical turning point. Once you reach this age, the IRS expects you to begin pulling money out of tax-deferred accounts. If you do not take any distributions, or if your distributions are not large enough, you may have to pay a 25% excise tax on the amount not distributed. Fortunately, the IRS offers a correction window that reduces this penalty to 10% if the missed distribution is withdrawn and corrected within two years. To report this and pay or request a waiver for the penalty, you must file Form 5329 with your federal tax return.
The required minimum distribution for any given calendar year is determined by taking the account balance as of December 31 of the immediately preceding calendar year and dividing it by the corresponding distribution period from the appropriate IRS table.
How To Use the Uniform RMD Age Table for Lifetime Distributions
Using the Uniform Lifetime Table is a straightforward process, but it requires careful attention to dates and ages. First, you must determine your account balance at the close of business on December 31 of the prior year. This is the exact number you will use as your starting point.
Next, look up your age on the rmd age table—specifically, the age you will turn during the current calendar year, not your age on the day you make the withdrawal. Find the divisor factor next to your age. For example, if you turn 75 this year, your factor is 24.6.
Once you have these two figures, divide the prior year-end account balance by the divisor factor to find your RMD for the year.
Timing is everything when it comes to tax planning. While subsequent annual RMDs must be taken by December 31 each year, the IRS provides a one-time grace period for your very first distribution. You can delay your first withdrawal until April 1 of the calendar year following the year you turn 73.
However, delaying your first RMD comes with a major catch: you will have to take two distributions in that same tax year. Your first RMD must be taken by April 1, and your second RMD must be taken by December 31 of that same year. This double distribution can push you into a much higher tax bracket, so we generally advise planning ahead to avoid this tax spike.
Single Life Expectancy RMD Age Table for Inherited Accounts
Inherited retirement accounts operate under a completely different set of rules. If you inherit an IRA or a 401(k), you cannot use the Uniform Lifetime Table. Instead, you must use the Single Life Expectancy Table.
For Eligible Designated Beneficiaries (EDBs)—such as chronically ill individuals, minor children of the owner, or beneficiaries who are not more than 10 years younger than the deceased—distributions are calculated using the “minus-1” method. Under this method, you look up the beneficiary’s age in the Single Life Expectancy Table in the year following the owner’s death to find the initial divisor factor. For each subsequent year, you simply subtract 1.0 from that initial factor rather than looking up a new age in the table.
Spousal beneficiaries have more flexibility. They can choose to use the recalculation method, which allows them to look up their actual age in the Single Life Expectancy Table every year, resulting in smaller required withdrawals over time.
For most non-spouse beneficiaries who do not qualify as EDBs, the SECURE Act rules dictate that the entire account must be fully distributed within 10 years of the original owner’s death. In some cases, annual RMDs must still be taken during years 1 through 9 using the Single Life Expectancy Table, with the remaining balance completely cleared out by December 31 of the 10th year.
Programmatic RMD Planning: Generating Age Tables in R Markdown (Rmd)
As a digital media company bridging the gap between personal finance and technology, we know that “rmd age table” has a double meaning. For retirees, it is the IRS Required Minimum Distribution table. For financial analysts, developers, and researchers, it refers to generating demographic age tables in R Markdown (.Rmd) documents.
Using R Markdown to build age-based demographic tables is an excellent way to automate financial planning, prepare client reports, and conduct reproducible data analysis. Instead of manually copying and pasting IRS tables or demographic data into static documents, we can use programmatic workflows to generate clean, dynamic tables that update automatically when the underlying data changes.
Best Packages for Creating Demographic Age Tables in R
When building demographic age tables in R Markdown, selecting the right package depends on your specific analysis goals. Several highly capable packages exist to streamline this process:
- reportRmd: This package is exceptional for generating tidy, publication-ready clinical and demographic tables. The primary function
rm_covsumallows you to compile summary statistics by group effortlessly. For those working with survival analyses or timelines, functions like rm_survsum: Summarise survival data by group in reportRmd: Tidy Presentation of Clinical Reporting and rm_survtime: Display survival rates and events for specified times in reportRmd: Tidy Presentation of Clinical Reporting offer advanced grouping capabilities. You can learn more about this ecosystem via the Tidy Presentation of Clinical Reporting • reportRmd documentation. - DemographicTable: If you need an intuitive, straightforward tool to compare demographic characteristics across multiple groups, this package is a perfect match. It automatically computes p-values and handles statistical tests under the hood. For a complete introduction, check out the Intro.qmd vignette.
- rtables: Developed for complex reporting environments,
rtablesseparates the layout definition from the actual data. This allows you to build highly customized, nested tables with multiple levels of column and row splits. - PatientProfiles: When working with observational health data or large cohorts, this package provides tools to enrich patient data. It is highly efficient for calculating age metrics dynamically.
- flextable: A versatile formatting package that integrates beautifully with R Markdown to produce highly styled HTML, Word, and PDF outputs.
Formatting Age Statistics and Handling Missing Data in Rmd
When presenting age statistics in a demographic table, you must choose how to represent the data based on whether age is treated as a continuous or categorical variable.
For continuous age data, it is best practice to display the mean (with standard deviation) or the median (with interquartile range or full range). For categorical age groups (e.g., “73-75”, “76-80”, “81+”), presenting counts and percentages is the most effective approach.
Handling missing age data is critical to maintaining the integrity of your reports. In R Markdown, packages like reportRmd and DemographicTable automatically detect missing values and display them in a dedicated “Missing” row, ensuring transparency.
If you are working with large patient or client databases, you can use the PatientProfiles package to calculate ages and group them programmatically. For example, the addAge function calculates age at a specific index date, while the ageGroup parameter allows you to define custom brackets. You can find detailed examples of this in the Demographics.rmd vignette.
Advanced Rmd Techniques for Stratified Demographic Tables
For professional financial and clinical reports, we often need to present age-stratified summary tables that compare demographics across different groups, such as different retirement plan types or trial arms.
The rtables package is incredibly powerful for this task. By utilizing functions like split_cols_by and setting show_colcounts = TRUE, you can easily build tables that break down age groups across multiple columns while displaying the total population count for each group. This layout framework is highly reusable and keeps your analysis code clean. For a deep dive into building these structures, refer to the vignettes/clinical_trials.Rmd file.
To ensure your tables are accessible and properly formatted for publication, always use descriptive variable labels instead of raw column names. This can be achieved using label-setting functions within your R environment before rendering.
When presenting these tables to clients or stakeholders, a well-defined generation pipeline ensures that your data flows smoothly from raw records to polished reports:

Frequently Asked Questions About RMD Age Tables
What is the RMD age table for 2026?
For the year 2026, the required beginning age for RMDs remains 73, as established by the SECURE Act 2.0. The IRS Uniform Lifetime Table is the primary table used to determine your life expectancy factor. For example, if you are 73 in 2026, your life expectancy factor is 26.5, which means you must withdraw approximately 3.77% of your prior year-end account balance.
What is the penalty for missing an RMD?
If you fail to withdraw your required minimum distribution by the deadline, the IRS imposes a 25% excise tax on the amount that was not distributed. However, if you correct this mistake and withdraw the required funds within a two-year correction window, the penalty is reduced to 10%. You must file IRS Form 5329 to address this penalty.
Can I use R Markdown to automate my clients’ RMD tracking?
Yes! By combining R Markdown with packages like reportRmd or DemographicTable, you can build reproducible, automated workflows. These scripts can pull the latest prior-year account balances, calculate ages dynamically, reference the official IRS divisor factors, and output clean, client-ready PDF or HTML reports.
Conclusion
Navigating the complexities of the rmd age table is vital for securing your financial future and avoiding costly IRS penalties. Whether you are calculating your own lifetime distributions using the Uniform Lifetime Table or managing inherited accounts with the Single Life Expectancy Table, staying proactive with your withdrawals is key to maintaining your financial security.
At ContentVibee, we are dedicated to providing clear, actionable financial and technology advice to help you manage your money with confidence.


