


Investment portfolio management software has become one of the most important tools for anyone who wants to stay in control of their money — without handing that control over to an algorithm or a high-fee advisor.
Here’s a quick look at the top categories of software, matched to different investor types:
| Software Category | Best For | Pricing Model |
|---|---|---|
| Retail Trackers | DIY individual investors | Monthly Subscription |
| Enterprise RIA Tools | Professional advisors | Custom/AUM-based |
| Institutional Suites | Family offices & large funds | Custom pricing |
| Private Equity Tools | Alternative asset managers | Custom pricing |
| Desktop Solutions | Security-focused users | One-time license |
| Analytical Engines | Backtesting & strategy | Tiered/Freemium |
The core problem most self-directed investors face isn’t a lack of options — it’s a lack of clarity.
Which platform is actually worth the cost? Which one keeps your data safe? And which one gives you real control instead of just the illusion of it?
This guide cuts through the noise. Below, you’ll find honest comparisons of the best tools available in 2026 — based on principles of Modern Portfolio Theory — broken down by user type, features, pricing, and security — so you can make a confident decision before committing to anything.
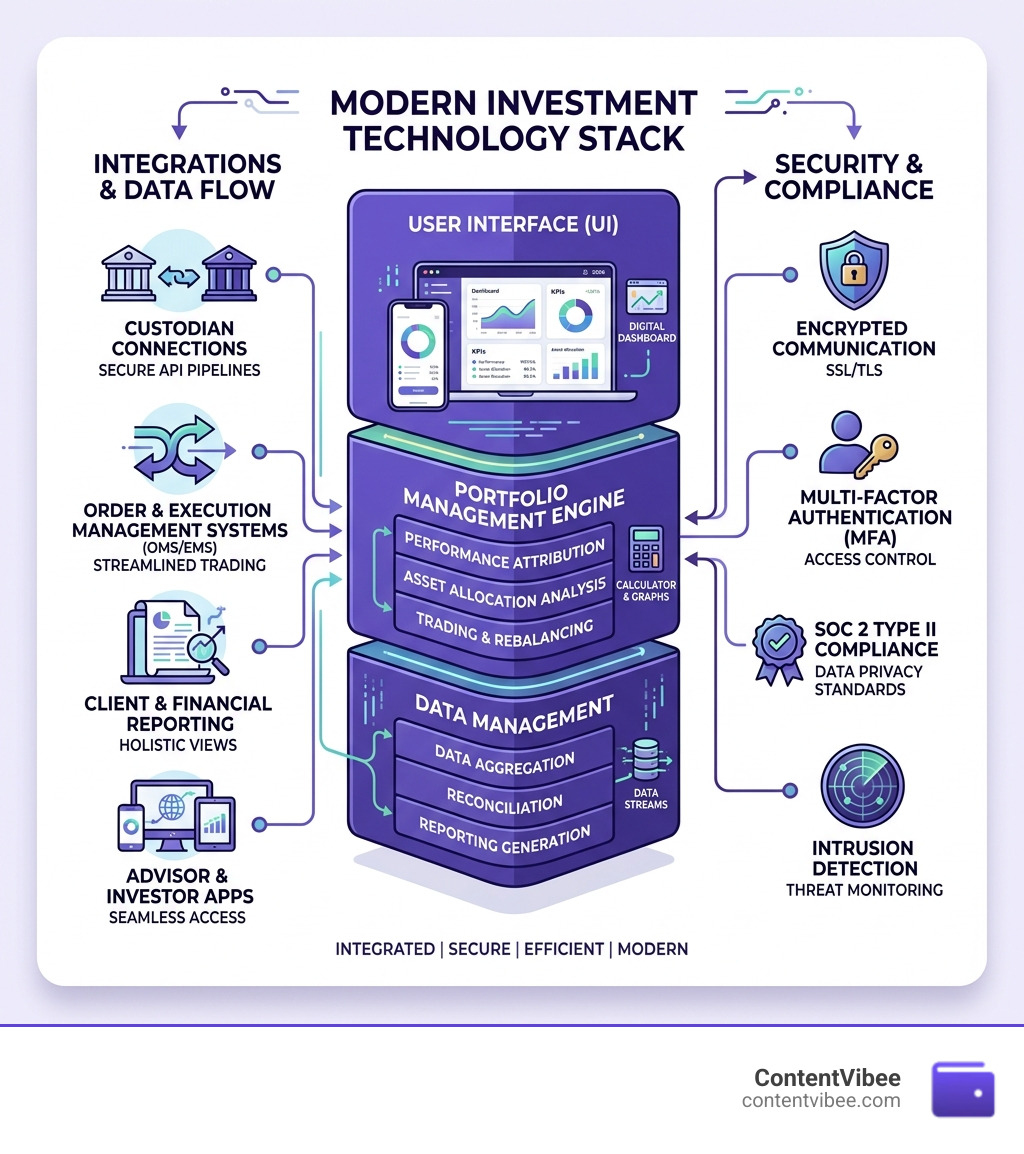
What is Investment Portfolio Management Software?
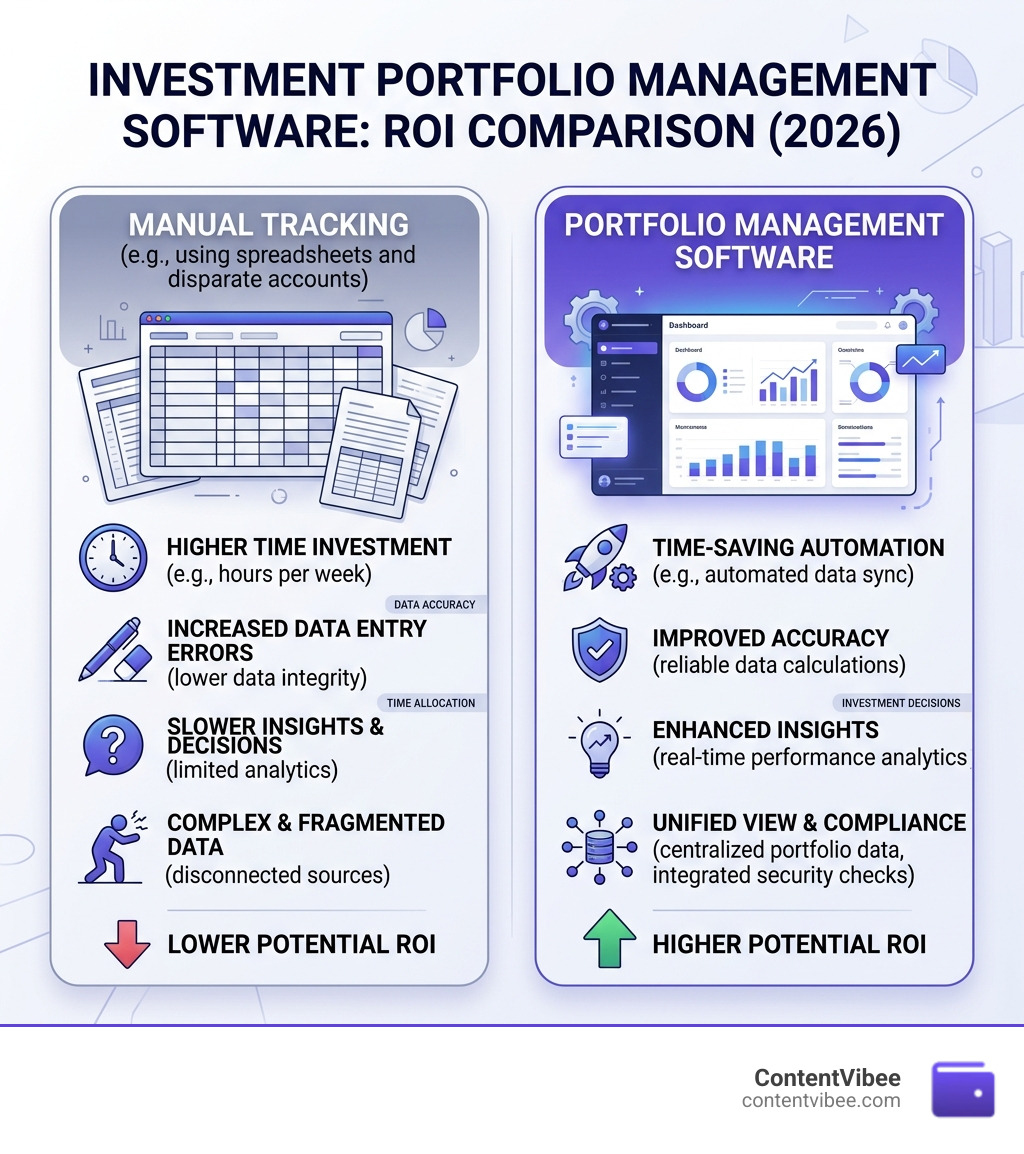
At its simplest, investment portfolio management software is a digital command center that allows you to view, analyze, and manage your financial assets in one place. Whether you are a DIY investor with three brokerage accounts or a professional advisor managing billions, these tools replace the “spreadsheet of doom” with real-time data and actionable insights.
The primary goal of this software is asset aggregation. Instead of logging into five different bank portals, the software uses secure APIs to pull your stocks, bonds, ETFs, and even alternative assets like private equity or crypto into a single dashboard. This provides a holistic view of your net worth and, more importantly, your true asset allocation.
Key functions include:
- Real-time Monitoring: Seeing price fluctuations as they happen across all holdings.
- Performance Attribution: Identifying exactly which sectors or specific stocks are driving your gains (or losses).
- Risk Assessment: Understanding how a market downturn might impact your specific mix of assets.
For professionals, these platforms often include complex accounting features. However, even for individuals, understanding Why Investment Accounting Software Cost/ is important, as the price often reflects the depth of data reconciliation and the accuracy of tax-lot tracking provided.
5 Essential Features of Investment Portfolio Management Software
When we evaluate any investment portfolio management software, we look for five “non-negotiable” features that separate the professional-grade tools from basic trackers.
- Automated Rebalancing: Markets move, and your 60/40 portfolio can quickly become a 70/30 portfolio. Top-tier software alerts you when your “drift” exceeds a certain percentage and helps you execute trades to get back on track.
- Tax-Loss Harvesting: This feature automatically identifies securities trading at a loss, allowing you to sell them to offset capital gains, potentially saving thousands in taxes.
- Multi-Custodian Integration: Whether you use major national brokerages or international trading platforms, the software must play nice with everyone.
- Performance Benchmarking: It’s easy to feel good about a 10% return until you realize the S&P 500 went up 15%. Good software compares your performance against relevant benchmarks.
- Risk Management Tools: Understanding your “downside” is just as important as tracking your “upside.”
Before diving in, it is worth asking Is Automated Portfolio Management Right For You/ to determine if you need a hands-off approach or a deep-dive analytical tool. Proper Investment Asset Allocation Strategy Risk Management/ is the foundation of long-term wealth.
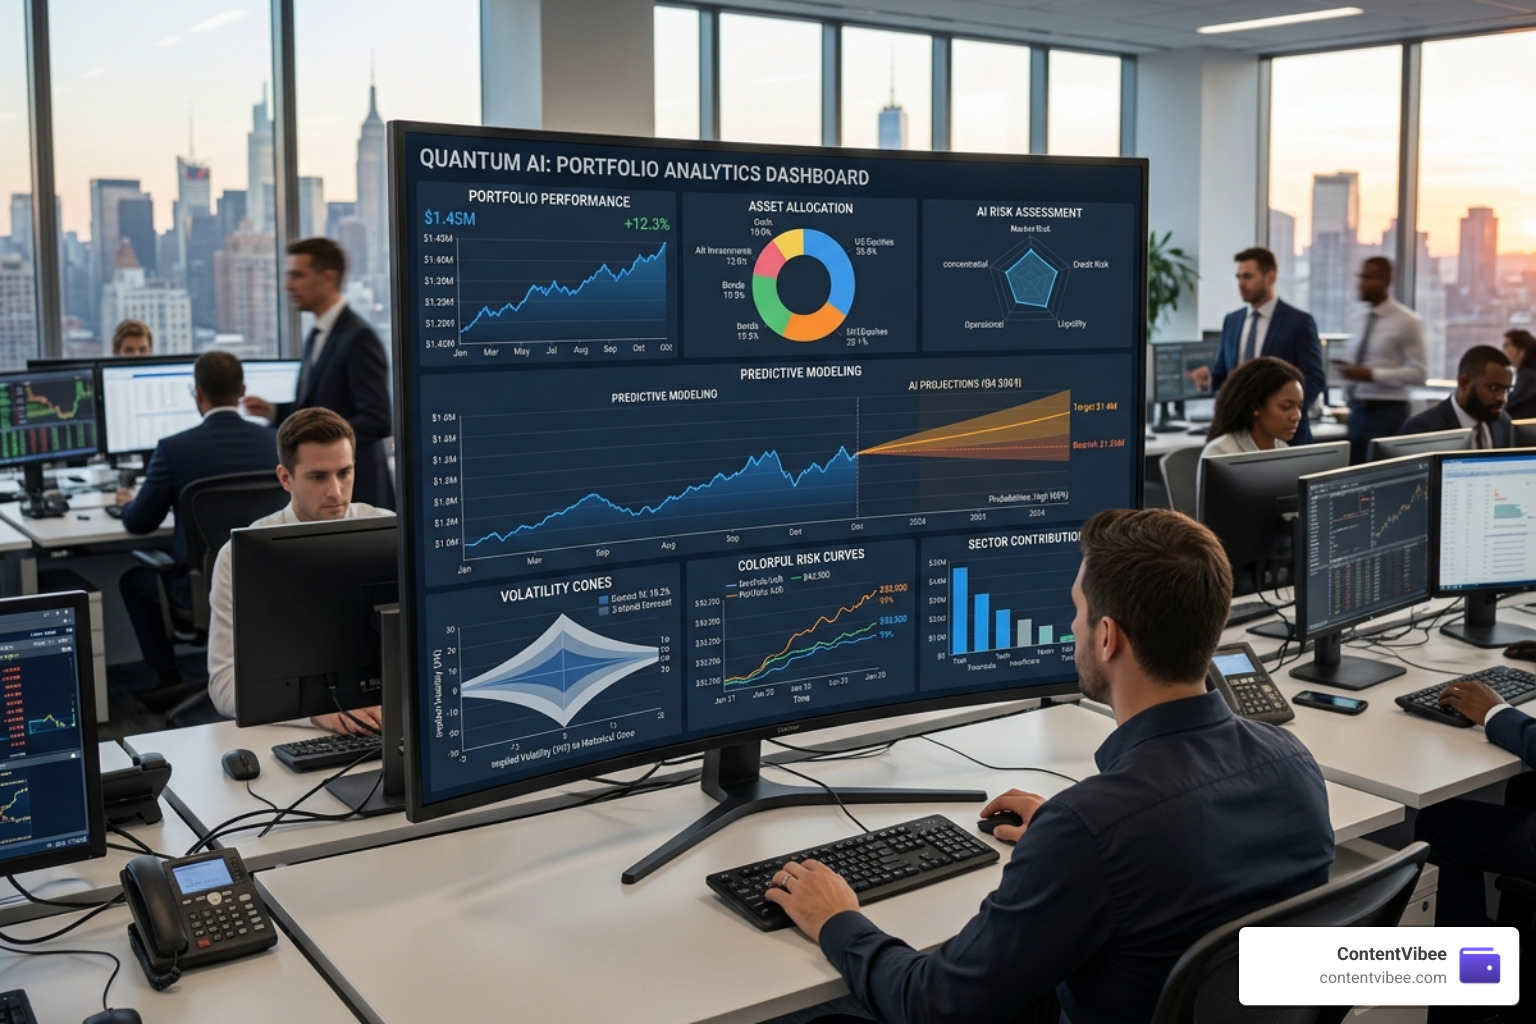
The Role of AI in Investment Portfolio Management Software
In 2026, AI has moved beyond a buzzword and into the core of portfolio management. Professional-grade platforms now feature AI assistants that allow you to ask natural language questions like, “What is driving the performance in my tech sector this quarter?” or “Break down my alternatives allocation by liquidity.”
AI is also being used for:
- Predictive Modeling: Using historical data and current market trends to simulate how your portfolio might react to a sudden interest rate hike.
- Pattern Identification: Modern tools help identify anomalies in data, which can serve as an early warning system for potential fraud or data entry errors.
- Automated Trade Recommendations: For CLO (Collateralized Loan Obligation) managers and private debt funds, AI can suggest specific trades to optimize portfolio compliance.
Protecting Your Investment Portfolio Management Software from Cyber Threats
As we aggregate more of our financial life into a single piece of software, we create a “honey pot” for hackers. Security is no longer an “extra”—it is the most critical feature.
When choosing a platform, we look for SOC2 compliance, which is the gold standard for service organization controls regarding data security and privacy. You should also ensure the software uses AES-256 data encryption and offers Multi-Factor Authentication (MFA).
For those who are extremely risk-averse, desktop-based solutions offer a unique advantage: they don’t store your data in the cloud. Your financial life stays on your hard drive, making it nearly impossible for a remote data breach to expose your holdings. Regardless of the platform, knowing the investment account hacking protection and financial data breach recovery steps USA is essential for any modern investor.
Security Protocols to Prevent Identity Theft and Financial Fraud
The rise of digital wealth management has unfortunately coincided with a rise in sophisticated financial crimes. In 2026, simply having a strong password isn’t enough to prevent identity theft or wire fraud.

If you find yourself a victim of a scam, time is your greatest enemy. Here are the critical protocols for recovery in the USA:
- Unauthorized Bank Transactions: If you see money leave your account without permission, you must act fast. Knowing unauthorized bank transaction how to dispute and recover money USA 2026 involves contacting your bank within 60 days to trigger Regulation E protections.
- Identity Theft and Credit Fraud: If someone opens a brokerage account in your name using your SSN, you need to know identity theft credit report fraud how to fix and protect your score USA. This includes placing a credit freeze and filing an Identity Theft Report via the FTC.
- Wire Transfer Fraud: This is often the most devastating. If you are a wire transfer fraud victim what to do and recovery options USA 2026, your first step is a “Financial Fraud Kill Chain” request through local law enforcement and the FBI’s IC3.
- Payment App Scams: For those using integrated payment tools, understanding zelle fraud transaction recovery steps and bank protection options USA is vital, as these transactions are often harder to reverse than credit card charges.
- Tax Scams: If a fraudster files a return in your name, follow the protocol for an irs tax refund scam how to claim loss and prevent identity theft USA by filing Form 14039.
For ongoing peace of mind, many investors are moving toward Real-Time Portfolio Security and Compliance Monitoring/ to catch red flags before they become financial disasters.
Comparing Pricing Models and Cost-Worthiness in 2026
How much should you pay for investment portfolio management software? The answer depends on your assets under management (AUM) and the complexity of your holdings.
| Model | Typical Cost | Best For |
|---|---|---|
| Flat Subscription | $10 – $50 / month | DIY Retail Investors |
| AUM-Based Fee | 0.01% – 0.05% of assets | Large Portfolios / RIAs |
| One-Time License | $200 – $500 | Desktop Software Users |
| Tiered Pricing | Scales with features | Growing Wealth Managers |
When evaluating cost, we look at “cost-worthiness.” For example, if a software costs $500 a year but its tax-loss harvesting tool saves you $2,000 in capital gains taxes, the software has a 400% ROI.
Understanding Why Investment Manager Software Fees/ vary so much can help you avoid overpaying for features you don’t use. Similarly, if you manage physical assets, you’ll want to look specifically at Why Real Estate Investment Software Pricing/ differs from traditional stock market tools.
For many, an automated platform provides the best balance. We recommend Understanding Automated Investment Platform Fees and Cost Worthiness/ before signing up for any “robo” or automated management service.
Frequently Asked Questions about Portfolio Software
How can I recover funds from unauthorized investment transactions?
In the USA, your primary protection is the Electronic Fund Transfer Act (EFTA). You should immediately notify your brokerage or bank. If the transaction involved a wire, contact the receiving bank to request a “hold” on the funds. In 2026, many brokerages offer “fraud guarantees,” but only if you have MFA enabled on your account.
What should I do if my SSN is used for fraudulent investment accounts?
This is a serious case of identity theft. You must file a report at IdentityTheft.gov, contact the fraud department of the brokerage where the account was opened, and place a “Fraud Alert” on your credit reports with Equifax, Experian, and TransUnion. This prevents the fraudster from opening further accounts.
How do I dispute wire transfer fraud in a brokerage account?
Wire transfers are generally considered “cash-equivalent” and are very difficult to reverse. However, you can initiate a “Recall Request” through your bank. If the fraud is caught within 24-48 hours, there is a slim chance the funds can be frozen before they are moved offshore.
What are the steps for identity theft credit report fraud recovery in the USA?
- Freeze your credit at all three bureaus.
- Review your reports for any accounts you don’t recognize.
- Dispute the fraudulent accounts in writing with the credit bureaus.
- File a police report to provide evidence to creditors that the debt is not yours.
Conclusion
At ContentVibee, we believe that the best investment portfolio management software is the one that empowers you to make better decisions while keeping your hard-earned wealth secure. Whether you choose a high-powered cloud platform or a security-first desktop solution, the key is to stay engaged with your data.
For those who want a more “hands-off” experience without sacrificing quality, the Autopilot app offers automated portfolio management specifically designed for self-directed investors. We specialize in comprehensive fee, risk, and management reviews to ensure that every tool in your financial stack is truly cost-worthy.
Don’t let your portfolio manage you. Take control of your financial future today.
More info about our investment categories

 A **robo advisor fees comparison** is the fastest way to see how much automated investing actually costs — and how much you could save over time. According to the [SEC Investor Bulletin](https://www.sec.gov/investor/alerts/ib_robo-advisers.pdf), understanding these costs is vital for long-term success. Here's a quick snapshot of the major fee tiers in 2026: | Service Tier | Management Fee | Avg. ETF Expense Ratio | Account Minimum | |---|---|---|---| | **Entry-Level Digital** | 0% (under $25K) / 0.35% above | ~0% | $0 | | **Standard Automated** | 0.25% | 0.03–0.12% | $500 | | **Low-Cost Index** | ~0.15–0.20% | Low (credits ER) | $100 | | **Cash-Heavy Model** | 0% | ~0.12% | $5,000 | | **Premium Hybrid** | 0.49–0.89% | Varies | $100,000 | **Bottom line:** Most robo-advisors charge between 0% and 0.35% per year in management fees, plus 0.03%–0.17% in underlying fund costs. That puts total all-in costs at roughly **$30–$60 per $10,000 invested annually** — far below a traditional human advisor's typical all-in cost of 1.50–1.75%. Fees are one of the few things in investing you can actually control. Markets go up and down. But a 1% fee quietly compounds against you for decades. Think about this: on a $100,000 portfolio growing at 7% annually with $12,000 in yearly contributions, a robo-advisor costing 0.30% leaves you with roughly **$575,000 after 20 years**. A human advisor charging 1.65% all-in? You'd end up closer to **$467,000** — a difference of over $110,000, simply from fees. That's not a small rounding error. *That's a decade of retirement income.* But not all robo-advisors are as cheap as their headline fees suggest. Some platforms advertise 0% management fees — yet their requirement to hold 6%–29% of your portfolio in cash creates an effective drag of around **0.74% per year**. Flat monthly fees sound modest, but on a $24,000 balance, a $5/month fee equals a 2.5% effective rate — *higher than most human advisors charge*. The goal of this guide is simple: cut through the marketing and show you the **real all-in cost** of today's top robo-advisors, broken down by account size, fee structure, and what you actually get for what you pay. 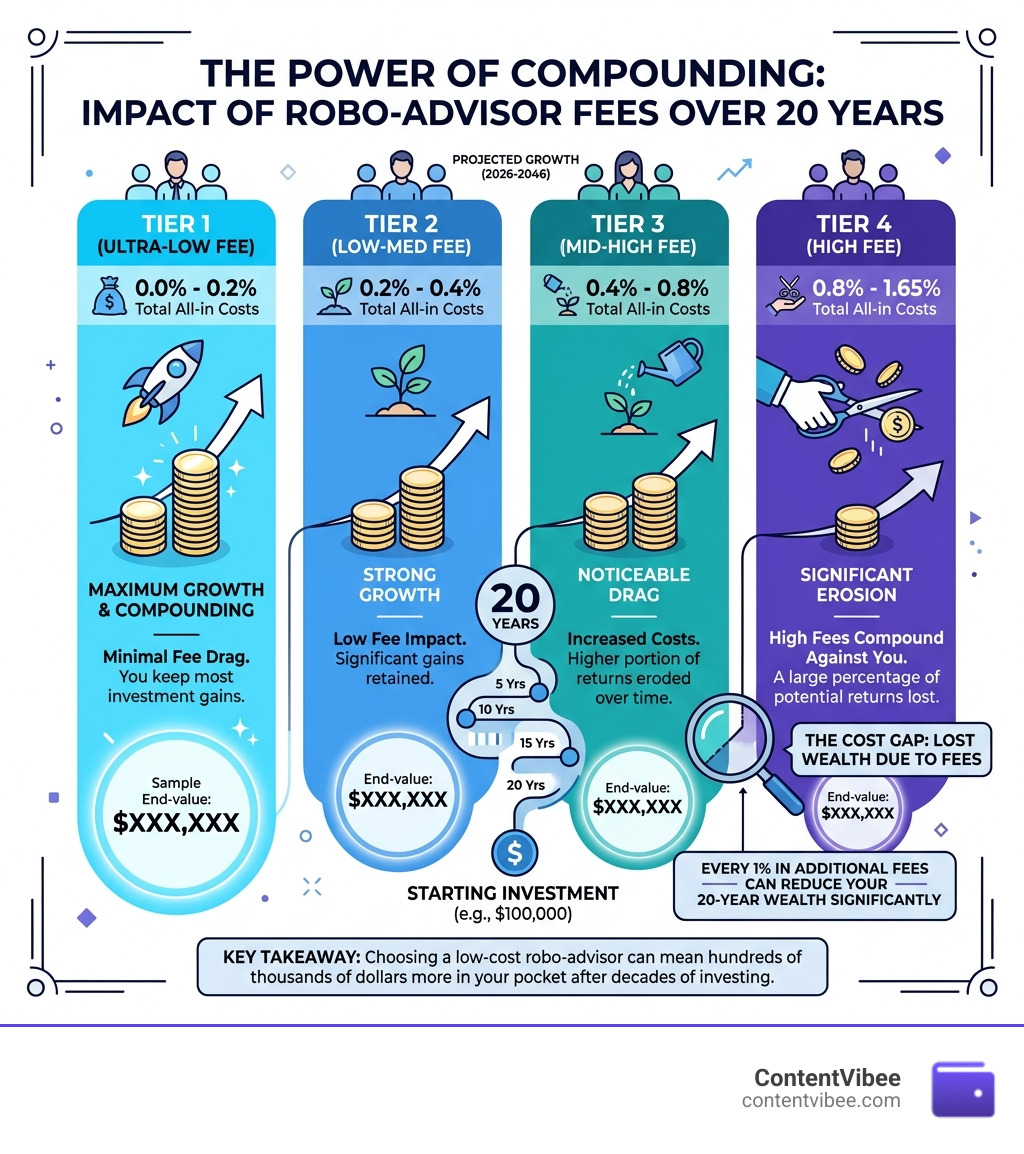 ## The True Cost of Automated Investing vs. Traditional Advice When we look at a **robo advisor fees comparison**, the most striking takeaway is the massive price gap between algorithms and humans. Traditional financial advisors often charge a standard 1.0% advisory fee. However, that is rarely the "out-the-door" price. Once you add in platform fees and the expense ratios of the funds they pick, the total cost often balloons to 1.50% or even 1.75%. In contrast, the median robo-advisor advisory fee sits at just 0.25%. Even when you include the underlying ETF expenses, the all-in cost typically stays between 0.30% and 0.60%. For a $50,000 portfolio, we are talking about $125 a year for a robo-advisor versus $750 or more for a human. Why the discrepancy? Robots don't have mahogany-filled offices or require expensive lunches. They use algorithms to build and manage portfolios based on your risk tolerance. While humans offer empathy and complex planning, many investors in the "accumulation phase" (building wealth under $250,000) simply don't need that level of overhead yet. You can learn more about these differences in our guide on Robo vs Human Financial Advisor: Cost Comparison 2026. However, it is vital to understand [What are Wealth Management Fees](https://contentvibee.com/what-are-wealth-management-fees/) before signing up. Fees aren't just a line item; they are a drag on your compounding interest. Over 20 or 30 years, that 1% difference can cost you hundreds of thousands of dollars in lost growth. ## Robo Advisor Fees Comparison: Analyzing All-In Costs for 2026 To perform a fair **robo advisor fees comparison**, we have to look at "all-in" costs. This means adding the management fee (what you pay the platform) to the ETF expense ratios (what you pay the fund managers like Vanguard or iShares). For a standard 60/40 stock-to-bond portfolio in April 2026, the costs look remarkably different depending on where you park your cash. | Provider Tier | Management Fee | ETF Expense Ratio | Total Annual Cost (per $10k) | |---|---|---|---| | Standard Digital | 0.25% | 0.08% | $33 | | Tiered Pricing | 0.35%* | 0.00% | $35* | | Low-Cost Leader | 0.15% | 0.05% | $20 | *\*Some tiered models are $0 for balances under $25,000, making them the price leader for beginners.* It is clear that Analyzing standard 0.25% fee structures is the baseline for the industry. If you are paying more than 0.40% all-in for a basic automated portfolio, you might be overpaying unless you are getting premium features like unlimited access to a Certified Financial Planner (CFP). ### How Account Size Impacts Your Robo Advisor Fees Comparison One of the biggest "gotchas" in the industry is how fees change as your balance grows. A "cheap" advisor at $5,000 might be the most expensive at $500,000. For example, some entry-level platforms are the undisputed king for small accounts. If you have $5,000, your management fee is $0. However, once you cross a certain threshold (often $25,000), they may charge 0.35% on the entire balance. Suddenly, a flat 0.25% fee looks a lot more attractive. On the flip side, some providers use flat monthly fees. A $5 per month fee is great if you have $20,000 (0.30% effective rate), but it is a disaster if you only have $1,000, as that $60 a year represents a 6% annual fee! We’ve seen that Tiered fee models for large balances are designed to reward loyalty, but you must do the math at your specific deposit level. ### The Role of ETF Expense Ratios in a Robo Advisor Fees Comparison Don't let a "0% management fee" headline fool you. Every robo-advisor builds your portfolio using Exchange Traded Funds (ETFs), and those funds have their own internal costs. A robo-advisor might claim to be free but then stuff your portfolio with "house" funds that have higher expense ratios. This is why [Why Brokerage Firm Investment Fees and Account Costs Matter](https://contentvibee.com/why-brokerage-firm-investment-fees-and-account/) so much. Some providers are cheaper overall because they credit the fund expenses back against their advisory fee, ensuring you aren't "double-dipped." In 2026, the gold standard for a blended ETF expense ratio is between 0.05% and 0.15%. If your robo-advisor's underlying funds cost more than 0.20%, they are likely using niche or actively managed funds that may not be necessary for a long-term index strategy. ## Protecting Your Wealth: Security Risks and Fraud Recovery in Automated Investing  As we move our wealth into automated systems, the conversation shouldn't just be about a **robo advisor fees comparison**; it must also cover security. While robos are generally safer than keeping money under a mattress ([SIPC insurance](https://www.sipc.org/for-investors/what-sipc-protects) covers up to $500,000 in brokerage insolvency), digital platforms are targets for identity theft and SSN misuse. A low fee is worthless if a hacker drains your account through an unauthorized wire transfer. We believe that Robo-Advisor Fees: Comparing Costs and Security Features should be evaluated together. Look for platforms that offer two-factor authentication (2FA), biometric logins, and "withdrawal locks" that require a secondary approval before money leaves the account. ### Unauthorized bank transaction how to dispute and recover money USA 2026 If you discover an unauthorized transaction in your investment account, time is your greatest enemy. In the USA, the Electronic Fund Transfer Act (Regulation E) provides protections, but they are stricter for investment accounts than for standard checking accounts. If you are a wire transfer fraud victim, knowing what to do and recovery options in the USA 2026 is critical. You must notify the institution within two business days of learning about the fraud to limit your liability to $50. If you wait longer, that liability can jump to $500 or even the full amount of the loss. **Steps to recover funds:** 1. **Freeze the account:** Immediately stop all outgoing transfers. 2. **File a formal dispute:** Do this in writing, not just over the phone. 3. **Police Report:** Essential for identity theft claims. 4. **FTC Affidavit:** Use IdentityTheft.gov to create an official record. ### Identity theft credit report fraud how to fix and protect your score USA Identity theft doesn't just put your cash at risk; it can wreck your credit score, making it impossible to get a mortgage or car loan. If someone uses your SSN to open a fraudulent brokerage account or credit line, you need to act fast. Learning how to fix credit after identity theft involves placing a "Security Freeze" on your reports at Equifax, Experian, and TransUnion. This prevents anyone from opening new accounts in your name. In 2026, many robo-advisors are integrating credit monitoring directly into their apps to help you spot these red flags early. For more detailed steps, check out identity theft credit report fraud: how to fix and protect your score in the USA. ## Advanced Features That Justify Higher Management Fees Is it ever worth paying a higher fee? Sometimes, yes. While a **robo advisor fees comparison** helps you find the lowest price, the "cheapest" option isn't always the one that makes you the most money. The secret sauce is often **Tax-Loss Harvesting (TLH)**. This is a strategy where the algorithm sells "loser" investments to offset capital gains and up to $3,000 of ordinary income on your taxes. Leading automated platforms are pioneers here. Studies suggest TLH can add 0.5% to 1.5% in "tax alpha" (annualized after-tax returns). If a robo-advisor charges 0.25% but saves you 1.0% on your taxes, the service effectively pays for itself. You should ask yourself [Is Automated Portfolio Management Right for You](https://contentvibee.com/is-automated-portfolio-management-right-for-you/) based on whether you have a taxable brokerage account. If you are only investing in a Roth IRA, tax-loss harvesting provides zero benefit, and you should stick to the lowest-fee provider possible. ### Hidden Costs and Cash Drag in a Robo Advisor Fees Comparison We have to talk about the elephant in the room: **Cash Drag**. Some "free" robo-advisors make their money by keeping a portion of your portfolio in cash. Certain models, for instance, require a cash allocation of 6% to 29%. While they don't charge a management fee, that cash is often earning a lower interest rate than if it were invested in the market. In a bull market, this "drag" can cost you significantly more than a 0.25% fee would. If the market returns 10% and 10% of your money is sitting in cash earning 4%, you've just lost 0.60% in potential gains. Evaluating automated management cost-worthiness requires looking at the "opportunity cost" of this uninvested capital. 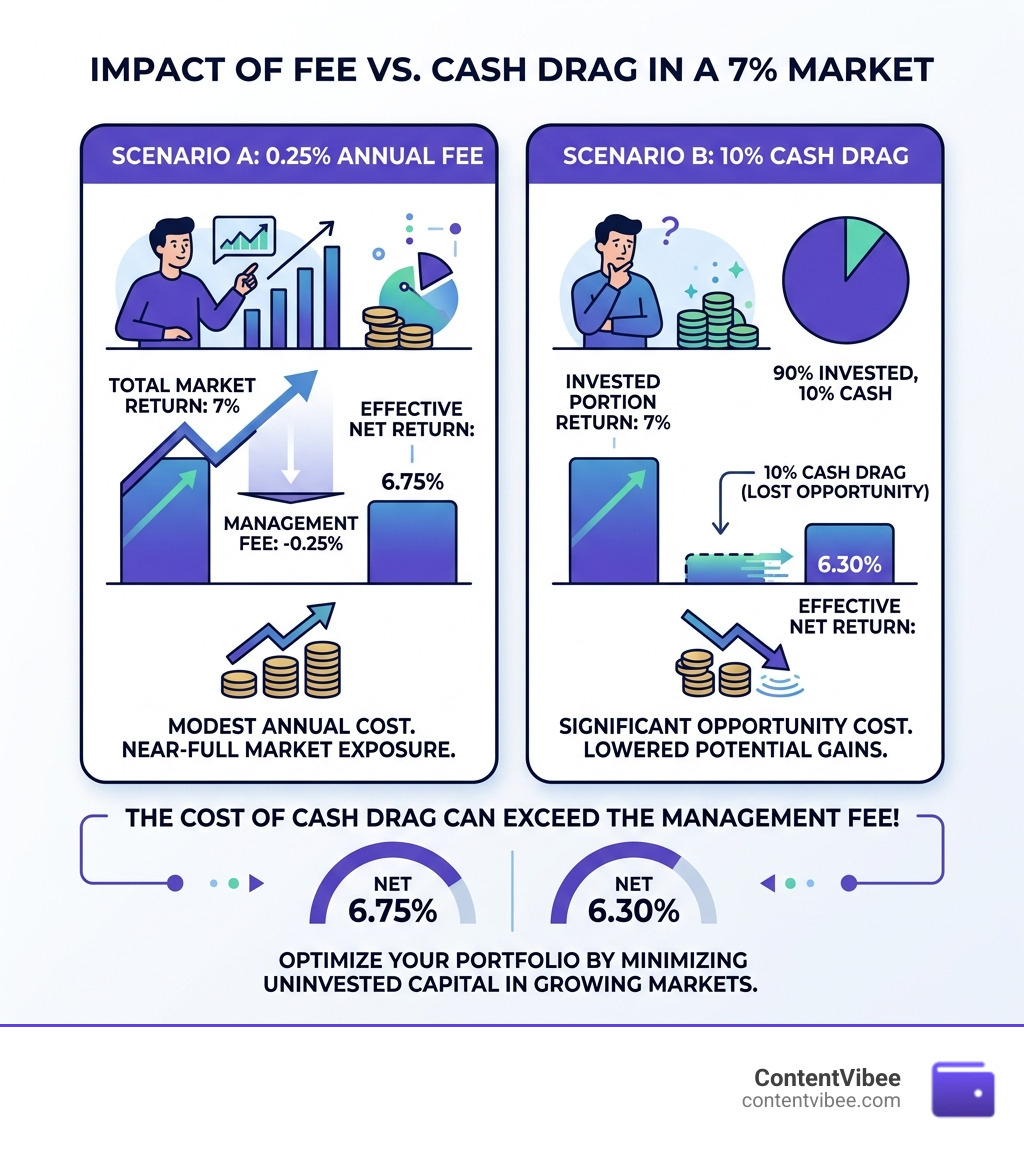 ## Frequently Asked Questions about Robo-Advisor Costs ### Which robo-advisor has the lowest all-in fees in 2026? For portfolios under $25,000, entry-level platforms with $0 management fees and zero-expense-ratio funds are generally the cheapest. For larger portfolios, providers that credit fund expenses back against their advisory fee often win on a total cost basis (roughly 0.20% all-in). ### Is a robo-advisor worth the fee for a small portfolio? Yes, but be careful with flat fees. If you have $1,000, avoid any provider charging a monthly dollar amount. Stick to percentage-based fees or $0-minimum providers. The automation of rebalancing alone is usually worth the 0.25% fee for beginners. ### How do hidden cash drags impact my total returns? Cash drag acts like an invisible fee. If a provider keeps 10% of your money in cash during a year where the market is up 15%, that drag "costs" you 1.5% in lost returns. This is often much more expensive than paying a transparent 0.25% advisory fee. ## Conclusion A thorough **robo advisor fees comparison** proves that you don't need to be a millionaire to get professional-grade portfolio management. By choosing an automated partner, you can slash your investment costs by 70% or more compared to traditional human advisors. However, the "cheapest" headline isn't always the best deal. You have to account for account minimums, ETF expenses, and the impact of cash drag. At ContentVibee, our **Autopilot** tool is designed to help you navigate these waters. We offer comprehensive fee, risk, and management reviews to evaluate the true cost-worthiness of your investments. Don't let high fees erode your future. Whether you are just starting with $500 or managing a $500,000 retirement nest egg, small changes in your fee structure today lead to massive differences tomorrow. [Explore our full range of financial security and investment guides](https://contentvibee.com/categories/) to keep your wealth growing and protected.](https://contentvibee.com/wp-content/uploads/2026/04/image-65-400x225.jpeg)
