

Two Tools, One Name: What an Automated QCD Contribution Calculator Actually Does
If you’ve landed here searching for an automated QCD contribution calculator, here’s the quick answer — there are actually two very different tools this term refers to:
Top QCD Calculator Tools by Type:
| What You Need | Tool Type | Best For |
|---|---|---|
| Reduce IRA taxes, satisfy RMDs | Financial QCD calculator | Retirees aged 70½+ |
| Particle physics cross-sections | Physics QCD calculator (e.g., HighTEA) | Physicists and researchers |
If you want to calculate a Qualified Charitable Distribution from your IRA:
- You need a financial QCD calculator
- These tools estimate how much you can donate tax-free (up to $111,000 per year in 2026)
- They help you satisfy Required Minimum Distributions without raising your taxable income
If you need quantum chromodynamics calculations for collider physics:
- You need a physics automation tool like HighTEA or WHIZARD
- These handle NLO/NNLO corrections, matrix elements, and PDF uncertainties
Most retirees searching this term want the financial version. This guide covers both — but if tax savings is your goal, you’re in the right place.
The word “QCD” pulls double duty in ways that can genuinely confuse people. In personal finance, QCD stands for Qualified Charitable Distribution — a powerful tax strategy for retirees who are required to take money out of their IRAs each year. In particle physics, QCD stands for Quantum Chromodynamics — the theory of the strong nuclear force, and calculating its effects requires some of the most demanding computing on the planet.
Both fields have developed automated tools to handle their respective calculations. And both matter enormously to the people who need them.
For a retiree worried about a surprise tax bill, an automated financial QCD calculator can show exactly how much giving directly from an IRA saves compared to a standard cash donation. For a physicist modeling proton collisions at the Large Hadron Collider, an automated QCD calculator can compress what used to take tens of millions of CPU hours into results delivered in minutes.
This guide explains both — clearly, without jargon — so you can find and use the right tool for your situation.
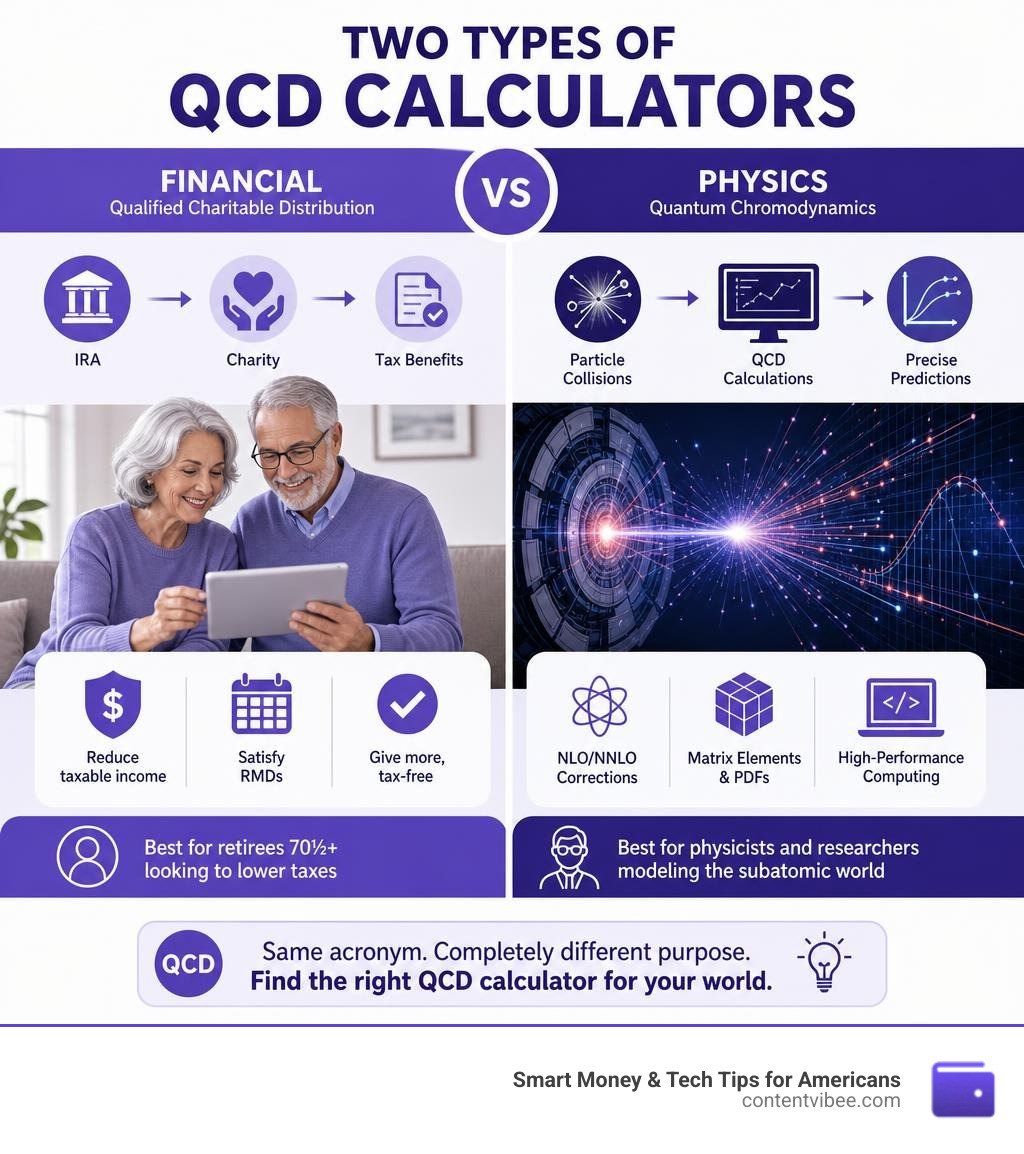
Understanding the Dual Meanings of QCD Calculators
To understand why these two fields share an acronym, we have to look at what each calculator is trying to solve. Both tools are designed to take highly complex, multi-variable inputs and output a precise, actionable number. However, one protects your hard-earned retirement nest egg from Uncle Sam, while the other prevents theoretical physics models from collapsing under the weight of subatomic reality.
Here is a quick look at how these two worlds compare:
| Feature | Financial QCD Calculator | Physics QCD Calculator |
|---|---|---|
| Primary Goal | Minimize tax liability on IRA withdrawals | Compute high-energy particle collision probabilities |
| Target Audience | Retirees, financial planners, and donors | Particle physicists and collider researchers |
| Key Inputs | Age, IRA balance, tax bracket, desired donation | Kinematic variables, scale parameters, PDF sets |
| Key Output | Tax savings and remaining RMD | Cross-sections and differential distributions |
| Typical Run Time | Instantaneous (less than a second) | Seconds to hours (using precomputed databases) |
What is a Qualified Charitable Distribution (QCD)?
For retirees, a Qualified Charitable Distribution is one of the absolute best tax-saving strategies available. Once you reach age 70½, the IRS allows you to transfer up to $111,000 per year (as indexed for inflation in 2026) directly from your Traditional IRA to an eligible 501(c)(3) public charity.
The beauty of this transaction is in its tax treatment. Normally, any distribution from a Traditional IRA is treated as taxable income. But when you execute a proper QCD, that money is excluded from your Adjusted Gross Income (AGI).
Even better, once you hit your Required Minimum Distribution (RMD) age—which is 73 under current SECURE 2.0 rules—your QCD counts toward satisfying that mandatory withdrawal. By keeping this money off your tax return, you can bypass high tax brackets, avoid Medicare premium surcharges, and keep your Social Security benefits from being taxed.
To see how these rules apply to your accounts and evaluate custodian-specific guidelines, you can review the Qualified Charitable Distributions (QCDs) | planning your IRA … resource. To calculate the specific tax benefits of your giving, tools like the Charitable Giving Tax Savings Calculator or the Charitable Tax Benefit Calculator can give you a personalized estimate of your savings.
What is a Quantum Chromodynamics (QCD) Calculator?
In the physics universe, QCD is the study of the strong force—the fundamental interaction that binds quarks and gluons together to form protons and neutrons. When physicists smash particles together at high-energy colliders like the Large Hadron Collider (LHC), they need to predict the outcomes of these collisions with extreme precision.
These predictions require calculating the “cross-section” of various processes, which tells researchers how often a specific event (like creating a Higgs boson) will occur. Because the strong force is incredibly complex, calculating these interactions requires perturbative QCD corrections.
Without automated tools, researchers would have to manually compute thousands of complex mathematical equations for every single process. Modern frameworks automate these calculations, matching high-level theoretical predictions with actual collider data. For example, researchers use these frameworks to compute the [2009.11437] Fiducial 𝑞_𝑇 resummation of color-singlet processes at N3LL+NNLO to understand the transverse momentum of color-singlet particles with unmatched accuracy.
The Technical Mechanics of an Automated QCD contribution calculator
If you are looking at the scientific side, an Automated QCD contribution calculator is a marvel of software engineering. It translates the abstract laws of quantum field theory into numerical predictions that can be compared directly with experimental data.
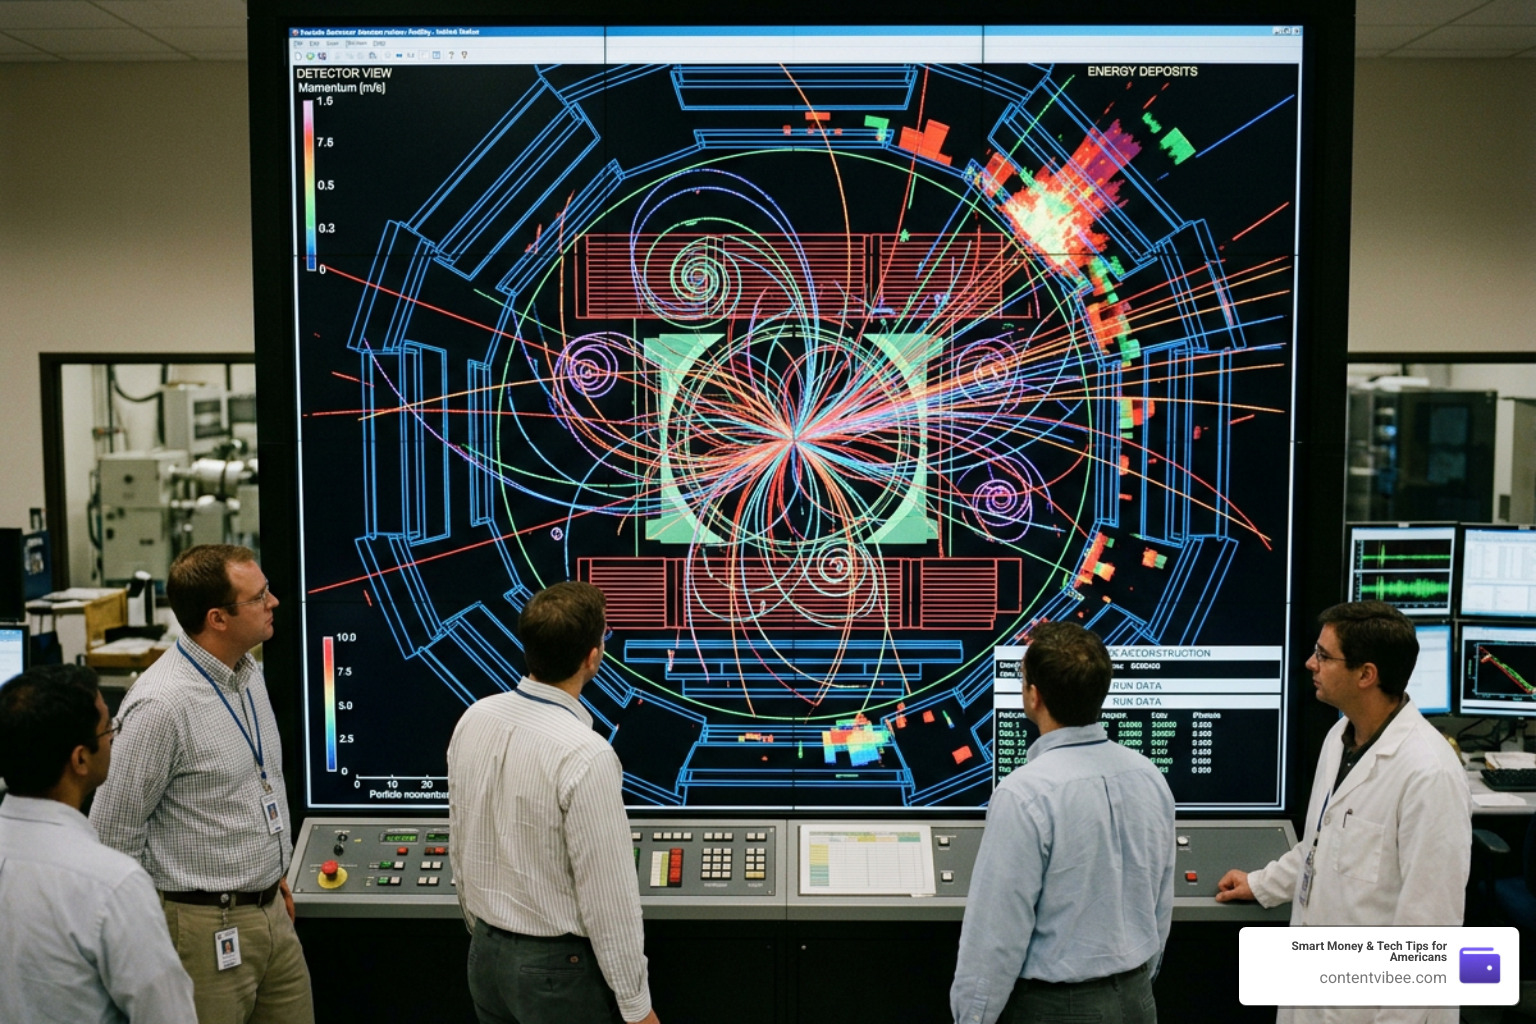
How the Physics Calculator Handles Higher-Order Corrections
To get precise predictions, physicists cannot rely on simple tree-level calculations (known as Leading Order, or LO). They must calculate Next-to-Leading Order (NLO) and Next-to-Next-to-Leading Order (NNLO) corrections.
Automation at NLO and NNLO is incredibly difficult because of the way quantum mechanics behaves. When you calculate higher-order corrections, you must account for:
- Real Emissions: Particles radiating extra gluons or quarks during the collision.
- Virtual Corrections: Virtual particles appearing and disappearing in “loops” within the quantum process.
- Infrared (IR) Divergences: Mathematical infinities that appear when radiated gluons become very soft or collinear with the parent particle.
To make these calculations solvable, automated calculators use advanced “subtraction schemes” (like FKS or dipole subtraction) to isolate and cancel out these infinities before performing numerical integration. For a deeper dive into how software packages automate these processes across different colliders, you can read the paper on [2210.07157] Automated NLO SM corrections for all colliders .
To see how these matrix elements are implemented programmatically, look at the source code in src/higgs/exactqcdcorrections/nloexactmatrix_elements.cpp at master · dulatf/ihixs . For developers looking to integrate these calculations into their own Python-based pipelines, the ecavan/FeynmanAPI repository provides a unified toolset for rendering diagrams and computing amplitudes.
Key Technical Components of Physics QCD Automation
A fully automated physics QCD calculator relies on several core components:
- Matrix Element Generators: Automated tools that write the symbolic quantum amplitudes for a given process.
- Phase-Space Integrators: Advanced Monte Carlo algorithms that integrate these highly complex functions over the multi-dimensional space of the final-state particles.
- Parton Distribution Functions (PDFs): Databases that describe the internal structure of the colliding protons, which are inherently non-perturbative and must be extracted from global data fit groups.
- Scale Variation Managers: Systems that automatically vary the renormalization and factorization scales to estimate the theoretical uncertainty of the calculation.
Because running these calculations from scratch can take millions of CPU hours, modern platforms like HighTEA (High Energy Theory Event Analyser) have introduced a new paradigm. Instead of forcing users to run massive calculations on their own local grids, HighTEA precomputes highly complex NNLO events and stores them in massive databases (ranging from hundreds of gigabytes to several terabytes per process). Users can then query these databases via web interfaces or APIs to get precise physical predictions in minutes. You can explore this framework further in the paper on HighTEA: high energy theory event analyser – IOPscience .
Maximizing Tax Savings with Financial QCD Calculators
Now, let’s step back into the financial realm, where “QCD” means keeping more of your hard-earned retirement savings. An automated financial QCD calculator is a simple yet powerful tool that helps you plan your giving to maximize your tax savings.
How an Automated QCD contribution calculator Helps Retirees
When you retire, tax planning changes completely. Instead of trying to earn more income, your goal is to manage how and when you withdraw your money to keep your taxable income as low as possible.
This is where an Automated QCD contribution calculator becomes essential. If you simply withdraw money from your Traditional IRA to write a check to your favorite charity, that withdrawal is added to your Adjusted Gross Income (AGI). Even if you claim an itemized deduction for the donation, your higher AGI can trigger several expensive tax traps:
- The Social Security Tax Trap: Up to 85% of your Social Security benefits can become taxable if your income exceeds certain thresholds.
- The Medicare IRMAA Surcharge: If your AGI is even one dollar over specific limits, your Medicare Part B and Part D premiums can spike significantly.
- Deduction Phaseouts: High AGI can limit other tax breaks and credits you might otherwise receive.
By using an automated calculator, you can input your expected RMD, your tax bracket, and your giving goals. The calculator will show you how much of your RMD should be processed as a direct QCD transfer to keep your AGI below these costly thresholds.
For married couples, coordinating these distributions alongside other retirement benefits can get complicated. To make sure you are optimizing your entire household’s income, it helps to combine your charitable planning with tools like the Do The Math Top Social Security Calculators For Married Couples to build a complete tax-minimization strategy.
Rules and Limits for Financial QCDs in 2026
To make sure your QCD is fully tax-free, you must follow the IRS rules exactly. An automated calculator can help you stay within these boundaries, but you should keep these key 2026 guidelines in mind:
- The Age Requirement: You must be at least 70½ years old on the exact day the distribution is made. Being “70½ in the calendar year” is not enough; the transfer must occur on or after your half-birthday.
- The Annual Cap: For 2026, the maximum QCD limit is $111,000 per individual. If you are married, you and your spouse can each contribute up to $111,000 from your respective IRAs, for a total of $222,000.
- Direct Transfer Only: The check or wire transfer must go directly from your IRA custodian to the qualified charity. If the money is paid to you first, it counts as a taxable distribution, and you lose the tax benefit.
- The RMD Age Gap: Under the SECURE 2.0 Act, the age to begin taking Required Minimum Distributions is 73. This means you can start making tax-free QCDs at 70½, lowering your total IRA balance and reducing the size of your mandatory RMDs when you turn 73.
To see how these withdrawals impact your overall retirement income, you can estimate your baseline retirement benefits using our Social Security Calculator Estimate Your Benefit Amount.
Frequently Asked Questions about QCD Calculators
Navigating these topics can bring up a lot of questions. Here are the answers to the most common queries about both financial and physical QCD calculations.
Can I use a QCD calculator for inherited IRAs?
Yes, you can! If you inherit a Traditional IRA, you are generally required to withdraw the entire balance of the account within 10 years under the IRS “10-year rule.” These mandatory withdrawals are fully taxable and can easily push you into a much higher tax bracket during your peak earning years.
Fortunately, if you are at least 70½ years old at the time of the distribution, you can make QCDs directly from an inherited IRA. An automated financial calculator can help you map out your mandatory withdrawals over that 10-year window, showing you how to use QCDs to satisfy your withdrawal requirements completely tax-free.
When planning these distributions, it is also highly beneficial to look at how your overall retirement and spousal benefits interact. You can model these scenarios using our Tools/Finance Calculator/Social Security Spousal Benefit Calculator to keep your household’s lifetime tax burden as low as possible.
What are the computational limits of a physics-based Automated QCD contribution calculator?
While financial calculators run instantly, physics-based calculators face massive computational challenges.
A high-precision NNLO calculation can easily require tens of millions of CPU hours to resolve the complex quantum loops and real emission corrections. Even a relatively straightforward, standard NNLO calculation typically takes around 50,000 CPU hours.
Because of this immense computational cost, public automated tools have some limitations:
- Fixed Statistics: Tools like HighTEA rely on precomputed event samples. If you need extremely high statistics for a highly specific corner of phase space, you may run into statistical limitations.
- Pre-defined Cuts: You can only apply user-level kinematic cuts that are more restrictive than the original generation-level cuts used to create the database.
- Process Availability: Only pre-implemented processes (like top-quark pair production or vector boson production) can be calculated instantly.
To explore other specialized calculation tools and physics engines, you can check out our comprehensive directory of technical tools.
How do QCD calculators integrate with broader financial planning?
A financial QCD calculator should never be used in isolation. It is one piece of a much larger puzzle that includes your tax-bracket management, your investment strategy, and your long-term retirement roadmap.
For example, when you use a QCD to lower your AGI, you might free up room in your tax bracket to perform a Roth IRA conversion at a lower tax rate. Alternatively, keeping your AGI low can prevent your Social Security benefits from being taxed, giving you more flexible cash flow.
To see how all of these pieces fit together into a clear, stress-free retirement plan, you can compare different retirement planning tools using our guide to the Best Free Social Security Calculator Options Your No Cost Retirement Roadmap.
Conclusion
Whether you are trying to solve the mysteries of the strong nuclear force or simply trying to keep your hard-earned retirement savings out of the hands of the IRS, automated QCD calculators are incredibly valuable tools.
At ContentVibee, we believe that making smart money decisions should be simple, clear, and highly actionable. By using an automated financial QCD calculator, you can take the guesswork out of your charitable giving, protect your retirement income from surprise tax bills, and make a meaningful impact on the causes you care about most.
If you want to automate even more of your financial life—from portfolio rebalancing to tax-loss harvesting—you might want to explore how modern technology can handle the heavy lifting for you. Check out our guide on What is a Robo-Advisor? to see if automated investing is the right fit for your retirement journey.


