

What You’ll Actually Pay on a $15,000 Car Loan
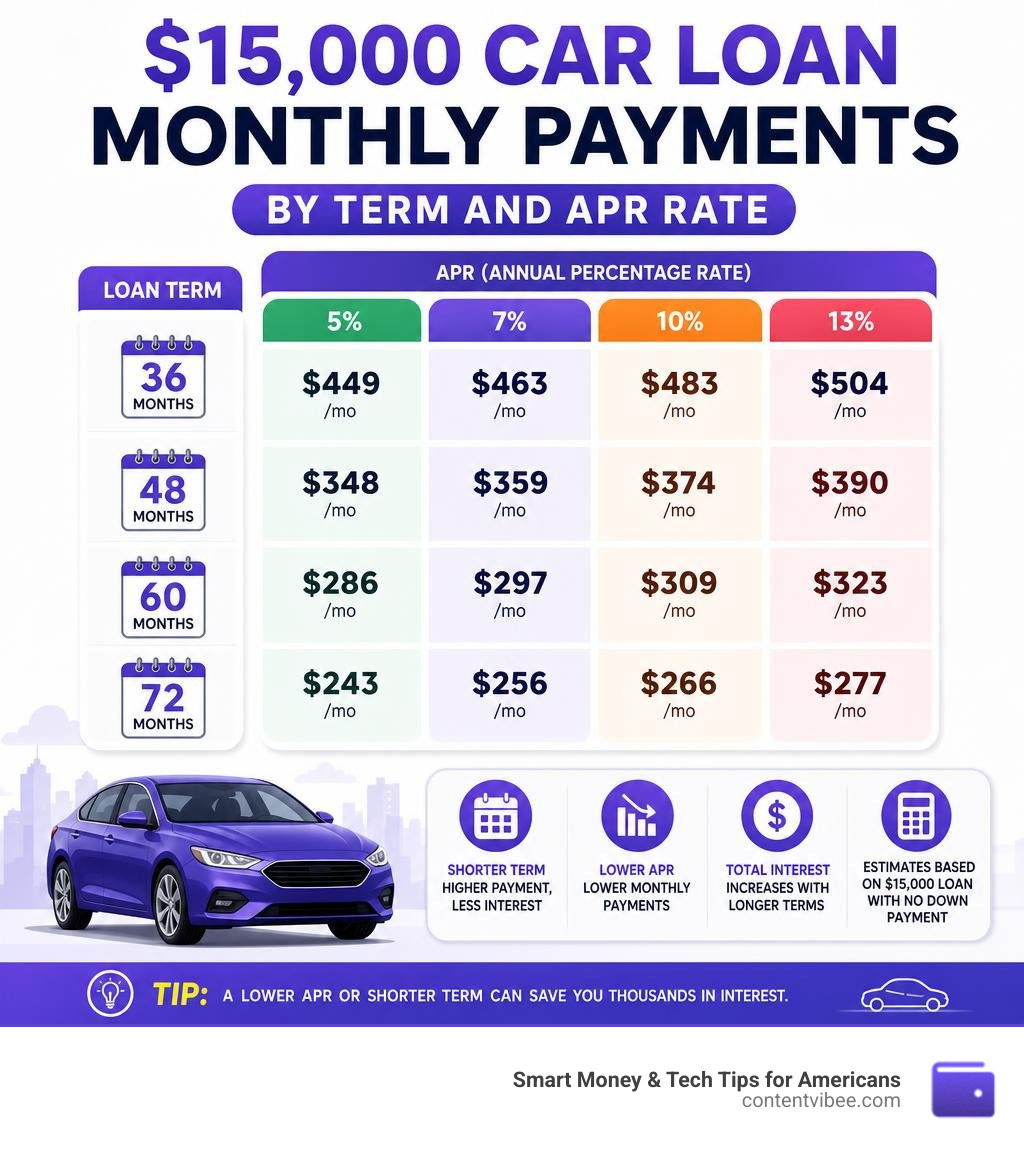
The monthly payment on a $15,000 car loan depends on three things: your interest rate (APR), your loan term, and your down payment. Here’s a quick snapshot at a common APR of around 7% so you can get your bearings fast:
| Loan Term | Monthly Payment | Total Interest Paid |
|---|---|---|
| 36 months | ~$463 | ~$668 |
| 48 months | ~$359 | ~$909 |
| 60 months | ~$297 | ~$1,782 |
| 72 months | ~$256 | ~$2,432 |
Estimates based on $15,000 loan at approximately 7% APR with no down payment.
Shorter terms mean higher monthly payments but less total interest. Longer terms feel easier on your wallet each month — but you pay more in the long run.
That tradeoff is at the heart of every car financing decision. And right now, in July 2026, average auto loan rates are sitting higher than many buyers expected — around 13.80% for new cars and 16.20% for used cars across all credit tiers. Borrowers with excellent credit can do much better, but those with fair or poor credit could pay significantly more.
The good news? A $15,000 loan is on the smaller end of the auto financing spectrum. (The average new car loan is nearly $28,657.) That means your total interest exposure is manageable — if you approach it wisely.
This guide walks you through everything that affects your payment: loan terms, credit scores, down payments, hidden costs, and strategies to pay less overall.
Key monthly payment on $15000 car loan vocabulary:
Introduction
Buying a car is one of those major life milestones that can feel both incredibly exciting and slightly terrifying. You find the perfect ride, imagine yourself cruising down the highway with your favorite playlist blasting, and then—bam!—the reality of financing hits you. If you are eyeing a vehicle in the $15,000 range, you are in a sweet spot. In today’s market, $15,000 can secure a reliable, high-quality used vehicle or serve as a sensible remaining balance after a solid down payment on a newer model.
However, before you sign on the dotted line, you must understand exactly how that $15,000 translates into a recurring line item in your monthly budget. We want to help you demystify this process. By looking at how loan terms, interest rates, credit scores, and down payments interact, we will help you map out a clear path to car ownership. Our goal is to ensure you drive off the lot with a smile on your face, rather than a knot in your stomach about your next payment.
What is the Monthly Payment on $15000 Car Loan?
When you ask, “What is the monthly payment on a $15,000 car loan?”, the honest answer is: it depends. The final number is dictated by the interaction of your loan principal, the interest rate (APR) you qualify for, and the duration of the loan term.
To give you a baseline, let’s look at how the loan term impacts your payments. Auto loans are typically structured in 12-month increments, ranging from 36 months (3 years) up to 84 months (7 years). Historically, under ideal or promotional conditions, a borrower with stellar credit might have secured an APR of 2.89% on a $15,000 loan, resulting in a highly affordable monthly payment of $331.29 for 48 months.
However, in the current 2026 economic landscape, typical rates are higher. Let’s look at a realistic comparison across different terms using a moderate, competitive interest rate of 8% APR to see how stretching your loan affects your wallet:
| Loan Term | Monthly Payment | Total Interest Paid | Total Cost of Loan |
|---|---|---|---|
| 36 Months | $470.05 | $1,921.80 | $16,921.80 |
| 48 Months | $366.19 | $2,577.12 | $17,577.12 |
| 60 Months | $304.15 | $3,249.00 | $18,249.00 |
| 72 Months | $263.02 | $3,937.44 | $18,937.44 |
| 84 Months | $233.84 | $4,642.56 | $19,642.56 |
As you can see, extending your loan to 72 or 84 months makes the monthly commitment look incredibly attractive. Paying $233 a month feels much easier than parting with $470. But look closely at the “Total Interest Paid” column. By choosing an 84-month term over a 36-month term, you pay an extra $2,720 in interest alone! That is money that could have gone into your savings, a vacation, or retirement.
Additionally, cars are depreciating assets. If you stretch a loan out to 72 or 84 months on a used car, you run a high risk of becoming “upside-down” or having negative equity. This means you owe more on the loan than the car is actually worth. If you need to sell the vehicle or if it gets totaled in an accident, you will have to pay the difference out of pocket. To avoid these traps, we highly recommend reading The 5-Year Car Loan Roadmap: Navigating 15k, 30k and 50k Auto Loans to understand how to align your loan term with the vehicle’s lifespan.
To experiment with these numbers yourself, you can use interactive tools like the Auto Loan Calculator – LendingTree or the Auto Loan Calculator | Navy Federal Credit Union .
How Credit Scores and APR Impact Your $15k Auto Loan
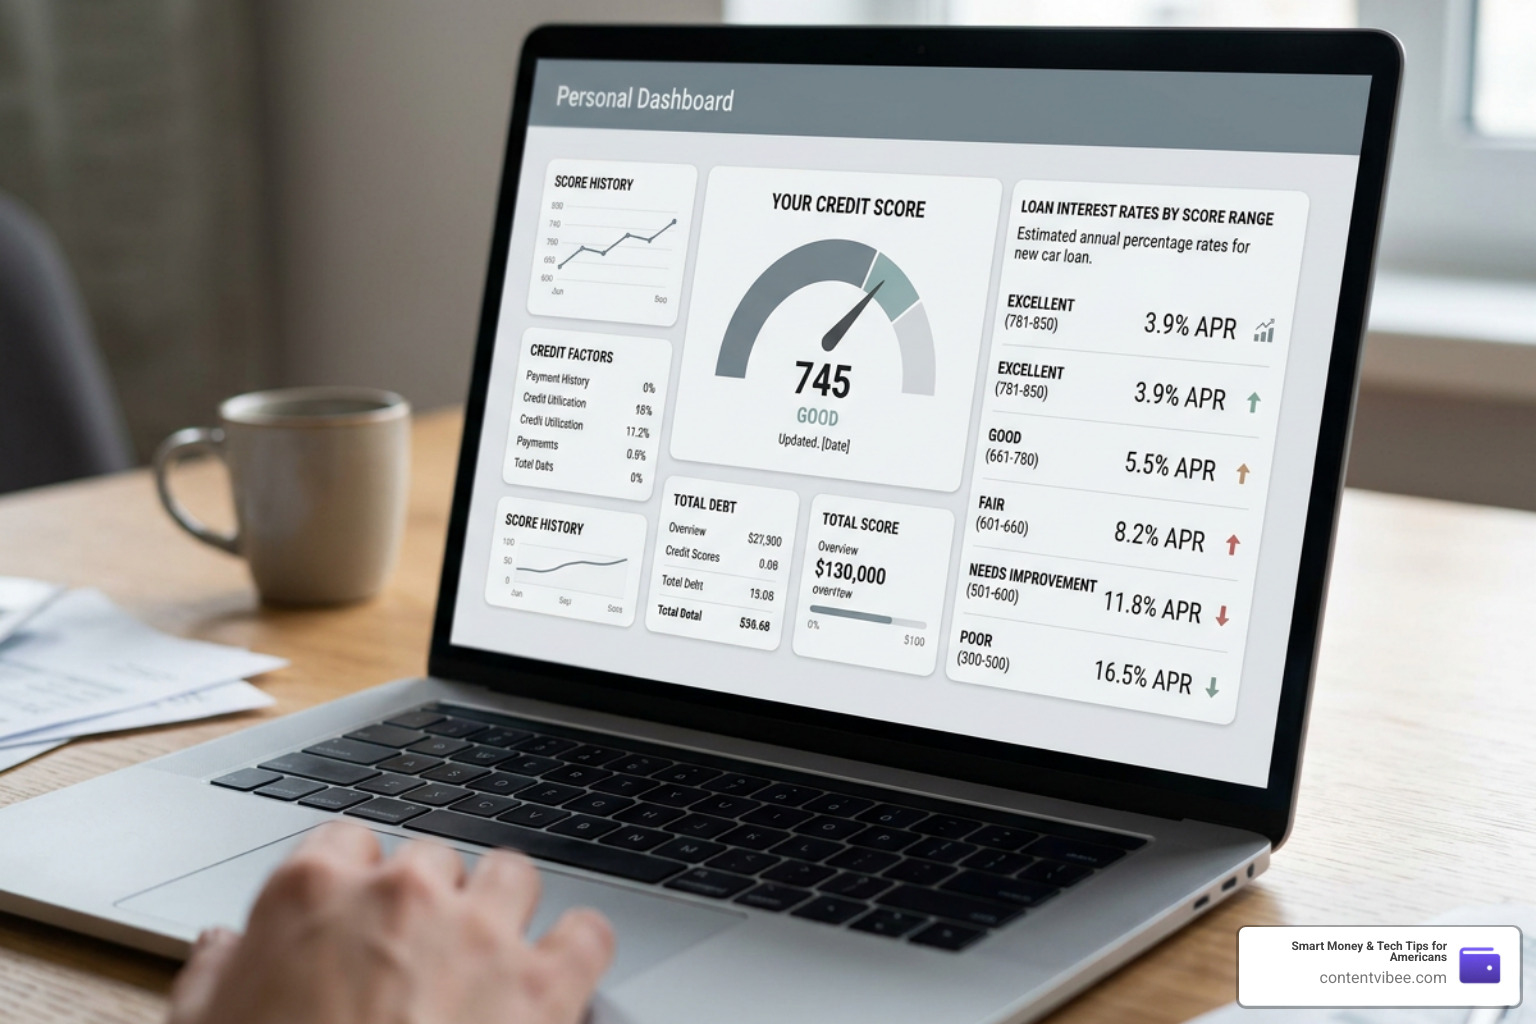
Your credit score is the single most powerful tool you have when negotiating a car loan. It acts as a financial resume, telling lenders how risky it is to lend you money. The higher your score, the lower the risk, and the lower the Annual Percentage Rate (APR) they will offer you.
APRs are not just simple interest rates; they represent the true annual cost of borrowing, including any lender fees. Because auto lenders typically use simple interest—where interest is calculated daily on the remaining principal balance—even a small difference in your APR can dramatically alter your total repayment amount.
Let’s break down the general credit tiers and the average interest rates borrowers are seeing in the current market:
- Super Prime (781–850): Borrowers in this tier enjoy the red-carpet treatment. They can expect new car rates around 4.88% to 6.81% and used car rates around 7.43% to 7.92%.
- Prime (661–780): Considered good credit, these buyers usually secure rates close to the national averages, typically around 7% to 9%.
- Near Prime (601–660): Lenders start to view these loans with a bit more caution, raising rates into the 10% to 12% range.
- Subprime (501–600): Borrowers with fair or damaged credit will face steep rates, often averaging 13.34% for new cars and up to 19.15% or higher for used options.
- Deep Subprime (300–500): This tier faces the most expensive financing terms, with average rates climbing from 15.85% to an eye-watering 21.60% or more.
To see how these percentages play out in the real world, you can learn how to crunch the numbers using The Ultimate Guide to Using a Car Loan Rates Calculator.
Estimating Your Monthly Payment on $15000 Car Loan by Credit Tier
To show you exactly how much your credit score affects your pocketbook, let’s look at a realistic comparison. Imagine you are financing exactly $15,000 for a 60-month (5-year) used car loan.
Here is what your estimated monthly payment on a $15,000 car loan would look like across different credit tiers based on average 2026 interest rates:
- Excellent Credit (Super Prime – 7.92% APR):
- Monthly Payment: $303.58
- Total Interest Paid: $3,214.80
- Fair Credit (Near Prime/Subprime – 16.20% APR):
- Monthly Payment: $366.39
- Total Interest Paid: $6,983.40
- Poor Credit (Deep Subprime – 21.13% APR):
- Monthly Payment: $406.84
- Total Interest Paid: $9,410.40
Look at that gap! A borrower with poor credit will pay $103.26 more every single month than someone with excellent credit for the exact same $15,000 loan. Over the course of the 5-year loan, that adds up to an extra $6,195.60 in pure interest.
This is why we always advise taking a step back to check and improve your credit score before applying for a loan. Paying down credit card balances to keep your utilization under 30% or correcting errors on your credit report can save you thousands of dollars. If you want to see how different credit scores and interest rates alter your potential payments, try playing with the numbers on our finance calculator.
New vs. Used Car Rates and Their Impact on a $15k Loan
When shopping for a vehicle with a $15,000 budget, you will likely be looking at used or certified pre-owned (CPO) vehicles. However, if you are using a $15,000 loan as a partial payment for a more expensive vehicle, you might be considering a new car.
It is important to know that lenders charge different interest rates depending on the vehicle’s condition. Generally, new cars qualify for lower APRs than used cars. This is because new cars have higher, more predictable resale values, making them lower-risk collateral for the lender. If a borrower defaults on a new car, the lender can easily repossess and sell it to recoup their losses.
On the other hand, used cars carry higher interest rates—often 1.5% to 3% higher than their new counterparts. However, used cars have a massive financial advantage: depreciation. A new car loses roughly 15% to 20% of its value the moment you drive it off the dealership lot, and up to 50% of its value within the first five years. By choosing a high-quality used car, you let the previous owner absorb that initial massive drop in value.
So, while you might pay a slightly higher interest rate on a used car loan, your overall principal amount will be significantly lower, saving you money on registration, insurance, and total depreciation. If you are still torn between leasing a new model or financing a used one, check out our guide on Everything You Need to Know About Lease vs Finance to find the best fit for your financial goals.
Applying the 20/4/10 Rule to Your Vehicle Purchase
To keep your car purchase from turning into a financial burden, financial planners recommend using the 20/4/10 rule. This simple framework is designed to keep your transportation costs in check so you still have plenty of money left over for savings, housing, and fun.
Here is how the rule breaks down:
- 20% Down Payment: Put down at least 20% of the vehicle’s purchase price. This immediately builds equity, lowers your loan principal, and prevents you from going “upside-down” on the loan.
- 4-Year Financing: Limit your loan term to no more than 4 years (48 months). This ensures you pay off the car quickly and minimizes the total interest you pay.
- 10% Transportation Budget: Keep your total monthly transportation costs under 10% of your gross (before-tax) monthly income. Crucially, this 10% must include not just your car loan payment, but also car insurance, fuel, maintenance, and registration fees.
For example, if your gross monthly income is $5,000, your total monthly vehicle expenses should not exceed $500. If your car insurance costs $120 and gas costs $100, your maximum car loan payment should be capped at $280.
Using this rule helps you work backward from your income to find a vehicle price that actually fits your life, rather than letting a smooth-talking salesperson talk you into a payment that stretches you to your absolute limit.
How a Down Payment Lowers Your Monthly Payment on $15000 Car Loan
Let’s look at how a down payment can transform your car-buying math. Suppose you have chosen a beautiful used sedan priced at $15,000.
If you walk into the dealership with zero money down, you will need to finance the entire $15,000. At a 10% APR for 48 months, your monthly payment will be $380.44, and you will pay $3,261.12 in total interest.
Now, let’s see what happens if you apply the 20/4/10 rule and put 20% down ($3,000):
- New Loan Principal: $12,000
- Monthly Payment (at 10% APR for 48 months): $304.35
- Total Interest Paid: $2,608.80
By saving up that $3,000 down payment, you accomplish three major wins:
- You lower your monthly payment by $76.09 every month.
- You save $652.32 in interest payments over the life of the loan.
- You lower your loan-to-value (LTV) ratio, which makes you look much safer to lenders, potentially helping you secure a lower interest rate.
Every single dollar you put down reduces your principal and saves you money. If you want to see how different down payment amounts alter your monthly budget, you can easily plug your numbers into our finance calculator.
Hidden Costs and Strategies to Pay Off Your Loan Early
One of the most common mistakes car buyers make is budgeting only for the monthly car payment. Unfortunately, driving a car involves several other ongoing expenses that can quickly drain your bank account if you don’t plan for them.
When you buy a car, you must account for:
- Sales Tax and Dealer Fees: Depending on your state, sales tax can add 5% to 10% to the purchase price. Dealer documentation fees, title, and registration fees can easily add another $500 to $1,500. If you roll these fees into your loan, you will pay interest on them for years.
- Car Insurance: Lenders require you to carry comprehensive and collision coverage while you have an active auto loan. This is significantly more expensive than basic liability coverage.
- Maintenance and Repairs: Tires, oil changes, brake pads, and unexpected repairs add up. On average, car ownership costs can add thousands of dollars annually beyond your loan payments.
Strategies to Pay Off Your Loan Early
If you want to beat the system and minimize the interest you pay, you should consider paying off your loan ahead of schedule. Because car loans use simple interest, paying down your principal early directly reduces the amount of interest that accumulates each day.
Here are three highly effective strategies to shorten your loan:
- The Bi-Weekly Payment Method: Instead of making one monthly payment, pay half of your monthly payment every two weeks. Because there are 52 weeks in a year, you will end up making 26 half-payments—which equals 13 full monthly payments instead of 12. This cuts months off your loan without you even noticing.
- Round Up Your Payments: If your monthly payment is $304, round it up to $350 or $400. Direct the extra amount specifically toward your principal balance (make sure your lender doesn’t apply it to the next month’s payment instead).
- Make One Extra Payment a Year: Use your tax refund or an annual work bonus to make a single, large principal-only payment once a year.
Before you start overpaying, check your loan contract to ensure there are no prepayment penalties. Most modern auto loans do not have them, but it is always smart to double-check. To see exactly how much time and money you can save by paying off your loan early, take a look at Discover how prepayment calculators save you money.
For quick calculations on smaller loans or to compare different simple interest amortization schedules, you can also check out the $1,000 Car Loan Monthly Payments Calculator or play with the Auto Loan Calculator | Car Payment, Interest & Total Cost .
Frequently Asked Questions About $15,000 Car Loans
Is 2026 a good time to finance a $15,000 car loan?
The 2026 interest rate environment is higher than the historic lows of the previous decade. However, because a $15,000 loan is relatively small compared to the average national loan size, the impact of these higher rates is much less severe. If you have strong credit, shop around with local credit unions (which consistently offer rates 1% to 2% lower than traditional banks), and keep your term short, 2026 is still a perfectly fine time to buy a reliable vehicle.
How can I lower my monthly car payment without extending my term?
The best way to lower your payment without stretching your term is to reduce the amount you borrow. You can do this by making a larger down payment, trading in your current vehicle, or negotiating a lower out-the-door price on the car. Additionally, shopping around and comparing offers from multiple lenders can save you an average of $2,346 over the life of your loan. You can use tools like the Auto Loan Calculator – Estimate Car Payments – Capital One or the Auto Loan Calculator to compare different lending options side-by-side.
Does a $15,000 car loan require GAP insurance?
Guaranteed Asset Protection (GAP) insurance covers the difference between what your car is worth and what you owe on your loan if the vehicle is totaled. If you put down less than 20% on a new car or choose a loan term longer than 60 months, you should consider GAP insurance. However, if you are buying a used car that has already experienced its steepest depreciation, or if you made a solid down payment, you likely do not need it. If you do buy GAP insurance, get it through your auto insurance provider—dealers often charge a massive markup for it.
Conclusion
Securing a $15,000 car loan is a fantastic, practical way to get behind the wheel of a reliable vehicle without drowning in debt. By understanding how your credit score, APR, and loan term interact, you can easily customize a payment plan that fits comfortably within your monthly budget. Remember to aim for a solid down payment, keep your loan term as short as practical, and always budget for the total cost of ownership—including insurance and maintenance—rather than just the monthly payment itself.
At ContentVibee, we are dedicated to helping you make smart, actionable financial decisions that protect your hard-earned money. If you are ready to start planning your next vehicle purchase, take the first step and Optimize your auto budget with our finance calculator to find your perfect payment sweet spot today!


