


Why Finding the Best Health Insurance for Self Employed Is Harder Than It Looks
The best health insurance for self employed workers in 2026 depends on your income, location, and health needs — but here are the top options to consider right now:
Top Health Insurance Options for Self-Employed People (2026):
| Option | Best For | Key Benefit |
|---|---|---|
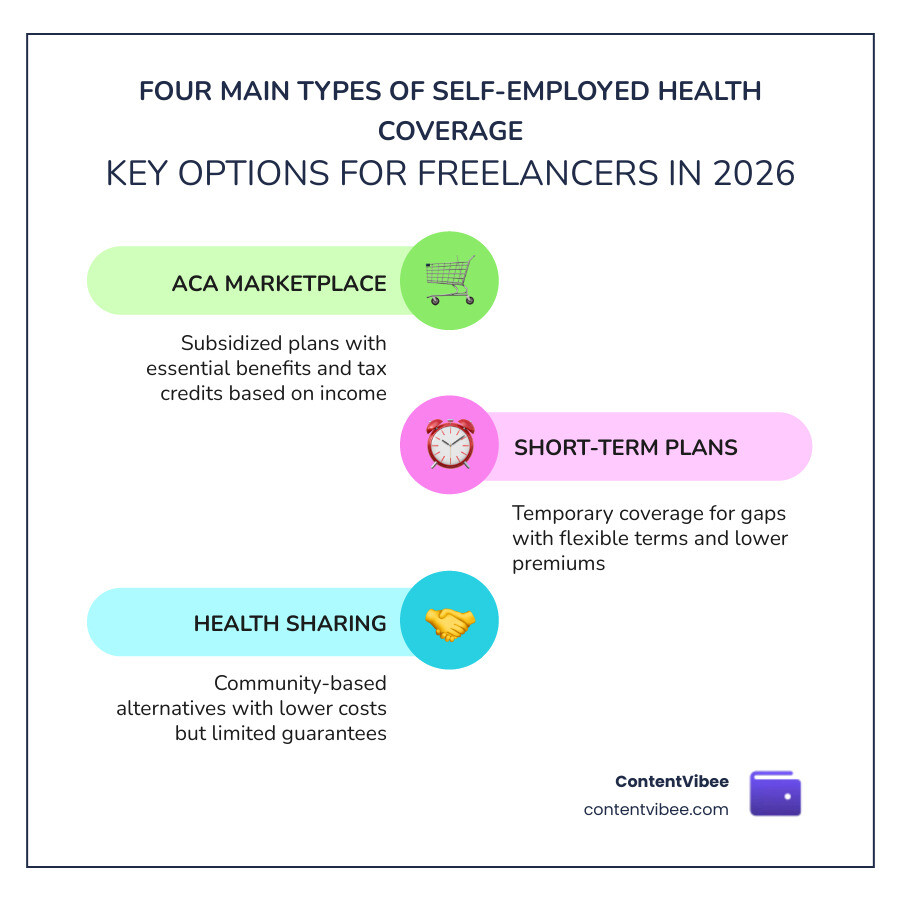
| ACA Marketplace Plans | Most self-employed individuals | Premium tax credits based on income |
| Blue Cross Blue Shield | Nationwide coverage flexibility | Available in all 50 states + D.C. |
| UnitedHealthcare | Broad plan variety | ACA plans in 30 states + TriTerm short-term |
| Kaiser Permanente | Coordinated, quality care | Integrated care model in 8 states + D.C. |
| Ambetter | Budget-conscious freelancers | Low-premium ACA plans in 29 states |
| Short-Term Plans | Coverage gaps only | Flexible start dates, lower premiums |
| Health Sharing Plans | Those wanting alternatives | Lower monthly costs, community-based |
When you work for yourself, nobody picks your benefits for you. No HR department. No employer splitting the premium. You carry the full weight — and that changes everything about how you shop for coverage.
More than 82% of freelancers say healthcare access influences how they vote, according to Freelancers Union. That stat alone tells you how much this issue matters to the self-employed community.
The good news? In 2026, the options are better than ever — if you know where to look. The ACA Marketplace, private insurers, health sharing plans, and alternative models like concierge medicine all compete for your business. The challenge is knowing which one actually fits your situation.
This guide cuts through the noise so you can make a confident, informed decision.
Simple guide to best health insurance for self employed:
- average mesothelioma settlement amounts
- mesothelioma compensation for family members
- what is the average settlement for asbestos claim
Navigating the Best Health Insurance for Self Employed in 2026
As we move through May 2026, the landscape for independent workers has shifted. Being “self-employed” isn’t just one thing anymore; it’s a spectrum that includes gig workers, high-earning consultants, and small business owners with a handful of employees. According to Health Care Insurance Coverage for Self-Employed Individuals | HealthCare.gov, you are officially considered self-employed if you have a business that generates income but has no employees other than yourself, a spouse, or a family member.
If you fall into this category, your primary hub for coverage is the Individual Health Insurance Marketplace. This is where most people find the best health insurance for self employed because it is the only place where you can access federal subsidies that make premiums affordable. For those of us in Virginia, the state-run exchange provides a streamlined way to compare these Health Insurance Options For Every American Family/.
Top-Rated Providers for the Best Health Insurance for Self Employed
Choosing a provider is often about balancing the size of the doctor network against the monthly cost. In 2026, several carriers stand out for their commitment to the independent workforce:
- Blue Cross Blue Shield (BCBS): Still the heavyweight champion for nationwide coverage. If you are a consultant who travels frequently between Virginia and other states, BCBS offers the most robust PPO networks, ensuring you aren’t stuck with “out-of-network” bills just because you crossed a state line.
- Anthem: Operating as part of the BCBS family in Virginia, Anthem provides “Essential Extras” that have become popular in 2026, sometimes including benefits for groceries or utilities for qualifying members. You can learn more about their specific offerings at Health Insurance for the Self-Employed | Anthem.
- UnitedHealthcare: Known for its “TriTerm” medical plans and its CareFlex Visa card, which helps members manage daily health expenses. They offer a great balance of ACA-compliant plans and supplemental options.
- Oscar Health: The go-to for the tech-savvy freelancer. Their app-first approach and $0 virtual urgent care make them a strong contender for the best health insurance for self employed individuals who prefer managing everything from their smartphone.
For a deeper dive into how these companies rank this year, check out Best Health Insurance for Self-Employed (2026): Top Plans and Smart Options.
Understanding ACA Marketplace and Premium Tax Credits
The “secret sauce” of the ACA Marketplace is the Premium Tax Credit. Since self-employed income can be a bit of a roller coaster, these credits are vital. They are based on your estimated household income for the upcoming year, not what you made last year.
In Virginia, eligibility is determined by your household size and how your income compares to the federal poverty level. If you earn between 100% and 400% of that level (and sometimes more, depending on current 2026 legislation), you could see your monthly premiums drop by hundreds of dollars. The Coverage for Self-Employed Individuals – Virginia’s Insurance … portal is the best place to check your specific eligibility.
Short-Term vs. Long-Term Coverage Options
Sometimes, you just need a bridge. Maybe you just left a corporate job and are waiting for your first big contract to land before committing to a high-premium plan. This is where short-term medical plans come in.
| Feature | ACA-Compliant Plans | Short-Term Medical Plans |
|---|---|---|
| Pre-existing Conditions | Always covered | Often excluded |
| Essential Benefits | Includes maternity, mental health | Limited coverage |
| Duration | 1 year (renewable) | 1–12 months (or up to 3 years) |
| Subsidies | Available | Not available |
UnitedHealthcare’s branded short-term plans can last up to three years with just one application, providing a longer-term “temporary” solution. However, we generally recommend these only as a last resort because they don’t offer the comprehensive protections found in Self-employed health insurance | UnitedHealthcare Marketplace options.
Maximizing Your Coverage and Tax Benefits
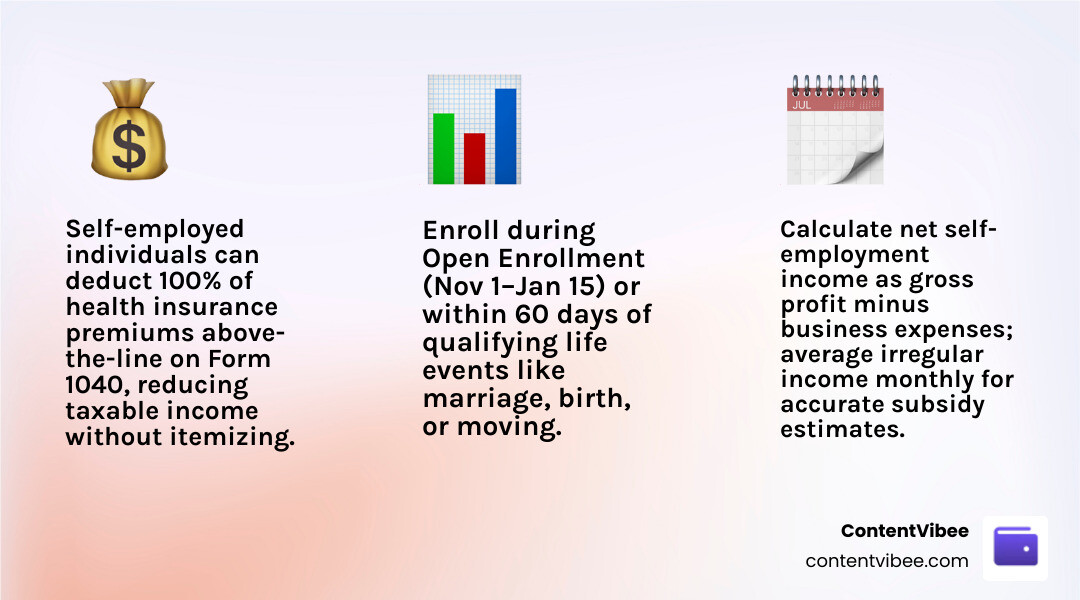
One of the few perks of being your own boss is the tax treatment of your health insurance. If you are self-employed and have a net profit for the year, you can usually deduct 100% of your health insurance premiums for yourself, your spouse, and your dependents. This is an “above-the-line” deduction on Form 1040, meaning you don’t have to itemize to claim it.
This deduction effectively lowers your taxable income, which can be a massive financial relief. You can find more tips on navigating these financial waters in our category/insurance/ section.
How to Estimate Net Self-Employment Income for the Best Health Insurance for Self Employed
Estimating income is the hardest part of the application for us. If you over-estimate, you pay too much each month. If you under-estimate, you might have to pay back some of those tax credits at the end of the year.
To get it right, focus on your net self-employment income. This is your gross income minus all allowable business expenses (advertising, home office, equipment, etc.). If your income fluctuates, take your total expected annual profit and divide it by 12 to get a monthly average. Experts at AX Health Insurance – Empowering Your Health Journey suggest updating your income on the Marketplace whenever you see a change of $150 or more per month to keep your subsidies accurate.
Alternative Health Solutions: Healthshares and Concierge Medicine
For those who find traditional insurance “ghoulishly” expensive (as some frustrated Reddit users put it), alternative models have gained traction in 2026.
- Health Sharing Plans: These are community-based organizations where members share each other’s medical costs. They aren’t insurance, but they often cost about half as much.
- Direct Primary Care (Concierge Medicine): You pay a flat monthly fee (often $60–$100) directly to a doctor’s office. In exchange, you get unlimited visits and wholesale pricing on labs. Many freelancers pair this with a high-deductible plan for “catastrophic” events.
- Association Plans: Groups like the Freelance Health Insurance | Tailored Self-Employed Plans allow individuals to band together to access group-like rates and portable benefits.
Enrollment Periods and Updating Your Coverage
You can’t just buy health insurance whenever you want. You must enroll during Open Enrollment, which typically runs from November 1 to January 15.
However, life happens. If you lose your job, get married, have a baby, or move to a new ZIP code in Virginia, you trigger a Special Enrollment Period (SEP). This gives you a 60-day window to sign up for a plan outside of the standard dates. For more on managing these transitions, see Self-Employed Health Insurance | Cigna Healthcare.
At ContentVibee, we want to make sure you’re protected not just in health, but in your overall financial journey. Whether you’re looking into Ethos Life Insurance Reviews/ or wondering Is Whole Life Insurance A Good Investment/, we have the resources to help. You might even want to explore Why Life Insurance Investment Cash Value Growth/ or What You Need To Know About Indexed Universal/ to see how life insurance can play a role in your long-term wealth strategy.
Before you sign on the dotted line, make sure you’ve done the math. Calculate your potential savings with our settlement calculator to see how different financial decisions impact your bottom line.
Final Thoughts on Choosing a Plan
Finding the best health insurance for self employed isn’t a one-and-done task. It’s an annual ritual of checking your network, re-estimating your income, and ensuring your plan still fits your lifestyle. In 2026, the power is in your hands—you just have to take the time to use it. Stay healthy, stay insured, and keep building your dream business!


