


Why a Mortgage Payoff Calculator Early Could Save You Tens of Thousands
Using a mortgage payoff calculator early in your planning process can reveal something most homeowners never realize: small extra payments today can save you an enormous amount of money over time.
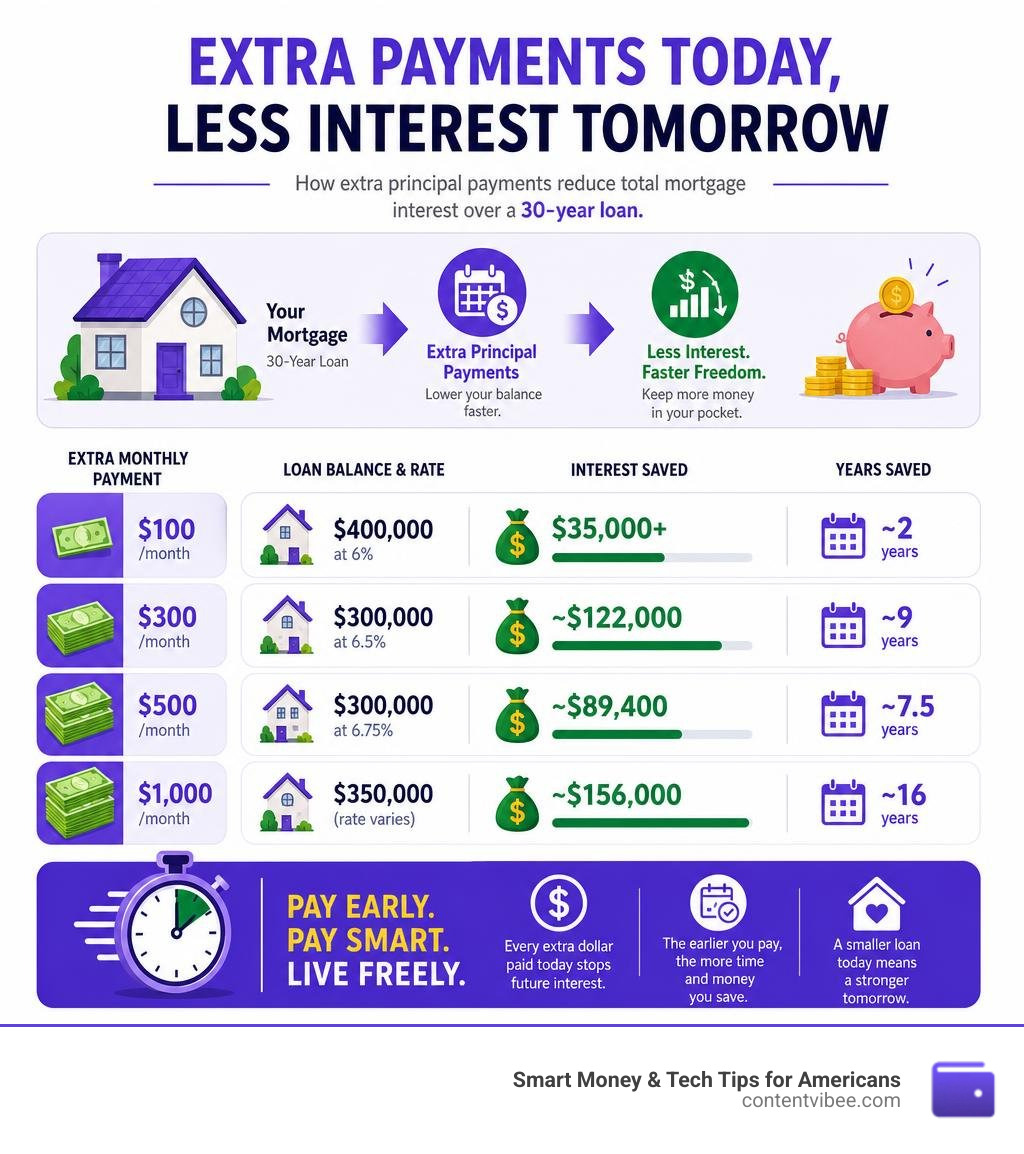
Here’s a quick snapshot of what’s possible:
| Extra Monthly Payment | Loan Balance | Interest Saved | Years Saved |
|---|---|---|---|
| $100/month | $400,000 at 6% | $35,000+ | ~2 years |
| $300/month | $300,000 at 6.5% | ~$122,000 | ~9 years |
| $500/month | $300,000 at 6.75% | ~$89,400 | ~7.5 years |
| $1,000/month | $350,000 | ~$156,000 | ~16 years |
The math is straightforward. Every extra dollar you pay toward your principal today stops interest from accruing on that dollar for the rest of your loan. The earlier you pay it, the more you save.
For pre-retirees especially, this matters a lot. Entering retirement with no mortgage payment means lower fixed expenses, less financial stress, and more flexibility with your income. That’s a powerful position to be in.
But knowing how much to pay — and when — requires running the numbers. That’s exactly what an early mortgage payoff calculator helps you do.
Basic mortgage payoff calculator early terms:
The Mechanics of Early Mortgage Payoffs
To understand how a mortgage payoff calculator early works, we first have to demystify how standard home loans are structured. Most American homeowners sign up for a 30-year fixed-rate mortgage. On day one, your monthly payment is locked in, but the way your money is divided behind the scenes changes every single month.
This shifting division is called amortization. In the early years of a mortgage, your payments are heavily “front-loaded” with interest. For example, during the first year of a standard 30-year loan, roughly 80% of your monthly payment goes directly to the lender to cover interest, while a measly 20% actually chips away at your principal balance.
Because interest is calculated as a percentage of your remaining principal balance, the larger your balance, the more interest you owe. If you want to stop this cycle, you have to attack the principal directly. When you make an extra payment designated for the principal, you bypass the interest schedule entirely. That money immediately reduces your outstanding balance, which permanently shrinks the base upon which your future interest is calculated.
This process triggers a reverse compounding effect. Instead of interest building on top of interest to make you poorer, your principal reductions compound over time to save you more money with every passing year. To visualize how these shifting numbers fit into your household budget, it helps to track your cash flow systematically.
If you are currently juggling multiple financial obligations, you can also Take Control Of Your Debt With A Monthly Loan Repayment Calculator to see how your mortgage fits alongside other monthly commitments.
How Extra Payments Reduce Total Interest
When you send extra funds to your mortgage servicer, you are shortening the lifespan of your loan and stripping away the interest the lender would have otherwise collected.
Let’s look at the math using real-world data. If you have a $200,000 mortgage at typical market rates, adding just $300 extra per month to your principal can save you over $64,000 in total interest and pay off your loan 11 years sooner.
Even incredibly small amounts make a difference because of how front-loaded interest works. For example, paying an extra $6 per month on a $200,000, 30-year loan at 5% interest will pay off the loan four months early, saving you $2,796 in interest. If you find a spare $25 per month to add to a $400,000 loan at 6% interest, you will save $9,565 in interest and shorten your repayment timeline by seven months.
Every single dollar you pay early acts as an employee working to save you future money. The key is consistency and timing; a dollar paid toward your principal in year two of your mortgage saves far more interest over the life of the loan than a dollar paid in year twenty-five.
The True Cost of Homeownership: Beyond Principal and Interest
While a mortgage payoff calculator early is fantastic for tracking principal and interest, we must remember that your actual monthly housing expense is much higher. Your standard monthly mortgage payment typically includes several other components:
- Property Taxes: Collected by your local government to fund schools, roads, and public services.
- Homeowners Insurance: Protection for your physical structure and personal liability.
- Private Mortgage Insurance (PMI): Usually required if you put down less than 20% when purchasing the home.
- HOA Fees: Homeowners association dues for community maintenance.
These additional expenses can easily add $400 to $900 per month beyond your principal and interest. When you pay off your mortgage early, you eliminate the principal and interest portion of your payment, but you will still be responsible for property taxes, homeowners insurance, and HOA dues.
However, accelerating your payoff can help you eliminate PMI much faster. Once your extra principal payments bring your loan-to-value (LTV) ratio down to 80%, you can request that your lender drop the PMI, immediately freeing up extra cash in your monthly budget.
How to Use a Mortgage Payoff Calculator Early to Plan Your Debt-Free Timeline
A mortgage payoff calculator early is an invaluable planning tool, but its accuracy depends entirely on the numbers you feed it. To get a clear picture of your accelerated debt-free timeline, you will need to gather a few key inputs from your most recent mortgage statement: your remaining balance, your current interest rate, and your monthly principal and interest payment.
Before diving deep into your mortgage math, you might also want to Explore our comprehensive suite of financial tools to help organize your broader financial picture.
Step-by-Step: Navigating a Mortgage Payoff Calculator Early When You Know Your Term
If you know exactly how many years or months are left on your home loan, using a calculator is incredibly simple. Excellent options like the Calculator.net Mortgage Payoff Calculator or the BoringCalc Mortgage Payoff Calculator allow you to input your exact remaining term.
Here is how to navigate the process step-by-step:
- Input the Core Loan Details: Enter your current outstanding principal balance, your annual interest rate, and the remaining term (e.g., 20 years and 4 months).
- Add Your Extra Payment Strategy: Most advanced tools, such as the Toolraxy Mortgage with Extra Payments Calculator, let you choose between monthly extra payments, a yearly lump sum, or a one-time payment.
- Analyze the Amortization Schedule: Look at the generated schedule to compare your original payoff date against your new, accelerated date.
- Review the Savings Summary: Note the exact dollar amount of interest you will save and how many years you will shave off the loan.
Using these tools allows you to play “what-if” games with your money, adjusting the extra payment amount until you find a balance that fits your monthly cash flow.
Using a Mortgage Payoff Calculator Early When Your Remaining Term is Unknown
What if you don’t know exactly how many months are left on your mortgage? Perhaps you have made sporadic extra payments in the past, or you simply lost track of the timeline.
In this case, you can use calculators designed for unknown remaining terms, such as the Early Loan Payoff Calculator. These calculators work backward using your current balance, interest rate, and monthly principal and interest payment.
The calculator uses the standard amortization formula to estimate your remaining months:
$$M = \frac{P \cdot (r(1+r)^n)}{(1+r)^n – 1}$$
Where:
- $M$ is your monthly payment
- $P$ is the principal loan amount
- $r$ is your monthly interest rate (annual rate divided by 12)
- $n$ is the total number of payments
By inputting what you do know, the tool calculates your baseline payoff date and then lets you overlay extra payments to see how much faster you can cross the finish line.
Proven Strategies for Accelerating Your Mortgage Payoff
There is no single “right” way to pay off a mortgage early. The best strategy is the one that aligns with your income, your financial habits, and your personal comfort level.
To help you visualize these different timelines, we can look at a calendar setup that highlights how adjusting your payment frequency changes your payoff date.
Whether you are trying to pay off a house or a vehicle, planning ahead is key. If you are also managing vehicle debt, you can read The Early Bird Gets The Title Your Guide To Car Loan Prepayment Calculators to apply similar prepayment principles to your auto loan.
The Bi-Weekly Payment Strategy
The bi-weekly payment strategy is highly popular because it accelerates your payoff without requiring a massive lifestyle change. Instead of making one full mortgage payment every month, you pay half of your monthly payment every two weeks.
Because there are 52 weeks in a year, you will make 26 half-payments. This adds up to 13 full monthly payments per year instead of the standard 12. This extra payment is applied directly to your principal, quietly shaving years off your loan term.
For example, switching to bi-weekly payments on a $300,000 mortgage at 6.5% interest shaves roughly 5.5 years off the loan and saves about $68,000 in interest. The beauty of this method is that it feels relatively painless, especially for those who are paid bi-weekly by their employers.
Lump-Sum Payments and Mortgage Recasting
If you prefer to keep your monthly budget flexible, you can opt for lump-sum payments instead of a recurring commitment. This strategy involves using unexpected windfalls—such as tax refunds, work bonuses, or inheritances—to make one-time principal payments.
A single, well-timed lump sum can have a massive impact. For example, a one-time $1,000 extra payment on a $200,000, 30-year loan at 5% interest can pay off the loan four months earlier, saving $3,420 in interest.
If you make a substantial lump-sum payment, you might also consider a mortgage recast. Unlike a refinance, which replaces your existing loan with a new one, a recast keeps your current interest rate and term but re-calculates your monthly payment based on your new, lower principal balance.
Lenders typically charge a small fee ($250 to $500) to recast a loan. While recasting lowers your monthly obligation and provides a safety net, continuing to make your original, higher payment after a recast is mathematically superior if your goal is to pay off the loan as fast as possible.
Key Considerations Before Making Extra Payments
Before you start funneling every spare dollar into your mortgage, you must look at your entire financial landscape. Paying off a home early is a wonderful goal, but it should not be done at the expense of your overall financial security.
If you have other outstanding debts, it is vital to compare interest rates. You can Take Control Of Your Debt With A Monthly Loan Repayment Calculator to analyze your non-mortgage liabilities first.
Paying Off the Mortgage vs. Investing
One of the most debated topics in personal finance is whether you should pay off your mortgage early or invest that extra money in the stock market. The answer depends heavily on your mortgage interest rate, market conditions, and your personal risk tolerance.
In the current environment of July 2026, mortgage rates have settled into a higher range of 6.5% to 7.5%. At these rates, paying down your mortgage principal offers a guaranteed, risk-free return equal to your interest rate. It is incredibly difficult to find a guaranteed, tax-free 7% return anywhere else.
However, if you bought or refinanced your home during the historic lows of 2021 and locked in a rate of 2.75% or 3%, the math changes. In that scenario, investing your extra cash in a diversified index fund or even a high-yield CD yielding 4% to 5% is mathematically superior.
Additionally, you should always prioritize maxing out tax-advantaged retirement accounts—such as a 401(k) with an employer match or a Roth IRA—before prepaying a low-interest mortgage. Cash in an investment account is liquid and can be accessed in an emergency, whereas home equity is locked up in the physical walls of your house.
Prepayment Penalties and Lender Rules
Before sending extra money to your lender, you must confirm that your loan does not carry a prepayment penalty. A prepayment penalty is a fee charged by some lenders if you pay off your mortgage early, usually within the first three to five years of the loan.
The good news is that prepayment penalties have become rare in modern lending. In fact, FHA loans, VA loans, and loans issued by federally chartered credit unions strictly prohibit prepayment penalties.
Even if your loan has no penalties, you must ensure your extra payments are applied correctly. Some mortgage servicers will default to applying extra money to your next scheduled monthly payment instead of your principal balance. When submitting extra funds online or via check, always specify that the additional amount should be designated as a “Principal-Only Payment.”
Real-World Scenarios: The Impact of Extra Payments
To see how these strategies play out, let’s look at three different homeowners who decided to accelerate their mortgage payoffs using different monthly amounts.
For these scenarios, we will assume a baseline 30-year fixed mortgage of $300,000 at a 6.5% interest rate, with 25 years remaining on the loan.
| Scenario | Extra Monthly Payment | New Payoff Timeline | Time Saved | Total Interest Saved |
|---|---|---|---|---|
| Standard Payment | $0 | 25 years | 0 months | $0 |
| Moderate Accelerator | $100 | ~21 years | 4 years | ~$56,000 |
| Aggressive Accelerator | $300 | ~16 years | 9 years | ~$122,000 |
| Supercharged Accelerator | $500 | ~12.5 years | 12.5 years | ~$170,000 |
As you can see, even a modest $100 extra per month saves $56,000 in interest and gets you out of debt four years faster. If you can stretch that to $300 or $500, the savings compound dramatically, allowing you to own your home free and clear up to a decade early.
Frequently Asked Questions about Early Mortgage Payoffs
Will making extra payments lower my monthly bill?
No. Making extra principal payments will not lower your regular monthly mortgage bill. Your monthly payment is set by your original loan agreement. Instead, your extra payments reduce the outstanding principal balance, which shortens the overall length of your loan and reduces the total interest you pay over time.
If you want to lower your actual monthly bill, you would need to either refinance your mortgage to a lower rate or request a formal mortgage recast from your lender after making a substantial lump-sum payment.
Will paying off my mortgage early hurt my credit score?
In the short term, you might see a minor, temporary dip in your credit score after paying off your mortgage. This happens because open, active accounts with a history of on-time payments contribute positively to your credit mix and payment history.
However, this minor drop is temporary and should not deter you from becoming debt-free. The financial freedom and interest savings of not having a monthly housing payment far outweigh a temporary fluctuation of a few points on your credit report.
Should I pay off my mortgage before retirement?
For many pre-retirees, entering retirement without a monthly mortgage payment is the ultimate financial goal. Eliminating your largest monthly fixed expense drastically reduces your required retirement income, which means you can withdraw less from your retirement accounts, reducing your tax burden and making your nest egg last much longer.
However, if your mortgage rate is extremely low (under 3%) and you have a shortfall in your liquid retirement savings, it may be wiser to keep the mortgage and focus on building up your retirement cash reserves first.
Conclusion
At ContentVibee, we believe that making smart money decisions is about balancing mathematical optimization with personal peace of mind. Paying off your mortgage early using a mortgage payoff calculator early is a proven way to secure your financial future, eliminate debt, and build lasting wealth.
Whether you choose to round up your monthly payments, commit to a bi-weekly schedule, or make occasional lump-sum payments, every step you take brings you closer to true financial freedom. To start planning your path to a debt-free life, Explore our comprehensive suite of financial tools and run the numbers for your unique situation today.


