Why California Health Insurance Quotes Vary More Than You Think
Getting california health insurance quotes can feel overwhelming — especially when you’re already dealing with medical bills or recovering from an unexpected health event.
Here’s a quick snapshot of what to expect in 2026:
| Plan Tier | Avg. Monthly Premium (Individual) | Best For |
|---|---|---|
| Bronze | ~$400-$490 | Healthy people, low usage |
| Silver | ~$601-$640 | Most individuals, subsidy eligible |
| Gold | ~$700-$800 | Regular medical needs |
| Platinum | ~$900+ | High healthcare users |
Note: Premiums vary by age, location, and income. Subsidies can reduce these costs significantly — sometimes to $0/month.
The short version:
- The average Silver plan in California runs about $640/month per person before subsidies
- Most Californians qualify for some financial help through Covered California
- Your final premium depends on your age, ZIP code, household income, and the plan tier you choose
- Open enrollment runs November 1 through January 31 each year
But the numbers alone don’t tell the full story.
Prices shifted noticeably for 2026. Kaiser raised rates by 7.1% — the lowest among major insurers. Health Net PPO jumped 15%. Blue Shield PPO increased 9.2%. That means the plan you had last year may no longer be your best deal.
Whether you’re uninsured, between jobs, or just trying to cut your monthly costs, this guide walks you through everything you need to know to compare your options and find real coverage at a price that makes sense.
Understanding Plan Types and Metal Tiers in California
When you start looking at california health insurance quotes, you will quickly notice that plans are categorized in two primary ways: network types (like HMOs and PPOs) and metal tiers (Bronze, Silver, Gold, and Platinum). Navigating these options is much easier once you understand how they balance upfront costs against care delivery. For a broader look at how these systems work nationwide, check out A Comprehensive Guide to Health Insurance Plans Comparison.
HMO vs. PPO vs. EPO Plans
The network type determines which doctors you can see and how much flexibility you have when seeking care. In California, three main network structures dominate the market:
- Health Maintenance Organizations (HMOs): HMOs require you to choose a Primary Care Physician (PCP) who acts as the gatekeeper for your healthcare. If you need to see a specialist, you must get a referral from your PCP first. Except in emergencies, HMOs do not cover out-of-network care. Major California HMO networks, such as Kaiser Permanente or Blue Shield Trio, are highly popular because they offer lower monthly premiums and predictable copays.
- Preferred Provider Organizations (PPOs): PPOs offer the ultimate flexibility. You do not need to select a PCP, and you do not need referrals to see specialists. You can also see out-of-network doctors, though doing so will cost more than staying in-network. However, this freedom comes at a premium. For 2026, PPO rates have seen substantial increases — such as Health Net’s 15% PPO rate hike — prompting many residents to review the Open Enrollment Guide 2026 to see if transitioning to an HMO makes financial sense.
- Exclusive Provider Organizations (EPOs): EPOs represent a middle ground. Like a PPO, you usually do not need a referral to see a specialist. However, like an HMO, the plan will not cover any out-of-network care except in emergencies. If you want specialist freedom but want to keep your monthly premium manageable, an EPO can be an excellent compromise.
Bronze, Silver, Gold, and Platinum Tiers
Once you decide on a network, you must choose a “metal tier.” These tiers do not reflect the quality of medical care you receive; instead, they indicate how you and your insurer split the financial costs of your care.
- Bronze Plans: These have the lowest monthly premiums but the highest out-of-pocket costs when you receive care. In 2026, Bronze plans typically carry deductibles around $5,800 and individual out-of-pocket maximums near $9,800. They are best for healthy individuals who only want coverage for major medical emergencies. Notably, starting in 2026, all Bronze and Catastrophic plans in California have transitioned to being Health Savings Account (HSA) eligible, allowing you to save pre-tax dollars for future medical expenses.
- Silver Plans: Silver plans represent the “benchmark” for coverage. With average premiums around $640 per month before subsidies, they offer a balanced mix of moderate premiums and moderate deductibles (averaging $5,200 in 2026). Silver plans are especially valuable because they are the only tier eligible for Cost-Sharing Reductions (CSRs), which can dramatically lower your deductibles and copays if your income qualifies.
- Gold Plans: Gold plans feature higher monthly premiums but much lower deductibles and copays. If you manage chronic conditions, take regular prescription medications, or anticipate a major medical event (like having a baby), paying a higher premium for a Gold plan will likely save you money overall.
- Platinum Plans: Platinum plans have the highest monthly premiums but virtually no deductibles, alongside very low out-of-pocket costs when you visit the doctor. These are ideal for individuals with high, predictable medical needs who want absolute cost certainty.
Covered California vs. Off-Exchange Plans
When shopping for coverage, you have two primary pathways: purchasing a plan through the state’s official marketplace, Covered California, or buying a plan directly from an insurance carrier (known as an “off-exchange” plan). If you are trying to estimate your potential expenses, taking a look at the Covered California Estimated Cost guide can help clarify your options.
The Role of the State Marketplace
Covered California is the state-run marketplace established under the Affordable Care Act (ACA). It serves as a one-stop shop where you can compare standardized plans and, most importantly, apply for financial assistance.
To help make coverage accessible, the state has allocated dedicated funds to provide premium subsidies to low-income residents. If you buy a plan through Covered California™ | The Official Site of California’s Health Insurance Marketplace, your household income, location, and age will determine if you qualify for these federal and state tax credits, which can drastically lower your monthly bills.
When to Choose Off-Exchange Coverage
Off-exchange plans are purchased directly from insurance companies like Blue Shield, Anthem, or Kaiser, or through independent brokers.
Why would someone shop off-exchange?
- No Subsidy Eligibility: If your household income is high enough that you do not qualify for premium tax credits, shopping off-exchange allows you to explore a wider variety of plans that may not be listed on the state marketplace.
- Alternative Network Designs: Some insurers offer unique, specialized plan designs or niche provider networks exclusively off-exchange.
- Avoiding Surcharges: In some years, specific marketplace fees or surcharges (such as the CSR surcharge on certain on-exchange Silver plans) make off-exchange plans slightly more cost-effective for unsubsidized buyers.
That off-exchange plans must still cover the ten essential health benefits mandated by the ACA, and they cannot deny you coverage or charge you more for pre-existing conditions. However, you cannot use federal or state subsidies to pay for them.
What Does Health Insurance Cost in California for 2026?
Understanding the overall price landscape is crucial before you start requesting california health insurance quotes. For an in-depth breakdown of these financial components, you can read How Much Does Health Insurance Actually Cost in California.
Average Premiums and Out-of-Pocket Costs
For individual coverage in California, residents pay an average of $601.74 per person across all plan types, with a standard Silver plan averaging approximately $640 per month ($7,680 per year) before any subsidies are applied.
If you are purchasing coverage for a family, expect those numbers to scale. Family plans typically cost two to three times more than individual plans. For example, a healthy family of three (parents in their mid-30s and one child) earning a moderate income might see a baseline Silver plan premium of $1,500 per month, which can drop to around $700 per month after accounting for an average $800 monthly subsidy.
The table below outlines the relationship between monthly premiums and out-of-pocket structures across the metal tiers for 2026:
| Metal Tier | Average Monthly Premium | General Out-of-Pocket Structure |
|---|---|---|
| Bronze | Low (~$400 – $490) | High deductibles (~$5,800), high out-of-pocket maximums (~$9,800). Best for emergency protection. |
| Silver | Moderate (~$601 – $640) | Moderate deductibles (~$5,200) and copays. Eligible for additional cost-sharing reductions. |
| Gold | High (~$700 – $800) | Low deductibles, low copays. Great for regular medical visits. |
| Platinum | Very High (~$900+) | No deductibles, lowest copays. Designed for high healthcare utilization. |
How Subsidies and Financial Assistance Work in 2026
The true cost of your health insurance depends heavily on your eligibility for financial assistance. Subsidies are calculated using your Modified Adjusted Gross Income (MAGI) relative to the Federal Poverty Level (FPL).
- Premium Tax Credits: Generally, individuals earning between 100% and 400% of the FPL (roughly $14,580 to $58,320 for an individual) qualify for sliding-scale subsidies. Because California has a high cost of living, the state also utilizes its own state-allocated funds to extend these subsidies, helping middle-income families who might otherwise fall victim to the “subsidy cliff.”
- Cost-Sharing Reductions (CSRs): If your income is below 250% of the FPL and you choose a Silver plan, you automatically qualify for CSRs. These reductions lower your deductible, copays, and out-of-pocket maximums. In some cases, a Silver plan with CSRs can offer a lower deductible than a Platinum plan, making it the absolute best value on the market.
How to Compare California Health Insurance Quotes Online
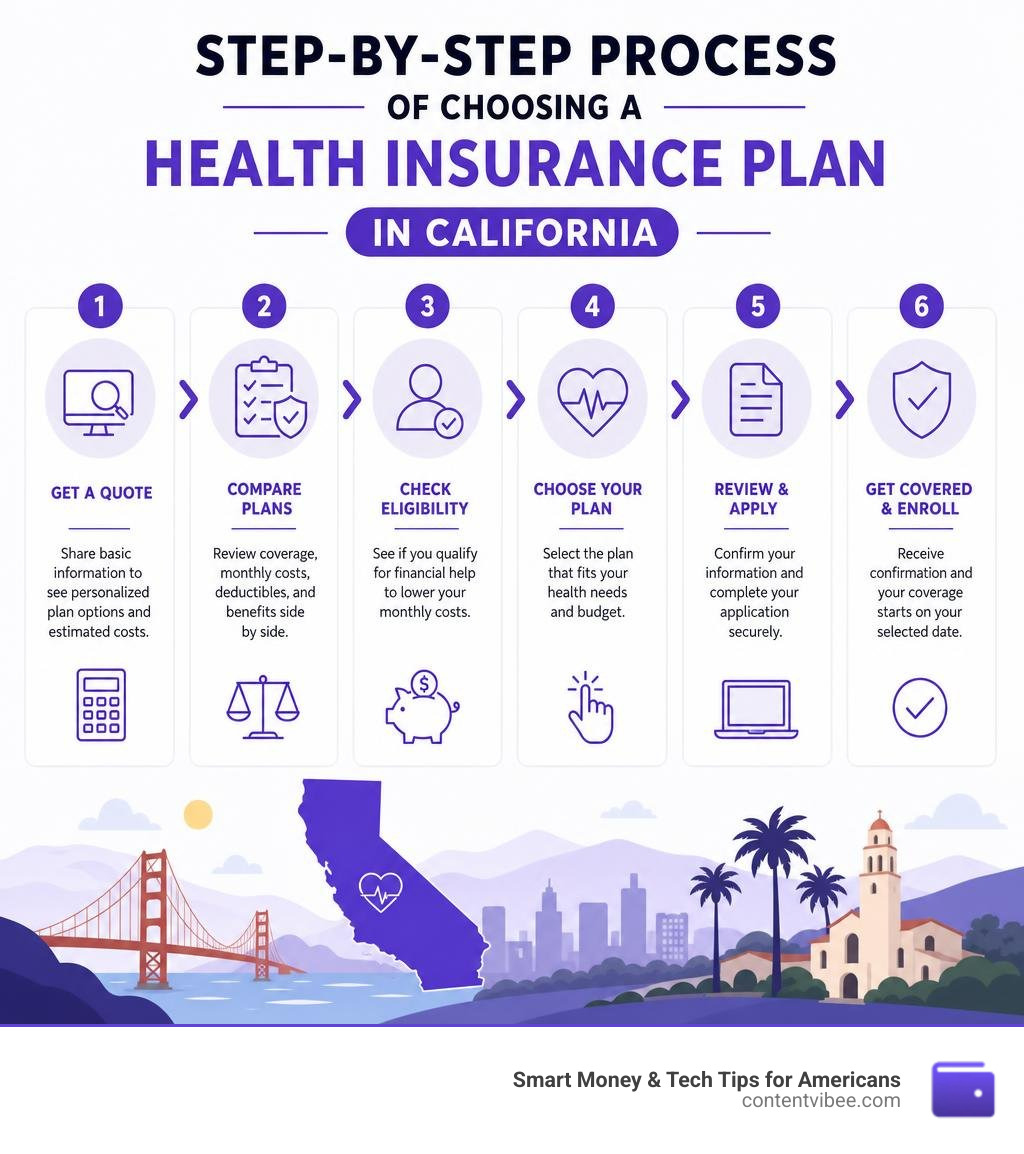
Shopping for coverage online has become incredibly streamlined. To make the process as smooth as possible, it helps to understand the mechanics of enrollment by visiting The Easiest Way to Enroll in Health Insurance.
Factors That Influence Your California Health Insurance Quotes
When you request quotes, insurance companies cannot look at your medical history or pre-existing conditions. Instead, your premium is determined by a few standardized factors:
- Age: Under the ACA, insurers use a 3:1 rating ratio. This means the oldest adults can be charged up to three times more than the youngest adults. Children under 21 are rated at a flat, lower rate.
- Geographic Rating Area: California is divided into 19 distinct rating areas. Medical costs vary by region, meaning a resident in Los Angeles will likely receive different quotes than someone living in Redding or San Francisco for the exact same plan.
- Tobacco Use: Insurers can apply a tobacco surcharge of up to 50% to your premium. Crucially, this surcharge does not qualify for premium subsidies, meaning you must pay the entirety of the tobacco penalty out of pocket.
- Household Income: While income does not change the “base price” of a plan, it directly dictates the size of your subsidy, which dramatically alters your final net premium.
Where to Request California Health Insurance Quotes
To get an accurate, comprehensive look at your options, you should utilize trusted platforms:
- State-Certified Portals: You can easily request personalized, direct comparisons through Individual & Family Health Insurance Quotes in California. These tools allow you to input your household size, ages, and estimated income to see exactly how much financial assistance you qualify for in real-time.
- Licensed Health Insurance Brokers: Working with a certified agent is completely free and can save you hours of research. A broker can help you check whether your preferred doctors, specialists, and hospitals are in-network for the plans you are considering. They can also assist you in analyzing recent carrier updates — such as reviewing Blue Shield of California’s network or keeping in mind their early 2026 data privacy incident notification — to ensure your personal data and health coverage remain secure.
Enrollment Windows and the Individual Mandate Penalty
Timing is everything when it comes to health insurance. If you do not sign up during the designated periods, you could find yourself without coverage and facing financial penalties. To understand how these monthly costs fit into your long-term budget, take a look at The Ins and Outs of Health Insurance Cost Per Month.
Open Enrollment and Special Enrollment Periods
For 2026 coverage, the standard Open Enrollment Period (OEP) runs from November 1 through January 31.
- If you enroll by December 15, your coverage will begin on January 1.
- If you enroll between December 16 and January 31, your coverage will begin on February 1.
If you miss the January 31 deadline, you cannot buy an ACA-compliant plan during the rest of the year unless you qualify for a Special Enrollment Period (SEP). SEPs are triggered by qualifying life events, which include:
- Losing job-based health coverage
- Getting married or divorced
- Having a baby or adopting a child
- Moving permanently to a new rating area within California
- A significant change in income that affects your subsidy eligibility
Generally, you have 60 days from the date of the qualifying event to sign up for a plan.
California’s Individual Mandate Penalty
California is one of a handful of states that enforces its own individual mandate. This means that all residents are required by state law to maintain qualifying health coverage throughout the year.
If you go without coverage and do not qualify for an exemption, you will face a penalty when you file your California state tax return. The penalty is calculated based on your household size and income. For an individual, the penalty starts at a minimum of $850 and can climb significantly higher for families or higher-income households. Paying for a subsidized Bronze plan is often cheaper than paying the state penalty and receiving absolutely no medical coverage in return.
Frequently Asked Questions about California Health Insurance
What is the average cost of health insurance in California?
The average individual premium in California is approximately $601.74 per month. For a standard Silver plan, the average cost sits around $640 per month before subsidies. However, if you qualify for federal and state financial assistance, your actual monthly payment could be significantly lower — sometimes even $0 per month depending on your household income and location.
Can I get health insurance in California without a job?
Yes. If you are unemployed, you have several excellent options in California. Depending on your income, you may qualify for Medi-Cal (California’s Medicaid program), which provides free or low-cost coverage to individuals earning at or below 138% of the FPL. Alternatively, you can purchase a plan through Covered California, where your lower income will likely qualify you for substantial premium subsidies to keep your coverage highly affordable.
What happens if I miss the open enrollment deadline?
If you miss the January 31 open enrollment deadline, you will not be able to purchase a standard health insurance plan for the remainder of the year unless you experience a qualifying life event (such as moving, losing job-based insurance, or having a baby). Additionally, going without coverage puts you at risk of paying California’s individual mandate tax penalty when you file your state taxes.
Conclusion
Finding the right health insurance plan doesn’t have to be a headache. By comparing california health insurance quotes early, understanding the differences between network types like HMOs and PPOs, and checking your eligibility for state and federal subsidies, you can secure comprehensive coverage that keeps both your body and your wallet healthy.
At ContentVibee, we specialize in breaking down complex personal finance and insurance topics to help U.S. audiences make smart, informed decisions. Take control of your financial wellness today!