

Is Retirement Affiliate Marketing Income Right for You?
Retirement affiliate marketing income is money you earn by recommending other companies’ products online — and it’s one of the most flexible, low-risk ways for retirees and near-retirees to bring in extra cash without a traditional job.
Here’s a quick snapshot of what you need to know:
- What it is: You share a special link to a product. Someone clicks it and buys. You earn a commission — typically 1–40% depending on the niche.
- What it costs to start: As little as $50–$100 per year for a domain and web hosting.
- How long before income arrives: Most people see their first commissions within 3–6 months of consistent publishing.
- Realistic monthly income by month 12: $1,000–$3,500 with around 200 published articles.
- Does it affect Social Security? Only before your full retirement age, and only if you earn above $23,400 per year (2026 limit).
- Do you need tech skills? No. Basic writing and a simple WordPress site are enough to get started.
The appeal is simple: you’re not managing inventory, answering customer service emails, or punching a clock. One retiree described it this way — imagine sitting on a beach and getting a notification that you just earned an $80 commission. That’s the potential of a well-built affiliate site.
The affiliate marketing industry topped $15.7 billion in 2026, and over 35% of affiliates on major networks earn more than $20,000 a year. Retirees, in particular, have a structural advantage: decades of real expertise, time to build content carefully, and the financial patience to let results compound.
This guide walks you through everything — how it works, what to expect, how to start, and what the tax rules mean for your Social Security and Medicare.
What is Affiliate Marketing and How Does It Work for Seniors?
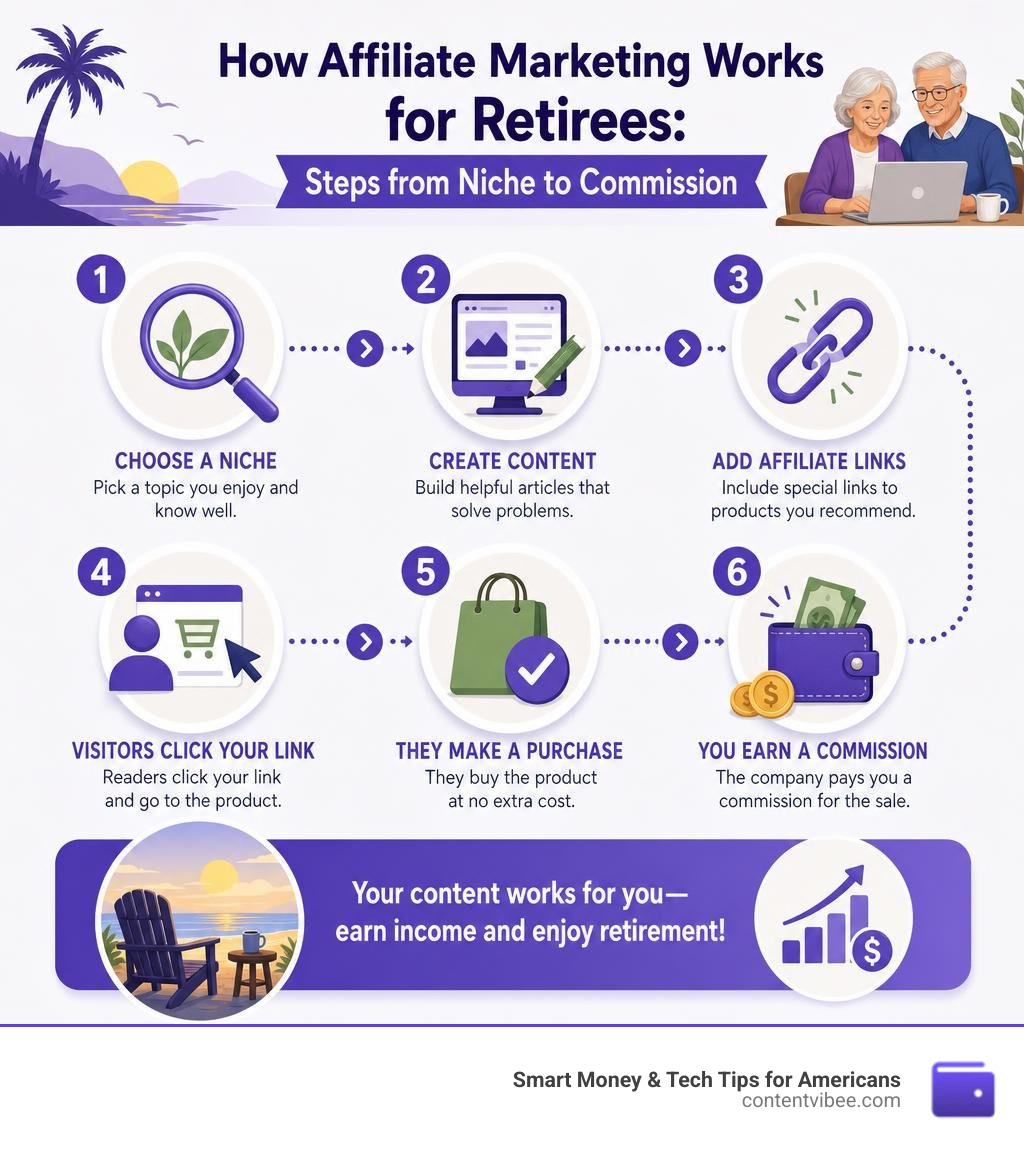
At its core, affiliate marketing is the digital equivalent of recommending a great local mechanic or a fantastic new lawnmower to your neighbor. The only difference is that when your online reader acts on your recommendation, the company pays you a referral fee.
For seniors, this model acts as a “digital bridge,” transforming your lifetime of accumulated wisdom, career knowledge, and personal hobbies into a steady stream of retirement affiliate marketing income.
To understand the model, you only need to understand three main roles:
- The Merchant: The company selling the product (e.g., Amazon, Home Depot, or a specialized medical alert company).
- The Affiliate (You): The trusted reviewer who recommends the product on a blog, newsletter, or social media page.
- The Customer: The reader who values your honest opinion, clicks your link, and makes a purchase.
The beauty of this system is what you don’t have to do. You do not have to design products, buy inventory, lease warehouse space, ship boxes, handle credit card transactions, or deal with angry customers. Once you place your affiliate links into your content, the merchant handles 100% of the operational heavy lifting. Your only job is to provide honest, helpful advice that connects a reader’s problem with a reliable solution.
Commission rates vary widely. If you recommend physical items on Amazon, you might earn 1% to 3% per sale. However, if you recommend digital products, online courses, or specialized software, commission rates can jump to 10% to 50% or more. Some services even pay recurring monthly commissions for as long as the customer stays subscribed.
The Mechanics of Earning a Retirement Affiliate Marketing Income
When you join an affiliate program, the merchant provides you with unique referral links. These links contain a special tracking code that belongs only to you. When a reader clicks that link, a tiny, harmless file called a “cookie” is saved on their device.
This cookie serves two vital functions:
- Cookie Duration: Also known as “cookie life,” this is the window of time you have to earn a commission. For example, Amazon has a 24-hour cookie, meaning if a reader clicks your link and buys anything within 24 hours, you get paid. Other programs offer 30-day, 90-day, or even “lifetime” cookies, which are fantastic for older shoppers who like to take their time researching purchases.
- Tracking: It ensures that even if the customer leaves the site and comes back to buy the product a few days later, the system still credits your account.
To make earning a retirement affiliate marketing income as simple as possible, you will want to choose established online networks. Instead of managing dozens of individual corporate accounts, you can join aggregated networks like ShareASale, CJ Affiliate, Impact, and FlexOffers. These networks group thousands of brands under one roof, making it incredibly easy to track your clicks, manage your links, and receive your payouts.
Most programs have payout thresholds, typically ranging from $25 to $100. Once your accumulated commissions hit this limit, the network sends your money directly to your bank account via direct deposit.
Why Affiliate Marketing is the Perfect Fit for Retirees
Most people who attempt affiliate marketing fail. However, they don’t fail because the business model is broken; they fail because they run out of time, money, or patience. They are often young professionals trying to build a business in the evenings while balancing a 9-to-5 job, a mortgage, and young children. By month five, exhausted and seeing only a few dollars in returns, they quit.
Retirees are structurally positioned for success in ways younger creators can only dream of. You possess three “unfair advantages” that make you the perfect fit for this industry:
- Time Abundance: While a working-age marketer struggles to find 5 hours a week, retirees often have 40+ hours of discretionary time. You only need 10 to 15 hours a week to build a highly successful affiliate site.
- Financial Patience: Because you likely have Social Security, a pension, or a retirement nest egg covering your basic living expenses, you do not need your website to pay your mortgage next month. This allows you to focus on building long-term value.
- The E-E-A-T Advantage: Google’s search ranking algorithms evaluate content based on E-E-A-T (Experience, Expertise, Authoritativeness, and Trustworthiness). Google specifically rewards firsthand, real-world experience. If a 22-year-old AI writer reviews a medical alert device, Google knows it’s fake. But if a retired nurse reviews that same device based on decades of professional experience, Google ranks it at the top. Your real life experience cannot be faked by AI.
Evaluating the return on investment (ROI) for retirees is highly favorable. The financial risk is virtually non-existent because your startup costs are equivalent to a few cups of coffee. The lifestyle ROI is equally high: it provides daily intellectual stimulation, a sense of creative purpose, and a way to stay connected with the modern digital world.
For many seniors, this venture represents the perfect retirement gig. It keeps your mind sharp, lets you share your passions, and funds your travel or hobbies.
Comparing Affiliate Income to Traditional Retirement Options
When looking for extra cash to supplement a fixed income, many seniors default to traditional options like retail work, consulting, or driving for a ride-share service. While these options provide immediate cash, they come with significant drawbacks, including physical wear and tear, rigid schedules, and exposure to public stress.
Let’s compare these options side-by-side:
- Physical Labor vs. Comfort: Traditional part-time jobs require you to stand on your feet, commute in bad weather, or lift heavy boxes. Affiliate marketing is done entirely from the comfort of your favorite armchair, on your own schedule.
- Active Income vs. Scalable Leverage: With a part-time job, you are trading hours for dollars. If you don’t work, you don’t get paid. With affiliate marketing, you do the work once — writing a helpful article — and that article can continue to generate commissions 24 hours a day, 7 days a week, for years to come.
- Risk vs. Reward: Starting a physical business (like a coffee shop or boutique) requires thousands of dollars in upfront capital. If the business fails, your retirement nest egg is severely damaged. Conversely, our guide on Alternative Ways to Save for Retirement That Actually Work outlines how digital assets carry almost zero financial risk.
If you are currently relying on retirement calculators or the traditional 4% rule to manage your cash flow, you know that keeping your nest egg secure is a delicate balancing act. To see how even a modest monthly side-income can completely alter your financial safety margin, check out our guide on Demystifying the 4 Percent Retirement Withdrawal Calculator.
Realistic Expectations: What is a Typical Retirement Affiliate Marketing Income?
Let’s cut through the internet hype: you are not going to make $10,000 next week. Affiliate marketing is a compounding asset, much like a garden. You plant seeds (write articles), water them (build traffic), and eventually harvest the crops (earn commissions).
What does a realistic, sustainable timeline look like for a retiree putting in 10 to 15 hours a week? The table below outlines a typical 24-month trajectory for a niche site built on genuine, expertise.
| Timeframe | Monthly Visitors | Estimated Monthly Income | Focus & Milestones |
|---|---|---|---|
| Months 1–3 | 200 – 800 | $0 – $75 | Setting up the site, writing the first 20–30 articles, getting indexed by Google. |
| Months 4–6 | 2,000 – 6,000 | $100 – $500 | Traffic begins to grow. First consistent sales and commission notifications arrive. |
| Months 7–9 | 6,000 – 15,000 | $400 – $1,500 | Google begins trusting your site. Older articles start ranking higher. |
| Months 10–12 | 15,000 – 40,000 | $1,000 – $3,500 | The “Snowball Effect” takes over. You have ~200 helpful articles driving steady daily sales. |
| Months 18–24 | 40,000 – 80,000+ | $2,500 – $7,000+ | A mature digital asset. High-value niches can scale to five figures per month. |
Your startup costs are incredibly low. You do not need expensive software, fancy office equipment, or high-priced consultants. Your ongoing monthly expenditures will likely look like this:
- Domain Name: $12 to $15 per year.
- Web Hosting: $5 to $15 per month (using reliable, beginner-friendly hosts like SiteGround or Bluehost).
- Email Marketing Platform: Free to $15 per month initially.
To protect your budget, keep your expenses lean. Do not buy unnecessary tools or jump from niche to niche.
Timeline to Your First Retirement Affiliate Marketing Income Commission
The first 90 days are all about laying a solid foundation. During this period, you will choose your topic, set up your simple website, and write your first dozen articles. It is completely normal to see zero income during this phase. This is when most beginners quit, but as a retiree with financial patience, you can easily cruise through this initial quiet period.
By month six, your content will begin to gain traction. You will start seeing daily visitors, and those visitors will begin clicking your links. When that first commission notification pops up — even if it is only for $4.50 — it is an incredibly exciting moment. It proves that the system works.
As you head toward your 12-month mark, consistency is your best friend. By publishing just two helpful articles a week, you will have over 100 pages of high-quality content online by the end of your first year. This library of content builds deep audience trust and establishes a sustainable, reliable side hustle that can support you throughout your retirement years.
How to Get Started: Step-by-Step Setup and Best Niches
Ready to build your digital asset? You do not need to be a programmer or a web designer. In 2026, building a website is as simple as writing an email.
Here is our simple, step-by-step setup guide:
- Secure Your Domain and Hosting: Your domain is your website address (e.g., ActiveSeniorGolf.com). Your hosting is the digital plot of land where your website lives. Go to a trusted provider like SiteGround, select their basic hosting plan, and register your domain name. This process takes less than 15 minutes.
- Install WordPress: WordPress is the world’s most popular, free website-building platform. Most hosting companies offer a “One-Click WordPress Installation” button. Click it, choose your password, and your site is live.
- Choose a Clean Theme: Select a free, fast-loading design theme like Astra or GeneratePress. Keep it clean, simple, and easy to read.
- Install Three Essential Plugins: Plugins are like apps for your website. You only need three to start:
- Yoast SEO (to help your articles show up on Google).
- WP Super Cache (to keep your site loading fast).
- ThirstyAffiliates (to easily organize your affiliate links).
- Write Your “About” Page: This is your secret weapon. Explain who you are, highlight your decades of experience, and show your readers why they can trust your recommendations.
High-Value Niches for Older Adults
The best niche is one where you already have personal experience, interest, or professional knowledge. Here are five high-value niches where seniors have a natural, massive advantage:
- Health and Wellness (10% to 30% Commissions): Recommending ergonomic garden tools, comfortable walking shoes, home fitness equipment, or natural supplements. Your peers value honest, age-appropriate health recommendations.
- Senior Travel (8% to 40% Commissions): Writing about RV living, slow travel in Europe, packing guides for seniors, or cruise reviews.
- Financial Planning and Insurance (High Payouts per Lead): Helping peers understand estate planning tools, software for budgeting, or Medicare comparison guides.
- Hobbies and Crafts (5% to 15% Commissions): Deep dives into woodworking, quilting, oil painting, or vintage restoration.
- Outdoor Recreation (5% to 15% Commissions): Reviewing golf clubs, fly-fishing gear, bird-watching binoculars, or camping equipment.
Tax Implications and Legal Requirements for Retirees
Earning a retirement affiliate marketing income is a wonderful feeling, but you must treat it like a real business. In the eyes of the IRS, your affiliate commissions are considered self-employment income. For official guidance on reporting self-employment income and estimated taxes, review the IRS resource for Self-Employed Individuals Tax Center.
Here is what you need to keep in mind:
- Schedule C and Self-Employment Tax: You will report your affiliate earnings on Schedule C of your Form 1040. If your net earnings exceed $400, you will be subject to the 15.3% self-employment tax (which covers Social Security and Medicare taxes).
- The QBI Deduction: Thanks to tax laws, you may qualify for the Qualified Business Income (QBI) deduction. This allows you to deduct up to 20% of your net business income right off the top before paying regular income tax.
- Write-Offs and Deductions: Because you are running a business, you can deduct your business expenses. This includes your web hosting fees, domain registrations, software subscriptions, home office space, and even the cost of the products you buy to test and review.
- FTC Disclosures: The Federal Trade Commission (FTC) requires you to clearly disclose your relationship with affiliate brands. You must place a simple, clear disclosure at the top of every page where you use affiliate links (e.g., “If you click a link on this page and make a purchase, we may earn a small commission at no extra cost to you.”).
To learn more about optimizing your retirement income and tax strategies, read our guide on After-Tax Contributions: How to Maximize Your Retirement Nest Egg.
Social Security and Medicare Considerations
If you are earning affiliate income, you must understand how it interacts with your government benefits.
- The Social Security Earnings Test: If you have already reached your Full Retirement Age (FRA) — which is 67 for anyone born in 1960 or later — there is no limit on how much you can earn. Your benefits will not be reduced. However, if you claim Social Security before your FRA, the earnings test applies. In 2026, the earnings limit is $23,400. If you earn more than this, Social Security will withhold $1 in benefits for every $2 you earn over the limit.
- Medicare IRMAA Thresholds: If your Modified Adjusted Gross Income (MAGI) exceeds certain thresholds ($103,000 for single filers or $206,000 for married couples in 2026), you may trigger the Income-Related Monthly Adjustment Amount (IRMAA) surcharge. This increases your Medicare Part B and Part D monthly premiums. Keep an eye on your net earnings to ensure you don’t accidentally cross these thresholds.
To make sure you are claiming your benefits at the absolute best time, read The Definitive Guide to Social Security Claiming Age and brush up on how to calculate your exact numbers with How to Calculate Your Social Security Benefit in 5 Simple Steps.
Frequently Asked Questions about Retirement Affiliate Marketing
Do I need to be a tech wizard to start affiliate marketing?
Absolutely not. In 2026, the entire internet runs on “no-code” tools. If you can write an email, use Microsoft Word, or post on Facebook, you have all the technical skills required to run an affiliate website. Modern platforms have simplified the process down to simple, click-and-type menus.
How much money do I need to start?
You can start for less than $100. All you need is a domain name (about $12 per year) and a basic web hosting plan (about $5 to $10 per month). You do not need to buy expensive courses, premium themes, or high-priced keyword research tools when you are first starting out.
Can I do affiliate marketing without showing my face?
Yes! These are known as “Faceless Authority” sites. Many successful retiree affiliates write under a pen name or simply focus the website entirely on the topic rather than themselves. You can build a highly profitable site using only written articles, comparison tables, and email newsletters, without ever having to record a video or show your face on camera.
Conclusion
Building a retirement affiliate marketing income is about much more than just adding a few hundred or a few thousand dollars to your monthly bank account. It is about maintaining your financial independence, keeping your mind sharp, and sharing your lifetime of valuable experience with a world that desperately needs authentic, human-verified advice.
At ContentVibee, we believe that retirement should be an active, fulfilling, and financially secure chapter of your life. You do not have to let inflation or fixed pensions dictate your lifestyle. By spending just a few hours a week building a simple, honest affiliate website, you can create a digital asset that supports your retirement goals for years to come.
Before you take your first steps, make sure you understand how earning an income in retirement might affect your household benefits. Learn how working in retirement affects your spousal benefits to ensure your new digital venture is fully optimized for your family’s financial future.


