Why Retirement Consulting Opportunities Are Booming Right Now
Retirement consulting opportunities are growing fast — and for people with financial services experience, they offer one of the most flexible ways to keep earning after a traditional career winds down.
Here’s a quick look at what’s available right now:
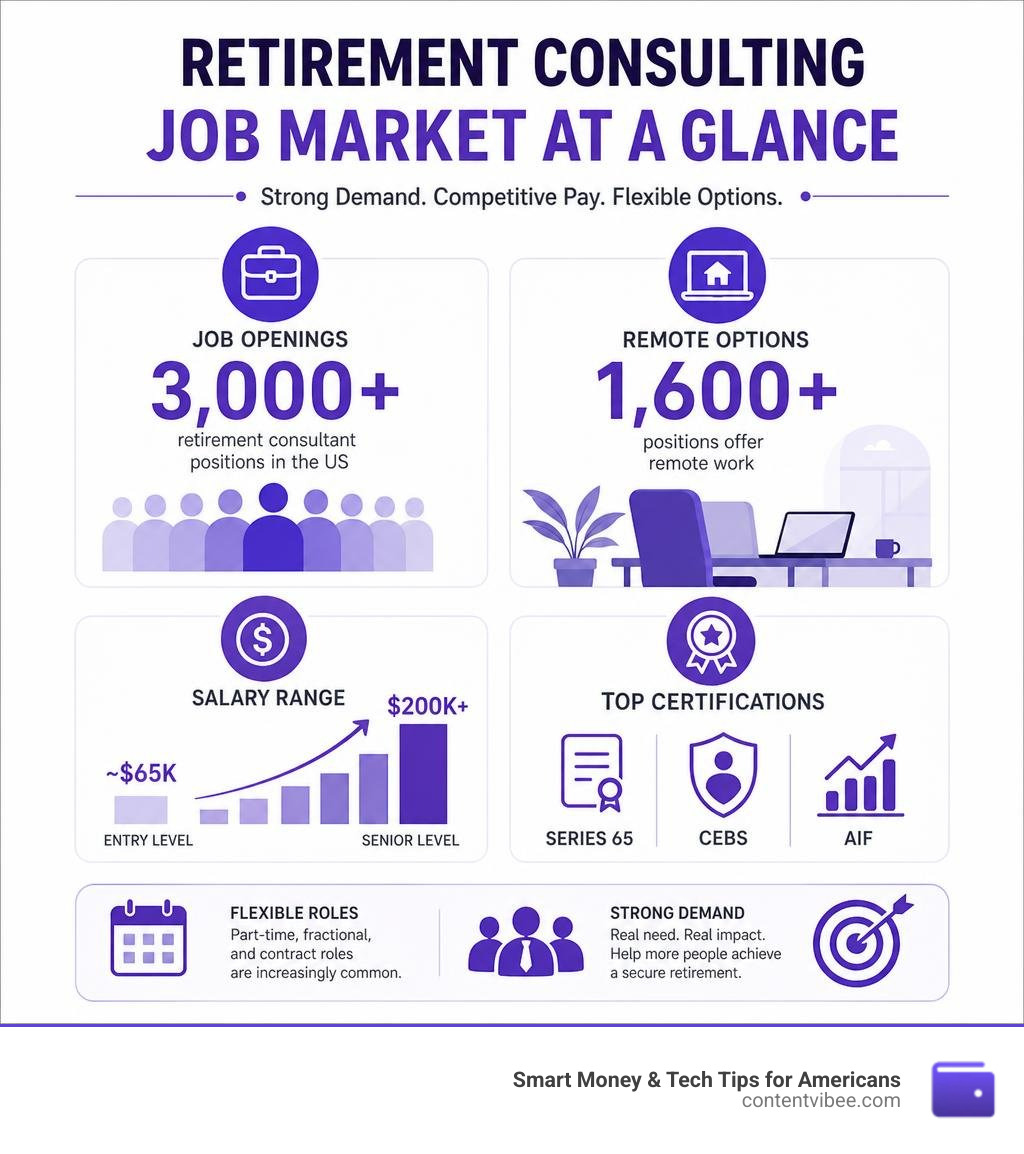
| What You Want to Know | Quick Answer |
|---|---|
| How many jobs are available? | 3,000+ retirement consultant positions listed in the US |
| Can you work remotely? | Yes — over 1,600 positions offer remote work |
| What’s the pay range? | From ~$65K entry-level to $200K+ at senior levels |
| Do you need certifications? | Yes — Series 65, CEBS, or AIF are common requirements |
| Can you work part-time or fractional? | Yes — fractional and contract roles are increasingly common |
| Who hires retirement consultants? | Firms like Marsh McLennan, Accenture, and boutique advisory practices |
The retirement plan industry is dealing with real pressure right now. Regulations keep changing, plan sponsors need fiduciary guidance, and millions of workers are underprepared for retirement. One striking figure: more than $2 trillion in potential future account balances could be lost over the next decade just from 401(k) loan defaults, according to Deloitte’s analysis.
That gap between what people have saved and what they need? That’s exactly where skilled retirement consultants come in.
If you’ve spent years in finance, HR, benefits administration, or financial planning, you already have a foundation. The field rewards deep expertise — and it increasingly rewards flexibility, too.
Exploring the Landscape of Retirement Consulting Opportunities
The demand for retirement plan expertise has reached an all-time high. As of June 2026, the job market is incredibly active. According to real-time hiring data, there are currently over 3,000 active listings on platforms like the 2,000+ Retirement Consultant jobs in United States – LinkedIn directory. This volume reflects a broader trend: employers are struggling to design benefits packages that attract top talent while keeping up with complex federal rules.
For experienced professionals, this demand translates into highly flexible post-retirement career options. You don’t have to commit to a grueling 60-hour corporate workweek to make a meaningful impact. Instead, you can leverage your accumulated knowledge to advise businesses on a project-by-project or fractional basis.
This pathway allows you to transition smoothly from full-time employment to self-directed consulting, helping organizations restructure their benefits packages. If you are looking to build a diversified post-retirement income stream, we highly recommend exploring Alternative Ways to Save for Retirement That Actually Work to see how consulting fits into a modern financial plan.
High-Demand Sectors for Retirement Consulting Opportunities
Not all retirement consulting roles are created equal. The market is broadly divided into several core sectors:
- Corporate Plans: Private companies need constant support managing their 401(k) and profit-sharing plans. Consultants evaluate plan performance, review fee structures, and recommend lower-cost investment lineups.
- Public Sector and Non-Profits: Government entities and school districts manage unique retirement vehicles like 403(b) and 457 plans. These organizations require specialized consultants who understand public-sector budgets and distinct tax rules.
- Multiemployer Pension Trusts: These complex plans, often managed jointly by labor unions and employer associations, require highly specialized expertise. For example, roles like those found in the Senior Consulting Actuary – Pension – Hybrid | Hirro listing focus heavily on multiemployer pension plan governance, collective bargaining dynamics, and complex withdrawal liability calculations.
Remote and Fractional Retirement Consulting Opportunities
One of the most appealing aspects of the modern consulting landscape is the sheer volume of flexible work arrangements. Out of the 3,000+ active retirement consultant listings in the United States, more than 1,600 explicitly offer remote work options.
This shift toward remote and fractional consulting means you can service clients across the country from your home office. Many senior professionals transition into these roles to enjoy a better work-life balance without sacrificing their earning power. For instance, positions like the Senior Retirement Plan Consultant | Hireza role show that firms are actively looking for remote consultants to own client relationships, design customized plan structures, and deliver virtual fiduciary training.
Core Responsibilities and Plan Designs in Retirement Consulting
At its core, retirement plan consulting is about helping organizations build benefits programs that balance two competing priorities: keeping corporate costs sustainable and helping employees build genuine financial security. It is a highly analytical field that requires a deep understanding of tax law, investment products, and behavioral finance.
If you are consulting in this space, you will spend a significant amount of time assessing whether a client’s plan design aligns with their broader business goals. For executives and high earners, this might mean designing specialized plans. If you want to understand how these unique structures function, check out our guide on Demystifying the 457 Deferred Compensation Plan: Your Golden Ticket to Early Retirement.
Designing and Managing Diverse Retirement Plans
As a consultant, you will work with a wide array of retirement plan structures. Your job is to help the employer choose the right vehicle for their workforce demographics and capital constraints.
| Plan Type | Primary Advantages | Key Compliance Considerations | Best Suited For |
|---|---|---|---|
| Defined Contribution (401k/403b) | Predictable employer costs; highly portable for employees. | Subject to strict annual nondiscrimination testing (ADP/ACP). | Almost all corporate and non-profit employers. |
| Defined Benefit (Traditional Pension) | Offers guaranteed lifetime income; strong retention tool. | Requires complex actuarial funding calculations and PBGC premiums. | Public sector, utilities, and older, established industries. |
| Employee Stock Ownership Plan (ESOP) | Strengthens corporate capital structure; boosts employee engagement. | Highly complex valuation rules; requires independent annual appraisals. | Owners looking for succession planning and high employee alignment. |
| Cash Balance Plans | High contribution limits for owners; acts like a hybrid pension. | Must maintain a minimum funding standard; complex actuarial rules. | Highly profitable professional practices (doctors, attorneys). |
Experienced consulting groups, such as USI Consulting Group, which has been advising clients for 50 years, emphasize that there is no one-size-fits-all plan. A tech startup with a young, mobile workforce will require a vastly different retirement plan design than a manufacturing business with a highly stable, long-tenured employee base.
Optimizing Plan Performance and Reducing Costs
Many corporate retirement plans are quietly overcharged and under-serviced. One of the most impactful things a retirement consultant can do is conduct a comprehensive plan diagnostic to uncover hidden fees and underperforming assets.
Consultants use specialized tools to benchmark investment performance and analyze administration fees. By helping clients transition to lower-cost institutional share classes or simplifying their mutual fund lineups, consultants can drastically improve long-term participant outcomes. To help your clients understand how these professional services are priced, it is helpful to refer them to our breakdown on How to Read a Financial Planning Fee-Based Structure.
Navigating Compliance, Fiduciary Risk, and Regulatory Challenges
For plan sponsors, managing a retirement program is a legal minefield. Under the Employee Retirement Income Security Act (ERISA), plan administrators are held to the highest standard of professional care. If they make a mistake — such as allowing excessive investment fees or failing to deposit employee contributions on time — they can be held personally liable.
This regulatory pressure is why companies are willing to pay top dollar for expert guidance. Consultants act as a shield, helping plan sponsors establish clear, documented processes to mitigate fiduciary risk.
Fiduciary Duty and Risk Mitigation for Plan Sponsors
To protect clients from costly litigation, consultants focus heavily on establishing structured governance. This involves:
- Fiduciary Training: Educating corporate board members and HR executives on their legal responsibilities.
- Investment Committee Support: Organizing quarterly investment reviews and documenting why certain funds were selected or replaced.
- Plan Diagnostics: Reviewing total plan costs and benchmarking them against industry standards. Specialized retirement practices, such as the Retirement Plan Consulting | Forvis Mazars US group — which serves 700 clients with over $850 million in assets under advisement — emphasize that a simplified, well-documented investment lineup is often the best way to reduce fiduciary liability.
For a detailed look at the operational side of these roles, the Retirement Plan Consultant (2026) – Sentinel Group – Career Page outlines how consultants work directly with clients to manage annual valuations, compliance testing, and complex plan documentation.
Annual Compliance Testing and Reporting
Every year, qualified retirement plans must prove they do not unfairly favor highly compensated employees (HCEs) over rank-and-file workers. Retirement consultants oversee this technical compliance process, which includes:
- Nondiscrimination Testing: Running ADP/ACP tests and IRC 410(b) coverage testing.
- Form 5500 Preparation: Ensuring accurate financial reporting is submitted to the Department of Labor (DOL) and IRS.
- Corrective Actions: If a plan fails its annual testing, the consultant calculates the necessary corrective distributions or employer contributions to restore compliant status.
Firms look for specialists who can handle both the technical side of compliance and the client-facing side of plan optimization. This dual need is highly visible in roles like the Retirement Plan Consultant – Sales | Flexionis position, which combines technical ERISA compliance knowledge with consultative relationship management.
Qualifications, Career Growth, and Compensation Benchmarks
Whether you want to work as an independent contractor or join an established firm, having the right credentials is vital. Because retirement consulting involves legal, tax, and investment advice, plan sponsors expect a high level of verified expertise.
If you are planning out your post-retirement career transition, it is also important to align your working hours with your personal financial goals. For those wondering about the timeline of this transition, our guide on When Can You Stop Working and Retire in California offers valuable insights into balancing active work with retirement timelines.
Essential Certifications and Licensing
To stand out in the competitive consulting market, consider pursuing these highly respected industry designations:
- Certified Employee Benefit Specialist (CEBS): Widely considered the gold standard for total rewards and benefits professionals.
- Accredited Investment Fiduciary (AIF): Focuses specifically on fiduciary standards, investment management, and fee benchmarking.
- Enrolled Actuary (EA): Required for those who want to perform actuarial valuations for defined benefit plans.
- FINRA Series 65 or 66: Essential if you plan to provide direct investment advisory services to retirement committees.
Many large-scale consulting operations look for a blend of technical expertise and business transformation skills. For example, the Retirement Management Consultant role highlights the growing demand for professionals who can bridge the gap between financial services, software integration, and digital operating models.
Compensation and Earning Potential
Compensation in this field varies based on your experience, geographical location, and whether you work independently or for a firm.
- Entry to Mid-Level: Typically ranges from $65,000 to $85,000 annually. These roles focus primarily on plan administration, compliance testing, and day-to-day client support.
- Senior Consultants / Relationship Managers: Regularly command salaries between $100,000 and $150,000, often supplemented by performance bonuses.
- Director and Partner Levels: Can earn well over $200,000, especially in major metro markets like New York, Los Angeles, and Chicago.
If you prefer a corporate-aligned role that focuses on participant transitions, companies often hire specialized advisors to handle rollover assets. For example, the Retirement Consultant – Roll In at Empower position highlights opportunities centered on helping participants consolidate their retirement accounts, combining customer service with institutional asset retention.
How Technology and AI are Transforming Retirement Administration
The retirement consulting industry is undergoing a massive digital transformation. Historically, plan administration was a paper-heavy, manual process prone to human error. Today, automation and artificial intelligence are streamlining operations, allowing consultants to focus on high-value strategic advice rather than routine data entry.
Modern recordkeeping platforms use advanced automation to run daily valuations, process participant transactions, and monitor contribution limits in real time. Furthermore, AI-powered assistants are now being deployed on open enrollment websites to answer participant questions instantly, which dramatically reduces the volume of basic inquiries handled by corporate HR departments.
As a consultant, you will use these advanced technological tools to deliver deeper value to your clients. For example, you can use automated diagnostic software to instantly benchmark plan fees against thousands of similar plans, or use predictive modeling tools to show employers how minor changes to their matching formulas could boost overall participation.
To help individual participants visualize their future financial needs, we recommend sharing practical tools like our interactive Retirement Calculator: Estimate Savings Needed.
Frequently Asked Questions about Retirement Consulting
What does a retirement plan consultant do on a day-to-day basis?
On any given day, a retirement plan consultant might review investment performance reports, conduct fee benchmarking studies, or meet with a client’s investment committee to discuss fiduciary responsibilities. They also spend time reviewing draft plan amendments, coordinates with third-party administrators (TPAs) on compliance testing, and developing educational materials to help employees improve their savings habits.
Can I work as a retirement consultant on a part-time or remote basis?
Absolutely. The rise of fractional consulting and remote work has made this one of the most flexible fields for post-retirement careers. With over 1,600 remote positions currently active in the US, experienced professionals can easily find part-time, contract, or project-based opportunities that allow them to work on their own terms.
What are the most valuable certifications for entering this field?
The most valuable certifications depend on your specific focus. For investment and fiduciary consulting, the AIF (Accredited Investment Fiduciary) and Series 65 are highly sought after. For plan design, administration, and compliance, the CEBS (Certified Employee Benefit Specialist) or credentials from the ASPPA (American Society of Pension Professionals & Actuaries) are widely respected by employers and clients alike.
Conclusion
Transitioning into retirement doesn’t have to mean walking away from your professional life entirely. By exploring retirement consulting opportunities, you can leverage your hard-earned financial and corporate expertise to help organizations protect their plans and build secure futures for their workforces. This path gives you the ultimate professional luxury: the ability to do intellectually stimulating work on a flexible, self-directed schedule.
As you design your post-retirement career, make sure you understand how your ongoing consulting income might interact with other financial benefits. To ensure you are maximizing your household’s resources, we encourage you to Learn how working in retirement affects your spousal benefits.
With the right balance of expertise, certifications, and modern tools, you can build a highly rewarding, flexible consulting practice that funds your ideal lifestyle while keeping your professional mind sharp.