The One Question Every Pre-Retiree Needs to Answer Before Choosing a 401(k)
Using a 401k vs Roth calculator is the fastest way to see which retirement account puts more money in your pocket — after taxes.
Here’s the quick answer most people need:
| Your Situation | Best Choice |
|---|---|
| Current tax rate is lower than expected retirement rate | Roth 401(k) |
| Current tax rate is higher than expected retirement rate | Traditional 401(k) |
| Unsure about future tax rates | Split 50/50 |
| High earner ($150K+ single) wanting a deduction now | Traditional 401(k) |
| Early career, low income (under $80K single) | Roth 401(k) |
The core tradeoff is simple: Traditional 401(k) saves you taxes now but you pay them in retirement. Roth 401(k) costs more today but your money grows completely tax-free.
The hard part? Nobody knows exactly what their retirement tax rate will be. That’s where a calculator changes everything.
A real example makes this concrete. Take someone earning $95,000, contributing 10% a year, at a 22% current tax rate — if their retirement tax rate drops to 18%, the Roth option wins by $109,260 in after-tax wealth over 25 years. Flip the tax rates, and Traditional pulls ahead.
The math isn’t complicated. But getting the inputs right — your current bracket, your expected retirement income, Social Security, required distributions — takes more than a back-of-napkin guess.
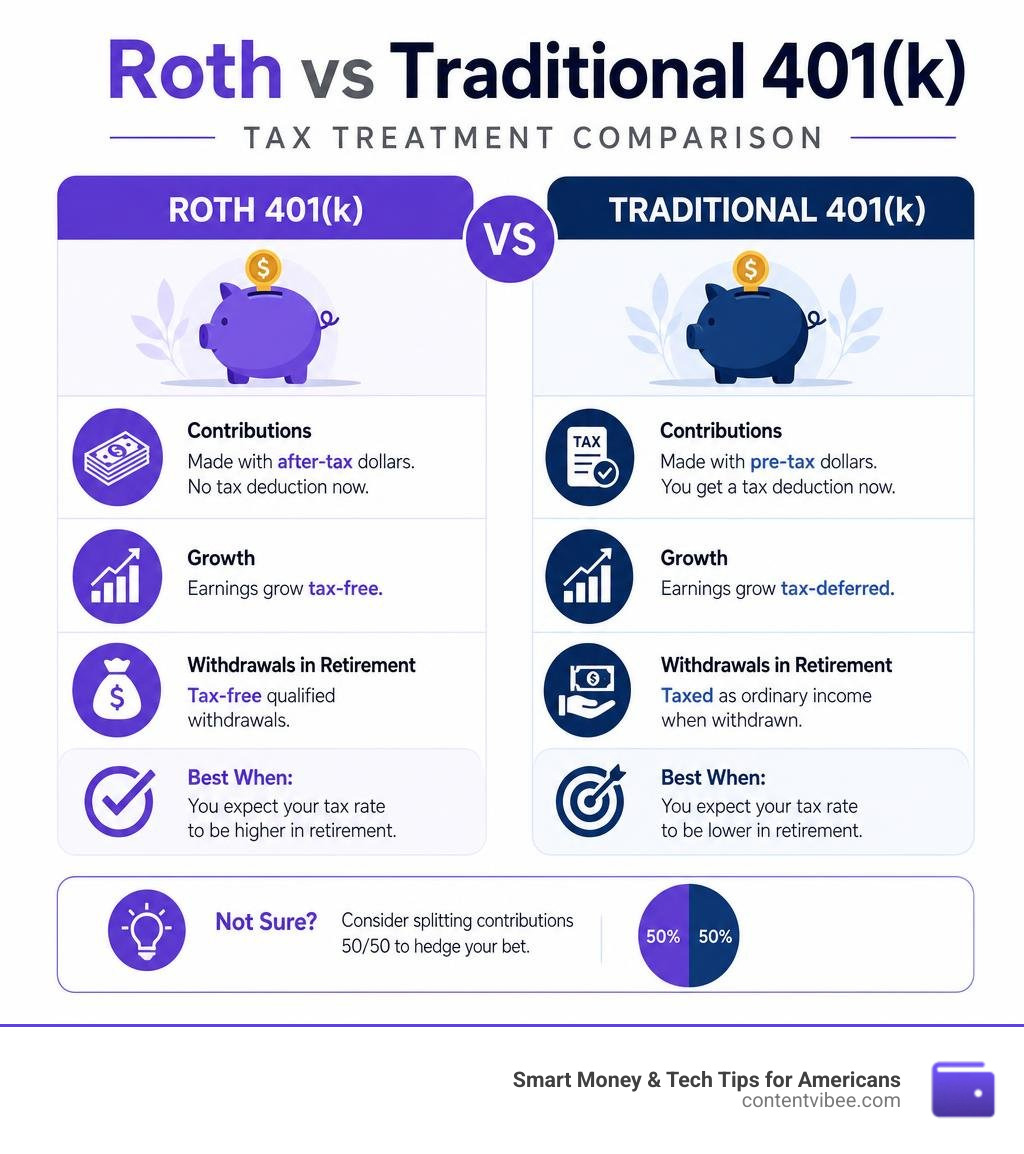
401k vs Roth calculator word roundup:
Traditional vs Roth 401(k): The Core Tax Battleground
When you peel back the layers of retirement planning, the choice between a Traditional 401(k) and a Roth 401(k) comes down to a single, crucial battleground: taxes. Both accounts are designed to help you build a massive nest egg, but they go about it in opposite ways.
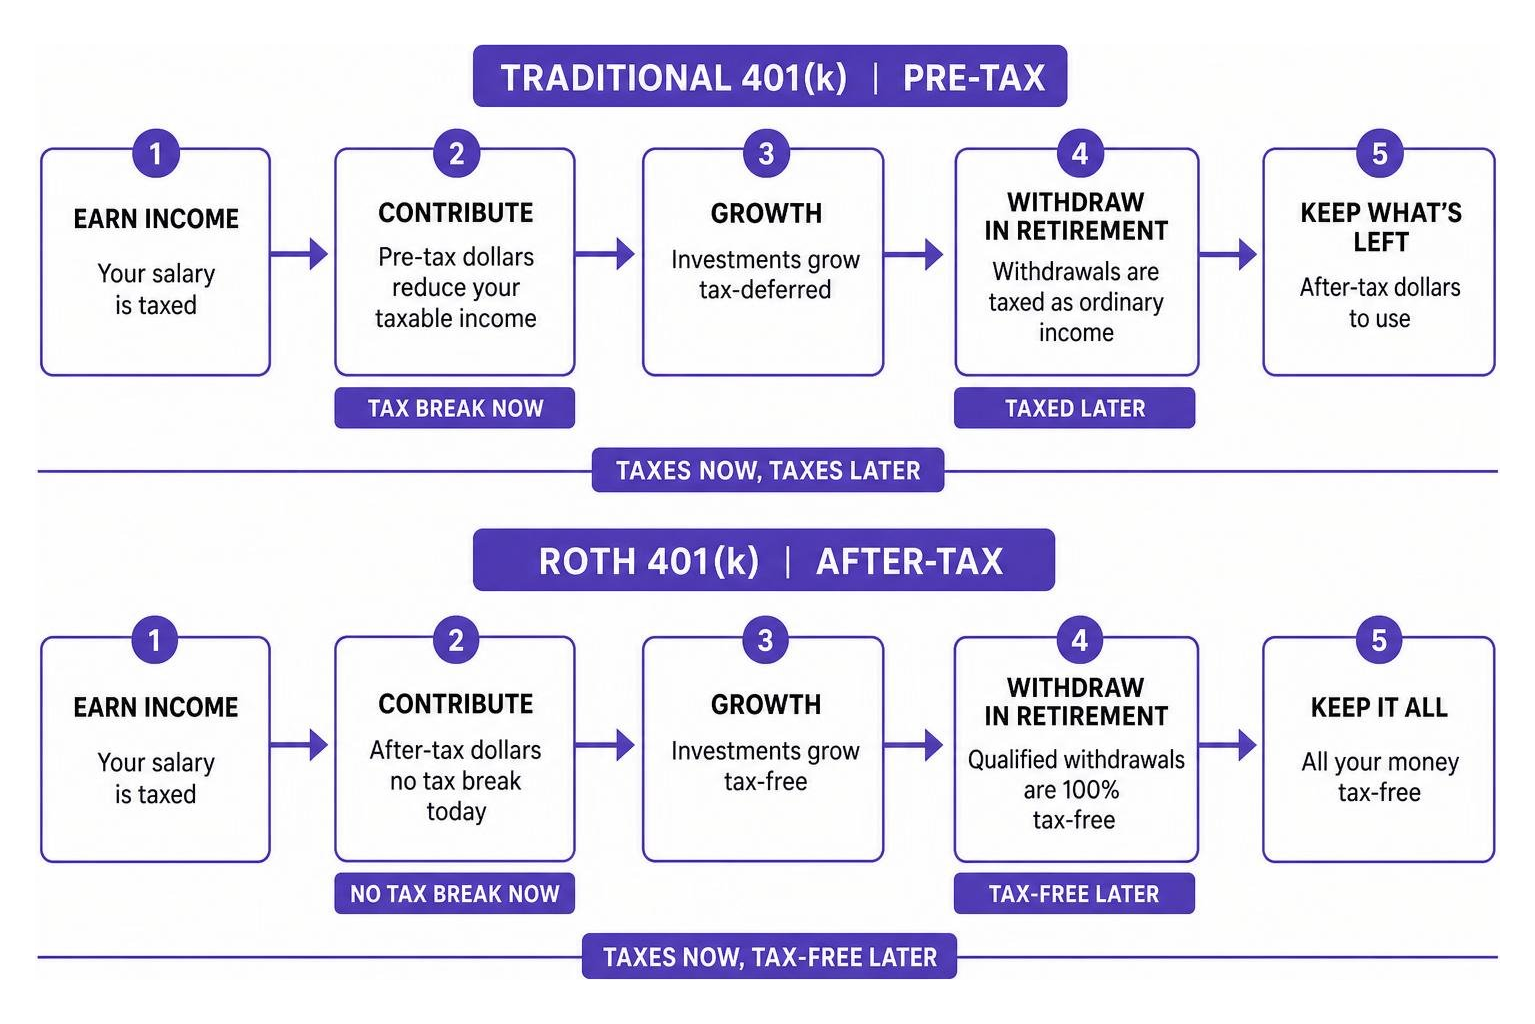
With a Traditional 401(k), your contributions are made with pre-tax dollars. This is a massive win for your current wallet because it reduces your adjusted gross income (AGI) for the year. If you put $10,000 into a Traditional 401(k) today, that is $10,000 of your income that Uncle Sam cannot touch this tax season. However, there is a catch. When you finally stop working and begin taking withdrawals in retirement, every single dollar you pull out is taxed as ordinary income. You are essentially deferring your tax bill to a future version of yourself.
With a Roth 401(k), the script is completely flipped. You make contributions with after-tax dollars. This means you do not get an upfront tax break today; your paycheck feels the full weight of your contribution. But the payoff down the road is spectacular. Once you reach retirement, all of your qualified withdrawals—including every penny of the compound interest and investment growth you accumulated over decades—are 100% tax-free.
To help you visualize this choice, we can look at the path your money takes:
If you want to maximize your current cash flow while keeping an eye on your long-term plan, implementing smart strategies to defer taxes and boost your retirement savings is the best way to keep your financial plan optimized.
2026 Contribution Limits and RMD Rules
Because it is currently July 2026, we have to look at the latest IRS guidelines to understand how much you can actually pack into these accounts. For 2026, the employee elective deferral limit is $24,500 for both Traditional and Roth 401(k) accounts.
If you are age 50 or older, you can take advantage of catch-up contributions to accelerate your savings. The catch-up limit for 2026 is $7,500, bringing your total allowed contribution to $31,000. Additionally, thanks to the SECURE Act 2.0, there are “super catch-up” provisions for workers aged 60 to 63, allowing an even higher catch-up limit of $11,250 (a total of $35,750) in 2026.
Historically, one of the biggest drawbacks of the Roth 401(k) compared to a Roth IRA was the issue of Required Minimum Distributions (RMDs). Under older tax laws, Roth 401(k) owners were forced to take minimum withdrawals starting at age 73, even though the money was tax-free. Fortunately, the SECURE Act 2.0 eliminated lifetime RMDs for Roth 401(k) accounts. Now, your Roth 401(k) can sit and grow completely untouched for as long as you live, putting it on equal footing with the Roth IRA for long-term estate planning.
Tax Treatment of Withdrawals
The way your withdrawals are handled in retirement will define your standard of living.
- Traditional 401(k) Withdrawals: These are treated as ordinary income. If you withdraw $80,000 in a year to fund your travels, the IRS treats that $80,000 exactly as if you earned it working a 9-to-5 job. It will be subject to federal, state, and local income taxes based on whatever the tax brackets look like decades from now.
- Roth 401(k) Withdrawals: These are entirely tax-free, provided you are at least 59½ years old and have held the account for at least five years. If you withdraw $80,000 from a Roth 401(k), you keep exactly $80,000.
This difference is why using a robust comparison tool is so important. If you want to run the numbers yourself, you can try the Roth 401(k) vs. Traditional 401(k) Calculator to see how these withdrawal taxes impact your actual spendable wealth.
How to Use a 401k vs Roth Calculator to Find Your Break-Even Tax Rate
To truly understand which account type wins, you have to look past the basic “tax now vs. tax later” rule of thumb. You need to find your break-even tax rate.
A 401k vs Roth calculator works by taking your current salary, contribution rate, investment timeline, and expected rate of return, and projecting two parallel futures. In one future, you take the tax savings from your Traditional 401(k) and reinvest them. In the other, you pay the tax upfront and let the Roth grow.
Let’s look at a side-by-side comparison of how a typical calculator models these scenarios over a 25-year career:
| Calculator Metric | Traditional 401(k) | Roth 401(k) |
|---|---|---|
| Annual Contribution | $10,000 (Pre-Tax) | $10,000 (After-Tax) |
| Upfront Annual Tax Cost | $0 | $2,200 (at 22% bracket) |
| Projected Balance (25 Yrs at 7%) | $632,490 | $632,490 |
| Taxes Owed at Withdrawal | $113,848 (at 18% retirement rate) | $0 |
| Net Spendable Value | $518,642 | $632,490 |
By using tools like the Roth and 401(k) calculator | John Hancock Retirement , you can plug in your exact tax brackets to see where your personal tipping point lies. If you want to check out our full suite of interactive tools, explore our comprehensive finance calculator tools.
Understanding the Break-Even Tax Rate
The break-even tax rate is the exact retirement tax rate at which both the Traditional and Roth 401(k) produce the identical amount of after-tax spendable wealth.
If your actual retirement tax rate is higher than the break-even rate, the Roth 401(k) wins because you locked in a lower tax rate during your working years. If your retirement tax rate is lower than the break-even rate, the Traditional 401(k) wins because you successfully avoided high taxes during your peak earning years and paid a lower rate later.
Calculating this rate requires a sensitivity analysis. Most people assume they will be in a lower tax bracket in retirement because they won’t have a salary. However, when you factor in Social Security, taxable pensions, and RMDs from pre-tax accounts, your retirement taxable income might be higher than you think.
The Power of Reinvesting Tax Savings
One major mistake people make when comparing these accounts is forgetting about the tax savings generated by the Traditional 401(k) deduction.
If you contribute $10,000 to a Traditional 401(k) while in the 24% marginal tax bracket, you save $2,400 on your tax bill this year. To make a true “apples-to-apples” comparison with a Roth 401(k), you have to assume that you take that $2,400 in tax savings and invest it in a taxable brokerage account.
Over 30 years, that reinvested tax savings will compound significantly. Even though the brokerage account will be subject to capital gains taxes, the sheer volume of extra compounded money often allows the Traditional 401(k) + Brokerage strategy to beat a pure Roth strategy, especially for high earners.
If you are looking for other ways to put your extra cash to work outside of standard workplace accounts, check out these alternative ways to save for retirement that actually work.
Strategic Scenarios: Who Wins the Roth vs. Traditional Debate?
Because financial planning is highly personal, the right choice depends heavily on where you are in your career and what your income looks like.
Early-Career Workers and Low Earners
If you are early in your career or currently earning a moderate income (under $80,000 as a single filer), the Roth 401(k) is almost always the undisputed champion.
At lower income levels, your current marginal tax bracket is likely the lowest it will ever be. Paying a 10% or 12% tax rate today to secure decades of tax-free compounding is one of the smartest financial moves you can make. Since you have a long time horizon before retirement, the tax-free growth of your compounding interest will far outweigh the minor tax deduction you would get today from a Traditional contribution.
Peak Earners and High Income Strategies
If you are a high earner (earning over $150,000 as a single filer or $300,000 married jointly), the Traditional 401(k) is usually the superior choice.
When you are in the 24%, 32%, or 35% tax brackets, saving on taxes today is incredibly valuable. A Traditional 401(k) contribution allows you to dodge those high tax rates now. When you retire, you can systematically withdraw that money, filling up the lower tax brackets (10% and 12%) first.
For high earners who still want Roth exposure, a common strategy is to maximize the pre-tax Traditional 401(k) first, and then execute a backdoor Roth conversion using an IRA. If you are trying to balance multiple income streams and retirement plans, navigating pension vs 401k tax strategies for working retirees can help you keep your tax burden as low as possible.
The Role of Employer Match and Account Rules
No matter which account you choose, there is one rule that rises above all others: always capture the full employer match.
An employer match is literally free money. If your company matches 50% of your contributions up to 6% of your salary, that is an immediate, guaranteed 50% return on your investment before the market even moves.
To make sure you are squeezing every drop of value out of your workplace plan, read our guide: don’t leave money on the table: the ultimate 401k max calculator guide.
How Employer Matching Works
There is a vital detail about employer matches that catches many savers off guard: employer matching contributions are almost always pre-tax.
Even if you choose to make 100% of your personal contributions to a Roth 401(k), your employer’s matching funds will go into a Traditional, pre-tax bucket. This means that when you retire, you will have a mix of tax-free Roth money (your contributions and their growth) and taxable Traditional money (your employer’s match and its growth). The match portion will be taxed as ordinary income upon withdrawal.
401(k) vs. Roth IRA: Key Differences
If you are deciding where to route your next dollar of savings, it helps to understand how the Roth 401(k) stacks up against a standalone Roth IRA:
- Income Limits: Roth IRAs have strict income limits. In 2026, if your modified AGI is over $161,000 (single) or $240,000 (married filing jointly), you cannot contribute directly to a Roth IRA. The Roth 401(k) has no income limits. High earners can contribute directly to a Roth 401(k) regardless of how much they make.
- Contribution Limits: The Roth 401(k) allows you to save up to $24,500 in 2026, while the Roth IRA is limited to just $7,000 (plus a $1,000 catch-up if age 50+).
- Investment Options & Fees: A Roth IRA can be opened at almost any discount brokerage, giving you access to thousands of low-fee index funds and ETFs. A 401(k) plan is limited to the specific menu of funds chosen by your employer’s plan administrator, which can sometimes carry higher administrative fees.
To run a detailed comparison of your options, you can use the Roth 401k vs 401k | Retirement Savings Calculator to see how different fee structures and matching plans affect your final balance.
Frequently Asked Questions About 401(k) Planning
How does a 401k vs Roth calculator handle employer matching?
A high-quality calculator separates your personal contributions from your employer’s matching contributions. Because the employer match is made on a pre-tax basis, the calculator will apply your projected retirement tax rate to the matched portion of your nest egg while keeping your personal Roth contributions completely tax-free. It also factors in vesting schedules to ensure only the funds you actually own are included in the long-term growth projection.
When should I use a 401k vs Roth calculator to plan for early retirement?
If you plan to retire before age 59½, you need to plan your withdrawals carefully to avoid early withdrawal penalties. A calculator can help you balance your pre-tax and after-tax buckets so you can use strategies like Roth conversion ladders or Substantially Equal Periodic Payments (SEPP).
To see how your withdrawal rate affects your long-term portfolio survival, check out our guide on demystifying the 4 percent retirement withdrawal calculator.
Are there income limits for Roth 401(k) contributions?
No. Unlike a Roth IRA, there are absolutely no income phase-out limits for a Roth 401(k). Even if you earn a high salary, you can contribute the full $24,500 elective deferral limit directly to a Roth 401(k) in 2026.
Conclusion
At the end of the day, the debate between Roth and Traditional 401(k) accounts isn’t about finding a single “perfect” mathematical answer. It is about building a personalized, sustainable plan that fits your current lifestyle and protects your future wealth.
By using a 401k vs Roth calculator, you can replace vague rules of thumb with clear, data-driven projections tailored to your unique income and career stage. Whether you decide to lock in tax-free growth with a Roth, take a valuable deduction today with a Traditional, or split the difference to build a diversified tax hedge, taking action today is what matters most.
If you want to take the guesswork out of your financial future, stop guessing and start planning with the best retirement planning tools and explore our comprehensive finance calculator tools today!