The Best SEP IRA Accounts to Open in 2026
Finding the best SEP IRA provider can mean thousands of extra dollars saved for retirement — tax-free until you withdraw. Here’s a quick look at the top picks before we dive deeper:
Top SEP IRA Providers at a Glance:
| Provider | Best For | Annual Fee | Minimum Balance |
|---|---|---|---|
| Fidelity | Best overall | $0 | $0 |
| Charles Schwab | Low-cost self-directed | $0 | $0 |
| Vanguard | Long-term index investors | $25/month (under $100k) | $0 |
| Wealthfront | Hands-off/automated | 0.25% annually | $500 |
| SoFi | Beginners | 0.25% managed | $0 |
If you’re self-employed, a freelancer, or a small business owner, retirement planning often falls to the bottom of the to-do list. There’s no HR department setting up a 401(k) for you. No employer match landing in your account each pay period. You’re on your own.
That’s exactly where a SEP IRA shines.
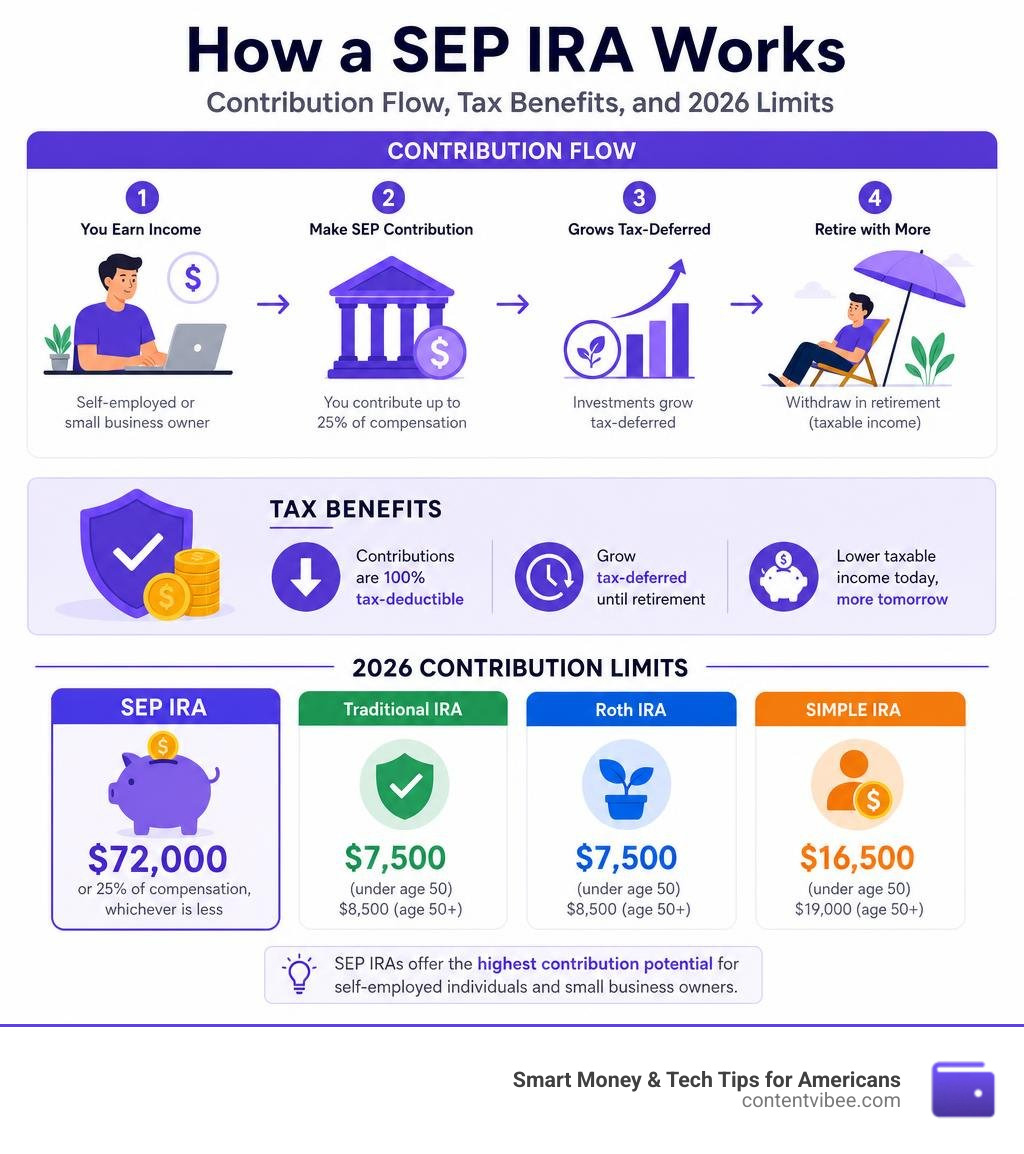
A SEP IRA — Simplified Employee Pension Individual Retirement Account — lets you contribute up to $72,000 in 2026 (or 25% of compensation, whichever is less). That’s nearly ten times the standard IRA limit of $7,500. And every dollar you contribute is tax-deductible, reducing your income today while your money grows tax-deferred for retirement.
The catch? Not all providers are equal. Fees, investment options, ease of setup, and support for employees vary widely. Picking the wrong one can cost you in hidden fees or limit how you invest.
This guide compares the best options available right now so you can make a confident choice.
Best sep ira definitions:
What is a SEP IRA and Who is It Best Suited For?
A Simplified Employee Pension (SEP) IRA is a specialized retirement plan designed specifically for business owners, freelancers, sole proprietors, and independent contractors. Think of it as a traditional IRA on financial steroids. It offers the same tax-deferred growth and tax-deductible contributions, but with vastly higher contribution limits.
The beauty of a SEP IRA lies in its simplicity. Unlike a traditional 401(k) plan, there are no annual IRS Form 5500 filings to worry about if you follow basic setup rules. This makes it incredibly low-maintenance and highly cost-effective for busy entrepreneurs who would rather focus on growing their business than managing complex retirement administration.
A SEP IRA is best suited for:
- High-earning freelancers and solopreneurs who want to shield a significant portion of their active income from income taxes.
- Small business owners with few or no employees who want a straightforward, flexible retirement plan without administrative headaches.
- Side-hustlers who have W-2 jobs but also generate self-employment income and want to save extra cash.
According to the official IRS rules on SEP eligibility, any business owner, including sole proprietors, partnerships, and corporations, can establish a SEP.
Employee Eligibility and Participation Rules
If you run a business with employees, the SEP IRA rules change slightly. The IRS has strict guidelines regarding who must be included in your plan. Under the standard “3-of-5” rule, an employee is eligible to participate if they:
- Are at least 21 years old.
- Have performed services for your business in at least 3 of the last 5 years.
- Received at least $750 in compensation from your business during the year.
The most critical rule to understand is that all contributions to a SEP IRA are 100% employer-funded. Employees cannot make their own salary deferrals into a SEP. Furthermore, you must contribute an equal percentage of compensation for all eligible employees, including yourself.
For example, if you decide to contribute 15% of your own net self-employment earnings to your SEP IRA, you must also contribute exactly 15% of each eligible employee’s salary to their respective SEP IRAs. Because of this equal percentage rule, a SEP IRA can become very expensive if you have a larger team of eligible employees.
SEP IRA Contribution Limits and Tax Rules for 2026
When it comes to building wealth, understanding the tax code is your superpower. For the 2026 tax year, the SEP IRA contribution limits are highly generous.
An employer can contribute up to 25% of an employee’s compensation, or a maximum of $72,000, whichever is less. This is an increase from the $70,000 limit in 2025.
To prevent high earners from sheltering unlimited amounts of cash, the IRS indexes the eligible compensation limit for inflation. For 2026, the maximum compensation that can be used to calculate your contribution is $360,000 (up from $350,000 in 2025).
Every dollar contributed to a standard SEP IRA is tax-deductible for the business, which directly lowers your adjusted gross income (AGI) for the year. The funds then grow tax-deferred, meaning you won’t pay a single cent of capital gains taxes as your investments compound over the decades. Taxes are only paid when you take qualified withdrawals in retirement. To explore more ways to keep your hard-earned money out of Uncle Sam’s pockets, read up on Smart strategies to defer taxes and boost your retirement savings.
Calculating Self-Employed SEP Contributions
If you are a sole proprietor or a single-member LLC, calculating your maximum contribution is slightly more complex than just multiplying your profit by 25%. Because you are considered both the employer and the employee, you must use a circular calculation.
Your contribution is based on your net self-employment earnings, which is your gross business profit minus your self-employment tax deduction. Because of this adjustment, the effective maximum contribution rate for a self-employed individual is actually 20% of net self-employment income, rather than 25%.
Using IRS Publication 560 worksheets is highly recommended to ensure you do not overcontribute. For a broader look at how different retirement calculations work, check out The Ultimate Guide to Calculating Your 401k Contributions.
SECURE 2.0 and Roth SEP IRA Contributions
One of the most exciting updates in recent retirement history comes courtesy of the SECURE Act 2.0. Historically, all SEP IRA contributions had to be pre-tax (traditional). However, the new law now allows business owners to offer after-tax Roth SEP IRA contributions.
With a Roth SEP IRA, you pay income tax on the contributions today, but the money grows completely tax-free, and qualified withdrawals in retirement are 100% tax-free.
While this is legally permitted, keep in mind that many traditional brokerages are still updating their systems to support Roth SEP IRAs. If you want to maximize your after-tax growth, consult your chosen custodian to see if they have fully implemented this feature. For more details on utilizing after-tax strategies, read our guide on After-Tax Contributions: How to Maximize Your Retirement Nest Egg.
How to Choose the Best SEP IRA Provider for Your Business
Selecting where to open your account is just as important as deciding how much to save. The right platform will offer a seamless user experience, robust customer support, and low overhead costs.
When evaluating potential providers, pay close attention to:
- Account Minimums: Look for platforms with $0 minimum deposit requirements so you can start saving immediately.
- Administrative Fees: The top brokerages charge $0 in setup or annual maintenance fees. Avoid companies that charge ongoing “custodial” fees.
- Setup Process: Some brokerages allow you to open a SEP IRA online in minutes, while others require paper applications if you have employees.
Many self-employed individuals turn to online communities like the Bogleheads forum discussion on where to open a SEP IRA to read real-world feedback on platform stability and customer service before making their final decision.
Evaluating Fees and Investment Options for the Best SEP IRA
To find the best SEP IRA for your needs, you must look closely at the underlying investment menu and fee schedule.
If you plan to build your own portfolio, look for brokerages like Fidelity or Charles Schwab that offer commission-free trading on US stocks and ETFs. They also provide access to thousands of low-cost, institutional-grade mutual funds. Avoiding transaction fees and high expense ratios is one of the easiest ways to accelerate your retirement compounding.
Traditional Brokerages vs. Robo-Advisors: Finding the Best SEP IRA Platform
Are you a hands-on investor who enjoys researching stocks and ETFs, or would you prefer to set it and forget it?
- Traditional Brokerages: Platforms like Fidelity and Schwab are ideal for self-directed investors. They give you complete control over your asset allocation.
- Robo-Advisors: Platforms like Wealthfront and Betterment are perfect for hands-off business owners. For a small annual advisory fee (typically around 0.25%), they will automatically build, rebalance, and optimize a diversified portfolio of low-cost ETFs based on your risk tolerance.
If you are looking for alternative pathways to build long-term wealth, check out these Alternative ways to save for retirement.
Standard SEP IRAs vs. Self-Directed SEP IRAs for Alternative Assets
Standard brokerages limit your investment options to publicly traded assets like stocks, bonds, mutual funds, and ETFs. But what if you want to use your retirement funds to buy real estate, physical gold, or cryptocurrency?
That is where a Self-Directed SEP IRA (SDIRA) comes in.
With a self-directed custodian, you can establish “checkbook control” over your retirement funds, allowing you to invest in alternative assets directly. While the earning potential can be high, SDIRAs come with higher administrative fees and strict IRS rules regarding prohibited transactions. If you want to explore alternative investing, you can learn more about how to Open a Self-Directed SEP IRA through specialized custodians.
SEP IRA vs. Solo 401(k) and Other Retirement Plans
Before committing to a SEP IRA, it is wise to compare it to other popular self-employed retirement vehicles, such as the Solo 401(k) and the SIMPLE IRA.
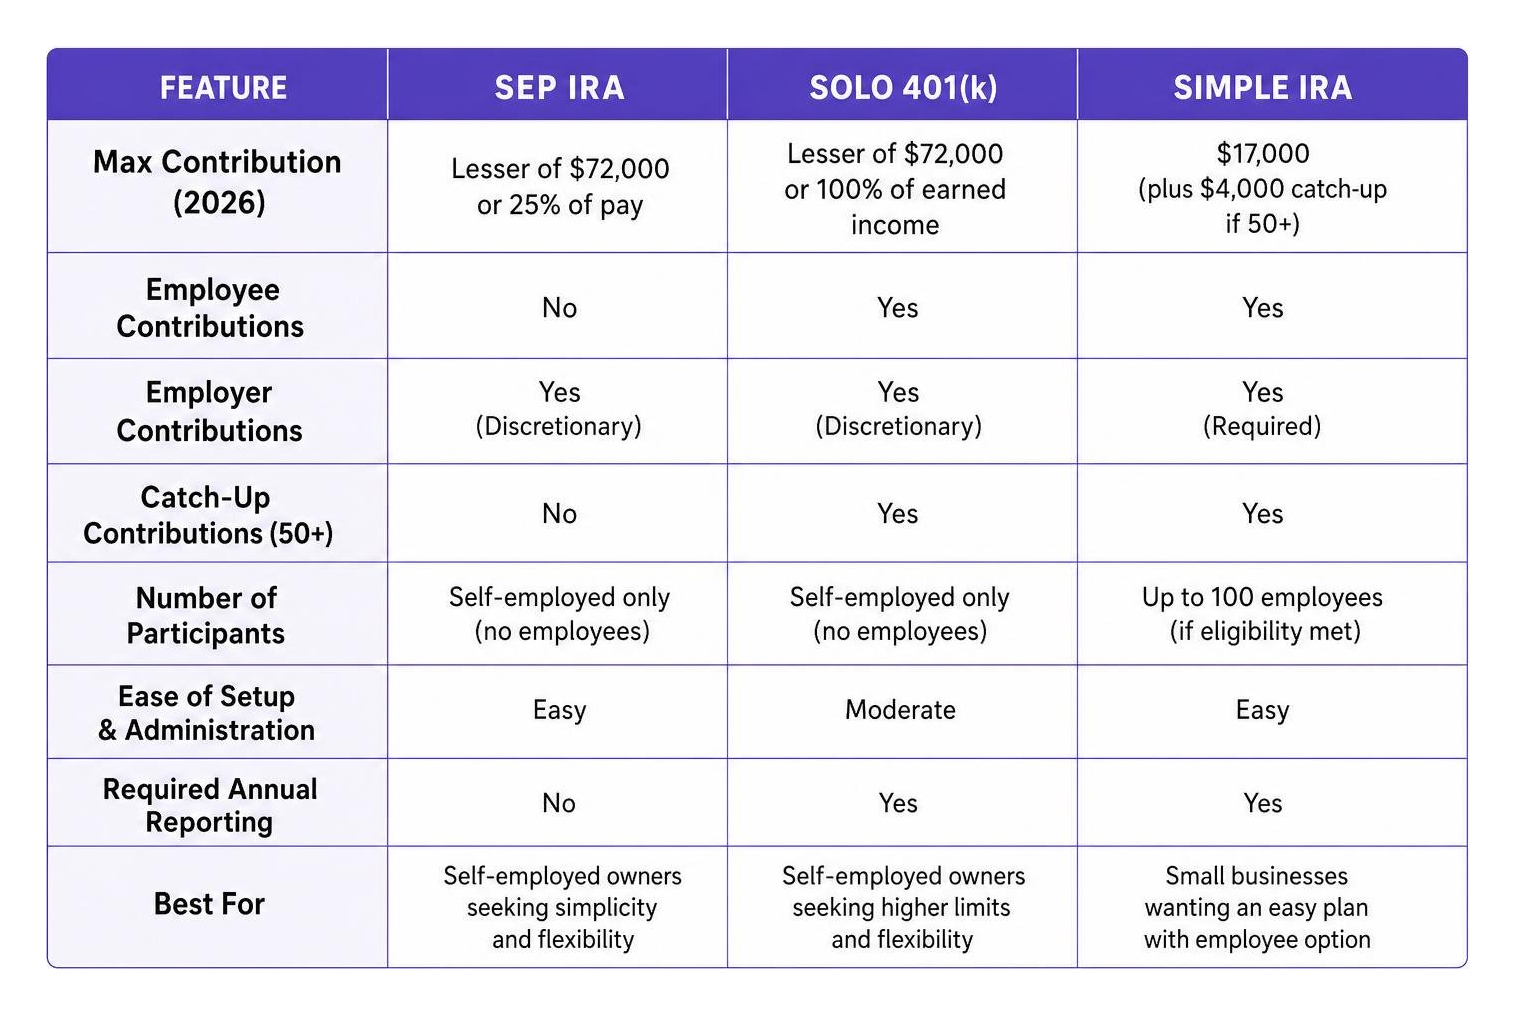
Here is a quick breakdown of how these plans compare for the 2026 tax year:
| Feature | SEP IRA | Solo 401(k) | SIMPLE IRA |
|---|---|---|---|
| Max Contribution (2026) | Lesser of $72,000 or 25% of pay | Lesser of $72,000 or 100% of earned income | $17,000 (plus $4,000 catch-up if 50+) |
| Who Contributes | Employer only | Employer & Employee | Employer & Employee |
| Administrative Burden | Very Low (No Form 5500) | Moderate (Form 5500-EZ if assets >$250k) | Low |
| Loan Provisions | Prohibited | Allowed (up to $50,000) | Prohibited |
| Catch-up Contributions | No | Yes ($7,500 for age 50+) | Yes ($4,000 for age 50+) |
To weigh the differences between traditional tax-deferred plans and Roth options, refer to The Great Retirement Debate: Roth vs Traditional 401k Calculator Guide.
The Solo 401(k) Advantage for Solopreneurs
If you are a true solopreneur with no employees (except potentially a spouse), the Solo 401(k) often beats the SEP IRA, especially at lower income levels.
This is known as the low-income advantage. Because a Solo 401(k) allows you to contribute both as an employee (up to $24,500 in salary deferral for 2026) and as an employer (up to 25% of profit), you can shelter far more money at lower income brackets.
For example, if your net business profit is $50,000:
- A SEP IRA limits your contribution to roughly $10,000.
- A Solo 401(k) allows you to contribute up to $34,500.
Additionally, Solo 401(k) plans do not trigger the IRS Pro-Rata Rule, protecting your ability to execute Backdoor Roth IRA conversions. They also permit tax-free personal loans of up to 50% of your account balance (max $50,000), which is strictly illegal inside a SEP IRA. For a look at how early withdrawal exceptions work, read up on Retirement Topics: Exceptions to Tax on Early Distributions at 55.
Frequently Asked Questions About SEP IRAs
Can I contribute to both a SEP IRA and a Traditional or Roth IRA in 2026?
Yes! You can absolutely contribute to both a SEP IRA and a personal Traditional or Roth IRA in the same year. For 2026, the individual IRA contribution limit is $7,500 ($8,600 if you are age 50 or older).
However, keep in mind that participating in a SEP IRA makes you an “active participant” in an employer retirement plan. This means your ability to deduct your Traditional IRA contributions may be phased out or eliminated if your adjusted gross income exceeds certain IRS thresholds.
What is the deadline to set up and fund a SEP IRA?
One of the greatest advantages of the SEP IRA is its incredible flexibility. Unlike a Solo 401(k), which must be established by December 31 of the tax year, a SEP IRA can be established and funded retroactively.
You have until your business’s federal income tax filing deadline, including extensions, to set up the plan and make your contributions. For many sole proprietors, this means you can establish and fund your 2025 contribution as late as October 15, 2026.
What happens if I overcontribute to my SEP IRA?
If you accidentally contribute more than the allowable limits, the IRS will impose a 6% annual excise tax on the excess amount until it is corrected.
To avoid this penalty, you must request a corrective distribution from your custodian. This involves withdrawing the excess contribution plus any net income attributable to those funds before your tax filing deadline (including extensions). Your custodian will then report this correction on Form 5498.
Conclusion
Taking control of your financial future is one of the most rewarding steps you can take as an entrepreneur. A SEP IRA offers a perfect blend of high contribution limits, tax-deductible power, and low administrative burden.
Whether you opt for a self-directed brokerage like Fidelity, a hands-off robo-advisor like Wealthfront, or a specialized self-directed custodian for real estate and crypto, the most important step is simply getting started.
At ContentVibee, we are dedicated to helping you make smart, actionable money decisions that protect your wealth and optimize your taxes. As you plan your long-term retirement strategy, make sure you understand how your future income will be treated by reading our essential guide on Understanding taxes on Social Security.