


More Americans Are Working Past Retirement — And Discovering Perks They Never Expected
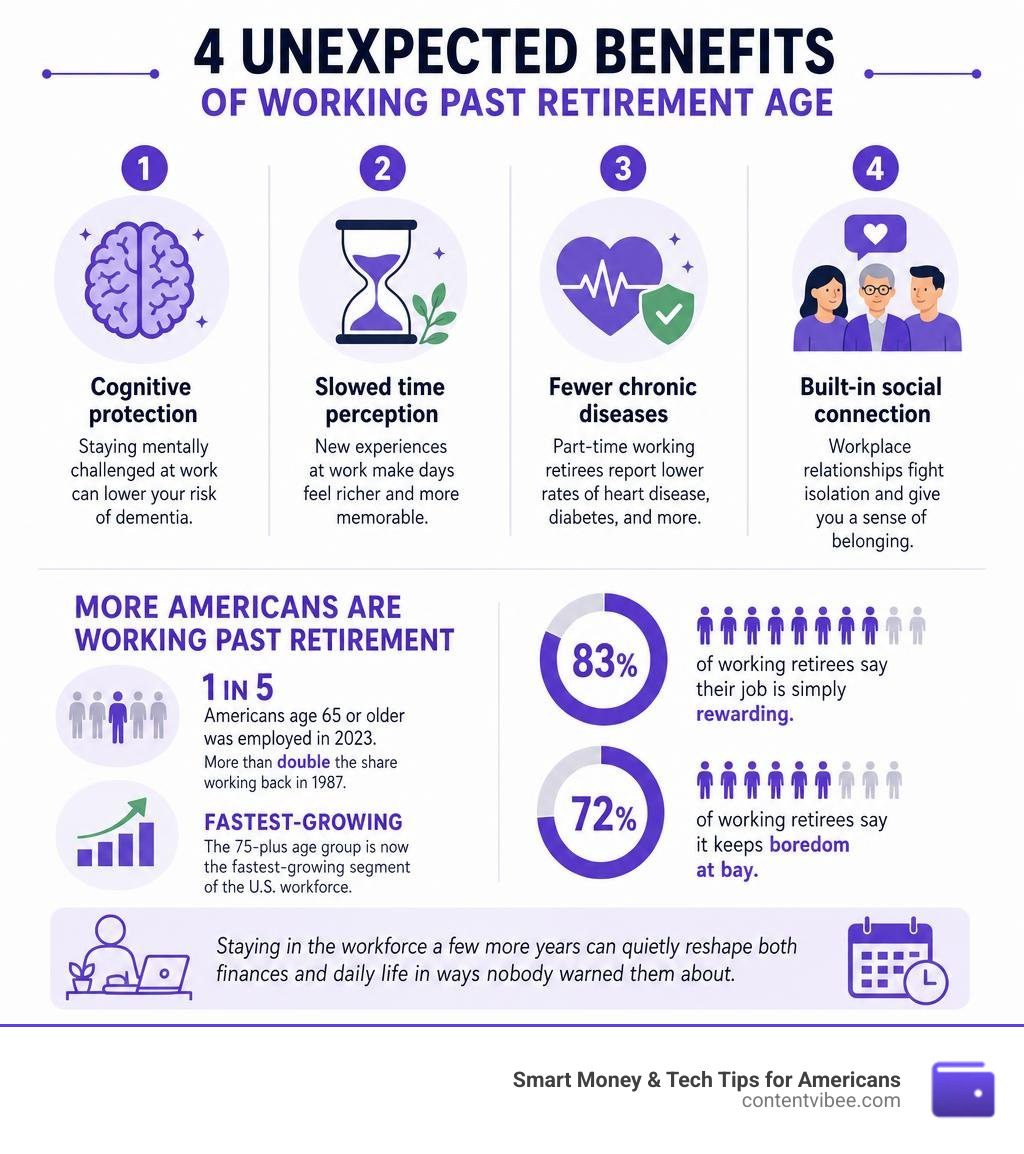
There are 4 unexpected benefits of working past retirement age that most people never see coming — and they go far beyond a bigger paycheck.
Here’s a quick look at what they are:
- Cognitive protection — Staying mentally challenged at work can lower your risk of dementia.
- Slowed time perception — New experiences at work make days feel richer and more memorable.
- Fewer chronic diseases — Part-time working retirees report lower rates of heart disease, diabetes, and more.
- Built-in social connection — Workplace relationships fight isolation and give you a sense of belonging.
If you’re nearing retirement and weighing whether to keep working, you’re in good company. In 2023, roughly 1 in 5 Americans age 65 or older was employed — more than double the share working back in 1987. The 75-plus age group is now the fastest-growing segment of the U.S. workforce.
And it’s not just about money. Research shows 83% of working retirees say their job is simply rewarding, and 72% say it keeps boredom at bay.
For many, especially those navigating spousal Social Security rules or watching savings stretch thinner against rising costs, staying in the workforce a few more years can quietly reshape both finances and daily life in ways nobody warned them about.
Important 4 unexpected benefits of working past retirement age terms:
- retirement jobs for seniors
- seniors working past retirement
- can you collect a pension and still work full-time
The Shift in Modern Retirement: Why Seniors Are Staying in the Workforce
The golden years aren’t what they used to be. Decades ago, retirement was viewed as a hard stop—a single day when you packed up your desk, accepted a gold watch, and walked away from the workforce forever. Today, that rigid boundary has dissolved. Retirement has transitioned from a finish line into a dynamic, highly personalized phase of life.
The numbers paint a clear picture of this shifting landscape. Nearly half a million Americans over the age of 80 are actively employed, and the 75-plus demographic stands as the fastest-growing segment of the entire U.S. workforce. In fact, about 9% of Americans aged 75 and older are currently employed—more than double the rate recorded in 1987.
Why are so many seniors choosing to keep their day jobs or even “unretire” after years away? For many, the decision is a mix of financial necessity and personal fulfillment. Long-held cultural expectations about working after age 62 heavily influence our life satisfaction. When we expect to work longer and successfully do so, we maintain a strong sense of agency. Conversely, when workers are forced into unexpected early retirement due to health issues or layoffs, their subjective well-being can take a significant hit.
Economic realities also play a massive role. Persistent inflation, rising healthcare costs, and multigenerational family obligations mean that even those who saved diligently for decades are finding their portfolios stretched thin. Staying in the workforce serves as a powerful shield for your retirement portfolio. By earning an active income, you reduce the need to withdraw money from your 401(k) or IRA, especially during volatile market cycles. This allows your remaining investments more time to compound and grow.
If you are wondering whether staying employed is the right path for you, explore our guide on why so many not ready for the rocking chair why seniors are staying in the workforce to understand this cultural and economic evolution. You can also read more about why retirees are returning to work even after saving for decades on Why So Many Retirees Are Returning To Work Even After Saving for Decades – AOL .
4 Unexpected Benefits of Working Past Retirement Age
While the financial benefits of an ongoing paycheck are obvious, the non-financial perks of continuing to work are often the most surprising. For many older adults, a job provides a profound sense of identity, vitality, and daily structure that leisure alone simply cannot replicate.
According to data from the Employee Benefit Research Institute (EBRI), the motivations for working in later life extend far beyond basic survival:
- 84% work to fund discretionary lifestyle expenses (like travel or hobbies).
- 83% work because they find their job personally rewarding.
- 72% work to avoid boredom and maintain a structured routine.
- 63% work to socialize and maintain a vibrant community.
- 59% work to learn new skills and experience novel environments.
When we shift our perspective from seeing work as a chore to viewing it as an avenue for personal growth, the advantages multiply. Let’s dive deep into the 4 unexpected benefits of working past retirement age that can drastically improve your physical, mental, and emotional well-being. To read more about how continuing to work past age 60 can create a deeply fulfilling life, check out The Benefits of Working Past 60: A Guide to a Fulfilling Retirement (2026) and explore the non-financial motivators detailed in The Top 8 Reasons Why People Work in Retirement (4 Have … .
1. A Surprising Cognitive Shield: How Continued Work Fights Dementia
One of the most profound benefits of staying in the workforce is the preservation of your mental sharpness. The human brain operates on a “use it or lose it” principle. When you retire fully and transition into a highly repetitive, low-challenge routine, your cognitive reserve can begin to decline.
Working past retirement age acts as a natural cognitive shield. When you stay busy, solve problems, navigate workplace dynamics, and challenge yourself, you are actively building new neural pathways. This sustained mental engagement makes you significantly less likely to develop dementia or experience rapid cognitive decline.
The key to unlocking these mental benefits lies in choosing work that stimulates your brain without introducing chronic, toxic stress. Learning new skills—such as mastering modern office technologies, adapting to new software, or managing project logistics—keeps your brain plastic and resilient. If you’d like to learn more about how staying engaged in the workforce protects your mind and keeps you sharp, read Why Working Longer Could Be the Best Decision for Your Retirement | Purpose, Social Ties, and More (2026) .
2. The Time-Dilation Effect: How New Experiences Slow Down Your Perception of Time
Have you ever noticed how quickly the years seem to fly by as you get older? When every day looks exactly the same, your brain stops recording detailed memories, causing weeks and months to blur together into a single, rapid stream. This is where the fascinating concept of “time dilation” comes in.
According to research by Stanford neuroscientist David Eagleman, our perception of time is heavily tied to novelty. When you experience new things, your brain takes more time to process the information, making the subjective experience of time pass more slowly. In contrast, a highly predictable routine makes time feel like it is slipping through your fingers.
By continuing to work—especially in a role that introduces new challenges, clients, or skills—you inject constant novelty into your life. This makes your days far more memorable, effectively functioning as a psychological time machine that stretches your golden years and keeps boredom at bay.
3. Unexpected Health Benefits of Working Past Retirement Age: Lowering Chronic Disease Risks
It sounds counterintuitive: shouldn’t resting and relaxing make you healthier? Surprisingly, the medical data suggests otherwise. Complete physical inactivity and a lack of daily routine can actually accelerate physical decline.
According to research published by Working After Retirement: Is It Right for You? – WebMD , older adults who transition into part-time or flexible work after retirement have significantly fewer serious, chronic diseases than those who stop working entirely. The active lifestyle associated with holding a job—even a low-intensity, part-time position—is linked to lower rates of:
- High blood pressure
- Type 2 diabetes
- Various forms of cancer
- Chronic lung disease
- Heart disease and stroke
- Psychiatric problems, including clinical depression and anxiety
Having a reason to get out of bed, get dressed, walk, and move around keeps your cardiovascular system active and your muscles engaged. The structure of a job naturally encourages physical movement, helping you maintain vitality well into your 70s and 80s.
4. The Social Buffer: Forging Intergenerational Connections and Beating Isolation
Social isolation is one of the greatest risks facing retirees today. Loneliness in older adults has been linked to health risks equivalent to smoking 15 cigarettes a day. When you leave the workforce, you instantly lose a massive, built-in network of daily social contact.
Continuing to work provides a powerful social buffer. Workplace friendships deliver a deep sense of belonging and community. Furthermore, staying in the workforce allows you to forge intergenerational connections. Working alongside younger colleagues gives you the unique opportunity to pass on your decades of hard-won wisdom, which is a deeply rewarding and mutually enriching experience.
At the same time, collaborating with younger generations keeps you in touch with modern cultural shifts, new technologies, and fresh perspectives, preventing you from feeling left behind by a fast-moving world.
Financial Advantages and Hidden Risks of Working Past Age 62
While the health and mental perks of working are incredible, we can’t ignore the financial math. Continuing to earn wages past age 62 offers massive financial advantages, but it also introduces unique regulatory, tax, and benefit rules that you must navigate carefully.
First, let’s look at the compounding power of delaying retirement. If you have a portfolio of $1.4 million earning a modest 5% annual return, working five years longer (retiring at age 72 instead of 67) and allowing that money to compound without making any withdrawals can add nearly $400,000 to your nest egg, bringing your balance close to $1.8 million.
To help you weigh your options, we’ve summarized the key financial pros and cons of working past age 65:
| Financial Pros of Working Past 65 | Financial Cons & Risks to Consider |
|---|---|
| Allows retirement savings to compound longer without withdrawals | Earned income can push you into a higher federal income tax bracket |
| Increases your lifetime Social Security benefit by 8% per year delayed (up to age 70) | May trigger temporary withholding of Social Security benefits if under Full Retirement Age (FRA) |
| Continued access to employer-sponsored health insurance | Up to 85% of your Social Security benefits may become taxable based on combined income |
| Opportunity to make catch-up contributions to 401(k) and IRA accounts | Enrolling in Medicare Part A or B makes you ineligible to contribute to a Health Savings Account (HSA) |
Maximizing Social Security and Delaying RMDs
One of the smartest financial moves you can make by working longer is delaying your Social Security claim. For every year you delay claiming your benefits past your Full Retirement Age (FRA)—which is between 66 and 67 depending on your birth year—your monthly check permanently increases by approximately 8% per year, up to age 70.
Additionally, working past traditional retirement age can help you defer Required Minimum Distributions (RMDs). Generally, the IRS requires you to start taking withdrawals from traditional IRAs and 401(k)s at age 73 or 75. However, if you are still actively employed by the company sponsoring your 401(k) plan, and you own 5% or less of that business, you can typically defer taking RMDs from that specific employer plan for as long as you keep working there.
To make sure you don’t lose a penny of your hard-earned benefits to federal penalties, read our expert guide on how to avoid the dreaded Social security earnings limit penalty.
Navigating the Tax and Medicare Implications of Working Past Retirement Age
Working in your golden years requires a careful eye on taxes and healthcare. If your combined income (adjusted gross income + tax-exempt interest + half of your Social Security benefits) exceeds $34,000 as an individual or $44,000 as a married couple filing jointly, up to 85% of your Social Security benefits can become subject to federal income tax.
Furthermore, you must coordinate your employer’s health insurance with Medicare. While you become eligible for Medicare at age 65, you may choose to delay enrolling in Medicare Part B if your current employer has 20 or more employees and provides creditable group health coverage. This can save you money on monthly premiums. However, be aware of the strict HSA rule: the moment you enroll in any part of Medicare (including Part A), you are legally prohibited from making further tax-free contributions to a Health Savings Account (HSA).
If you’re married, you must also understand how your ongoing employment affects your household. Dive into our breakdown of working in retirement are spousal benefits reduced by working to ensure your joint financial strategy remains airtight.
Balancing Flexibility and Structure: Practical Steps for Older Adults
If you want to reap the benefits of working without sacrificing your hard-earned freedom, you don’t have to commit to a stressful, 40-hour-a-week grind. The modern labor market offers incredible flexibility for seniors who want to design their own schedules.
Many older adults opt for “bridge jobs”—temporary, part-time, or lower-stress positions that act as a step-down transition between a full-time career and complete retirement. Others pivot to consulting in their former industry, turning decades of expertise into high-paying, project-based work on their own terms.
To help you get started, explore our curated list of the absolute best jobs after retirement to keep you active and discover how to transition smoothly using bridge jobs to help you ease into retirement. If you love the idea of absolute autonomy, you can also learn how to master the gig economy in retirement to find flexible freelance work that fits your lifestyle perfectly.
Before making any final decisions, we highly recommend consulting with a certified financial planner (CFP), an elder law attorney, and your primary care physician. Together, they can help you evaluate the impact of continued work on your retirement accounts, tax brackets, healthcare options, and physical stamina.
Frequently Asked Questions About Working Past Retirement
Does working after retirement reduce my Social Security benefits?
If you have reached your Full Retirement Age (FRA), you can earn as much as you want with absolutely no reduction to your Social Security benefits. However, if you claim benefits before reaching your FRA and continue to work, you are subject to an annual earnings limit. If you earn over this limit, the Social Security Administration will temporarily withhold a portion of your benefits. Rest assured, these withheld funds are not lost forever; once you reach FRA, your monthly benefit will be permanently adjusted upward to account for the withheld amounts.
Can I still contribute to an HSA or 401(k) if I work past age 65?
You can absolutely continue to contribute to an employer-sponsored 401(k) or a traditional/Roth IRA as long as you have earned income. If you are age 50 or older, you can also take advantage of catch-up contribution limits. However, for Health Savings Accounts (HSAs), you can only contribute if you have not enrolled in any part of Medicare. Once you enroll in Medicare Part A or B, you can no longer make tax-advantaged contributions to an HSA.
How does working past retirement age affect my mental sharpness?
Working past retirement keeps your mind sharp by promoting cognitive engagement, problem-solving, and social interaction. Challenging your brain with new tasks, learning modern software, and collaborating with coworkers stimulates neuroplasticity, which helps preserve your cognitive reserve and significantly lowers your overall risk of developing dementia.
Conclusion
At ContentVibee, we believe that retirement is not a one-size-fits-all destination. It is a highly personalized journey. For many, continuing to work past traditional retirement age is the ultimate life hack—providing a powerful blend of financial security, mental sharpness, physical health, and deep personal fulfillment.
By taking a proactive, informed approach to your retirement planning, you can design a life that offers both the structure you need to thrive and the flexibility you’ve earned. Whether you choose to consult, take on a fun part-time job, or dive into the gig economy, the choice is entirely yours.
To make sure your family’s financial plan is fully optimized, don’t miss our comprehensive guide on working in retirement are spousal benefits reduced by working to keep your household benefits secure and growing.


